

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Image Signal Processor and Vision Processor Market to Expand at 9.16% CAGR, Reach USD 10,715.05 Million by 2032

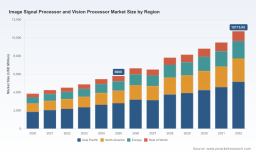
Image Signal Processor and Vision Processor Market: Strategic Imperatives for 2026 Decision-Makers
As demand for edge vision intelligence accelerates across automotive, industrial, security and consumer systems, PW Consulting’s new Image Signal Processor (ISP) and Vision Processor Market report (base year 2025, forecast 2026–2032) provides the strategic intelligence leaders need to navigate a rapidly evolving technology and regulatory landscape. With the market expanding at a compound annual growth rate (CAGR) of 9.16%, and total market value moving from approximately USD 3.85 billion in 2020 to roughly USD 5.8 billion in 2025 — and projected to exceed USD 10.7 billion by 2032 — executives must align product, supply-chain and corporate strategies to capture disproportionate share and minimize exposure to systemic risks.
Image Signal Processor And Vision Processor Market
Why this report matters for 2026 planning
-
Actionable forecasting calibrated for near-term volatility: Our forecast captures a distinct inflection through 2026–2028 where the market normalizes after pandemic-era supply disruptions, followed by an acceleration driven by multi‑sensor automotive systems and software-defined imaging innovations. The forecast explicitly models a modest short-term correction before renewed expansion, enabling finance and product leaders to plan CapEx, inventory and cadence of design wins with a more realistic runway.
Image Signal Processor And Vision Processor Market -
Strategic sensitivity to policy and supply risks: Recent U.S. trade and export policy changes — including ad valorem tariffs under Section 232 on certain advanced computing chips and tightened export controls — materially change sourcing calculus. The report translates those policy shifts into supply-risk scenarios and procurement playbooks for sourcing, qualification and nearshoring that are immediately actionable for 2026 decision cycles.
Image Signal Processor And Vision Processor Market -
Technology roadmap alignment for edge AI: The market is bifurcating around two engineering philosophies — higher-integration system-on-chip (SoC) solutions that embed ISPs and AI accelerators, versus modular approaches that combine best-in-class sensors, companion ISPs and dedicated vision processors. Our analysis maps where each approach wins on power, latency, safety certification and unit-cost at scale, guiding architecture choices for next-generation products.
What’s inside (practical, non-generic deliverables)
-
Executive dashboard and GTM prioritization matrix — shortlists high-opportunity segments and timing windows framed to 2026 product cycles without disclosing proprietary segment splits. These prioritize opportunities by addressable market growth, regulatory exposure and design‑in lead times.
-
Supplier risk-heatmap and mitigation playbook — identifies single-source and geo‑concentrated risks, recommended dual‑sourcing strategies, and a three-tier contingency plan for critical components and processed minerals exposed to new trade measures.
-
Procurement and NRE optimization guide — model clauses for wafer and module long‑lead contracts, recommended buffer strategies given current IC lead times (observed industry trends in early 2026 show certain families trending toward 30–42 week lead times), and scenarios for onshore vs. offshore sourcing to balance total landed cost and regulatory compliance.
-
Technical decision framework — comparative scorecards for integrated ISPs, dedicated vision processors, and sensor‑level intelligent solutions, including metrics for power-per-inference, multi-sensor synchronization, and software portability for customers designing into automotive and safety-critical markets.
-
M&A and partnership playbook — valuation sensitivity exercises, target archetypes (IP-rich startups, sensor+ISP integrators, software‑pipeline innovators), and integration risks to watch for in 2026 transactions.
-
Regulatory and standards readiness checklist — a pragmatic set of actions to maintain market access amid export control regimes and process‑specific tariffs affecting advanced computing chips and processed critical minerals.
Competitive landscape — who’s shaping the market and how
The market structure shows meaningful concentration (CR3 ≈ 42.5%; CR5 ≈ 61.8%), indicating that a small group of incumbent semiconductor and vision-system vendors retain substantial influence over technology direction and pricing. Our competitive analysis synthesizes product strategy, go‑to‑market motion, and ecosystem leverage across leading players, with implications for potential entrants and OEM partners.
-
Ambarella Inc. — continues to push high-performance edge SoCs with integrated ISPs and AI accelerators. Its January 2026 CV7 launch on an advanced process node underscores a strategy to capture high-end security, robotics and emerging automotive use-cases where multi-stream 8K processing and on‑device AI matter. For OEMs, Ambarella represents a route to rapid feature differentiation but with premium pricing and integration demands.
-
onsemi (ON Semiconductor) — positions dedicated ISPs as co-processors complementary to leading CMOS sensors and targets automotive and industrial machine vision. Their revenue profile, with substantial exposure to automotive and industrial verticals, signals a conservative, qualification-heavy GTM approach — valuable to customers prioritizing long lifecycle support and qualification rigor.
-
Qualcomm Technologies — leverages mobile SoC heritage to deliver integrated vision intelligence platforms suitable for security cameras, IoT and other edge scenarios where an existing developer ecosystem can accelerate deployment.
-
NXP Semiconductors — brings broad embedded processing platforms (e.g., i.MX families) with dual-ISP architectures and strong automotive-grade ecosystems, appealing to suppliers that need functional safety pathways and longtime partner support.
-
indie Semiconductor — has focused tightly on automotive vision processors that support multi-sensor low-latency processing and high throughput, matching the timing of advanced ADAS and cabin-monitoring deployments.
-
OmniVision, Sony, STMicroelectronics, Texas Instruments and Renesas — each plays distinct roles from sensor/companion ISP pairings and sensor-level intelligence to vision-enabled MCUs/MPUs for industrial and automotive platforms. Their strengths range from sensor/optics co-design to broad distribution and safety-qualified silicon.
-
Chips&Media (with Visionary.ai) — notable as an innovator in software-defined, AI-based ISP pipelines introduced for real-time video enhancement. Such capability points to a future where image quality and scene understanding are increasingly defined by software updates rather than hardware turnover.
Recent product and ecosystem shifts with strategic implications
-
Edge compute performance is moving aggressively: Ambarella’s CV7 and indie’s iND880xx families illustrate a trend toward higher integration and multi-sensor throughput. For OEM planners, this means evaluating whether to invest in single-chip simplification or retain modularity for upgrade flexibility.
-
Software-defined imaging is a differentiator: The industry’s first full AI-based ISP pipeline demonstrates how software and AI models can materially uplift perceived video quality and analytics performance post‑deployment, altering the economics of camera upgrades and licensing.
-
Policy shocks reshape supplier economics: The January 2026 U.S. actions on tariffs and processed critical minerals, combined with export licensing tightening, introduce transactional friction and potential cost uplift for certain high-performance vision processors. Companies that proactively diversify sourcing, qualify alternate silicon, or redesign to less-restricted components will reduce program execution risk.
Practical recommendations for 2026 strategic plans
-
Re-assess architecture trade-offs during Q1–Q2 product planning: Use our decision framework to choose between integrated SoC approaches and modular sensor+ISP flows based on product lifetime, safety requirements and total delivered cost over multiple production runs.
-
Harden supply‑chain playbooks now: Move from vendor selection to vendor qualification for multiple tiers of suppliers. Establish rolling six‑month forecasts, revise long-lead procurement terms, and build contingency contracts for silicon families most exposed to extended lead times.
-
Prioritize software/update monetization models: With software-defined imaging emerging, consider monetizable firmware upgrades and model-delivery subscriptions as part of product roadmaps, enabling revenue capture beyond the initial hardware sale.
-
Prepare M&A and partnership scouting lists: Identify targets that can fill IP gaps (e.g., ISP IP, AI pipelines) or accelerate deployment into regulated markets; our M&A playbook provides valuation sensitivities and integration checkpoints tuned to 2026 market dynamics.
-
Embed regulatory stress-testing in new program gates: For every program slated for 2026–2028 production, include export-control and tariff-scenario checks to avoid late-stage redesigns or certification delays.
Conclusion — how PW Consulting’s report becomes your tactical advantage
For executives preparing budgets, design cycles and strategic partnerships in 2026, the convergence of stronger edge compute, software-oriented imaging, and a shifting policy environment creates both opportunity and risk. PW Consulting’s Image Signal Processor and Vision Processor Market report gives you the integrated market forecast (CAGR 9.16%, detailed year-by-year modeling), supply‑chain and regulatory scenario planning, and a competitive technology playbook to prioritize investments and mitigate execution risk. The report is intentionally prescriptive and operational — designed to be used at the program level by product, procurement, corporate development and legal teams.
To access the full intelligence suite, including proprietary segmentation models, supplier heatmaps, and the complete competitive scorecards that power our recommendations, please consult the full report. Our lenses are calibrated to 2026 decision cadences — pragmatic, prioritized, and ready to influence budgets and roadmaps today.
For detailed analysis of this topic, please visit the official page: Image Signal Processor And Vision Processor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com