

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Report: Primary Cell Media Market Poised for 9.25% CAGR Expansion Through 2026–2032
By pmarketresearch, 2026-07-07
Primary Cell Media Market 2026: Strategic Imperatives from PW Consulting’s New Market Study
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I am pleased to present an executive preview of our Primary Cell Media Market study — the timely intelligence designed to shape enterprise decisions in 2026. This briefing explains why the next 12–18 months are pivotal, how the market’s macro trajectory informs strategic choices, and what practical, decision-ready outputs our full report delivers. To preserve the value of our proprietary segmentation models and detailed financial schedules, this release follows a “trailer” approach: it reveals rigorous insight and methodologies while intentionally withholding core segment-level figures and forecasts. For complete data and downloadable models, please consult the full report on our website.
Primary Cell Media Market
Why 2026 Is an Inflection Point
The Primary Cell Media market has shown sustained expansion over the past half-decade, propelled by intensifying investment in complex biology, regenerative medicine, and phenotypic screening platforms. Our base-year assessment (2025) places the global market above the billion-dollar mark, and the forecast to 2032 reflects a near doubling by the end of the period on a compound annual growth rate (CAGR) of approximately 9.25% across 2026–2032. These macro dynamics mean that 2026 is not merely another year of growth — it is the year when strategy must transition from “capture share” to “capture value.”
Primary Cell Media Market
For market participants — from reagent manufacturers to service providers and large biopharma procurement teams — the practical question is: where should capital and commercial focus be allocated now to secure differentiated position and margin in a market maturing toward consolidation and advanced use cases?
Primary Cell Media Market
Macro Trajectory and Strategic Consequences
-
Scale and sophistication: The market’s expansion to 2025 and beyond is broad-based. Volume-driven opportunities remain in routine cell culture and research applications, while higher-growth pockets are tied to cell therapy enabling workflows and high-fidelity primary cell assays. The implication for suppliers is clear: defend low-cost, high-reliability SKUs, and simultaneously invest selectively in premium formulations and kit-level solutions that command higher margins.
-
Consolidation dynamics: Industry concentration metrics indicate that top-tier providers collectively command a meaningful share of the market, with the leading triad responsible for a substantial portion of global revenues and the top five firms controlling an even larger share. This concentration raises both competitive pressure and opportunity — incumbents can leverage scale to integrate vertically and offer platform solutions, while nimble specialists can win by deepening differentiation in tissue-specific or chemically defined media.
-
Regulatory and quality constraints: Primary cell media are subject to stringent consistency and documentation expectations for research and early translational work. Our analysis highlights that buyers increasingly demand traceable raw material provenance (including amino acids, vitamins, and plant hydrolysates) and standardized QC data. Suppliers with robust quality systems, transparent raw material supply chains, and validated lot-to-lot consistency will be best positioned for 2026 procurement frameworks.
Competitive Landscape — How the Leaders are Positioning
The market is characterized by a mix of global life-science platforms, specialist media vendors, and emerging niche players. Our report analyzes strategic positioning across product breadth, scale economics, channel reach, regulatory readiness, and innovation pipelines. A few high-level observations:
-
Platform incumbents leverage brand, distribution, and integrated product portfolios to protect core revenue while extending into higher-value kits and support services. Their strengths lie in scale sourcing, global logistics, and trusted QC frameworks.
-
Specialist manufacturers focus on tissue- or application-specific formulations and often compete on the basis of R&D depth, bespoke support, and close collaboration with academic or clinical partners. These companies typically achieve higher ASPs in targeted segments and act as strategic partners to translational programs.
-
Niche entrants and regional players seek to capture share through localized service models, competitive pricing, or rapid-response formulation services tailored to emerging cell types and assay formats.
For executives evaluating competitors, our full analysis profiles each major player across capability matrices: product portfolio scope, manufacturing compliance, distribution networks, and recent M&A or alliance activity. This enables precise benchmarking and informs whether inorganic growth or targeted partnership is the optimal route to accelerate a 2026 agenda.
Supply-Chain Realities and Raw Material Risk
Primary cell media formulations are chemically and biologically complex. They are assembled from basal media (amino acids, vitamins, salts, energy substrates) and are frequently supplemented with growth factors, cytokines, and low‑percent serum or serum replacements for fastidious primary cells. Plant-derived hydrolysates, such as certain wheat hydrolysates, remain a cost-effective supplement to provide amino acids and peptides in some formulations.
Our scenario analysis highlights three supply-chain risk vectors relevant to 2026 decision-making:
-
Raw material variability: Lot-to-lot quality variability for complex supplements can create downstream assay drift. Procurement teams should require supplier transparency on raw-material sourcing and perform targeted lot-bridging studies.
-
Regulatory tightening: As translational use cases rise, documentation and traceability expectations increase. Firms that preemptively align to higher-quality documentation standards will accelerate adoption by clinical developers.
-
Price and availability shocks: Concentrated supply of key biosupplements can cause rapid margin pressure. Diversified sourcing strategies and strategic inventory policies are recommended for manufacturers and large buyers alike.
What the PW Consulting Report Delivers — Operational and Strategic Tools
Our full Primary Cell Media Market report is designed to be immediately operational for C-suite and business unit leaders. Key deliverables include:
-
Proprietary market model: A dynamic financial model projecting global market size from 2020 through 2032, with scenario toggles for adoption rates, pricing pressure, and raw-material cost shocks. (Note: detailed segment outputs and regional splits are available in the paid report.)
-
Commercial playbook: Go-to-market strategies tailored to three archetypes — platform incumbent, specialist innovator, and regional challenger — with tactical recommendations on pricing, bundling, and channel optimization for 2026 implementation.
-
Supplier due-diligence checklist: A ready-made scorecard for procurement teams that weighs quality systems, supply-chain transparency, documentation readiness, and product validation support for translational work.
-
Product innovation roadmap: Prioritized formulation and kit investments based on unmet needs in cell therapy enabling workflows, high-throughput primary cell assays, and serum-free/chemically defined transitions.
-
M&A and partnership heat map: Identification of strategic targets and alliance opportunities by capability cluster, including integration risk flags and expected time-to-value for different transaction archetypes.
How Leaders Should Use This Report in 2026
We recommend three immediate actions for decision-makers preparing for 2026 execution:
-
Prioritize investment by value chain position: If you are a raw-material supplier, invest in traceability and documentation. If you are a media formulator, prioritize kits and application-specific validation data that accelerate adoption by translational teams.
-
Refine procurement terms: Shift from price-only sourcing to total-cost-of-ownership and risk-sharing contracts that account for lot stability and supply reliability. Use the supplier due-diligence checklist included in the report to standardize assessments across stakeholders.
-
Test & scale innovation through partnerships: De-risk product introductions by co-developing with key translational partners and contract research organizations. The report’s partnership heat map guides selection and sequencing.
Methodology and Confidence
Our conclusions draw on a multi-method approach: bottom-up revenue modeling, supplier interviews, product portfolio mapping, and primary conversations with procurement and R&D leaders across biopharma and academic institutions. The study’s base year is 2025, with a forecast window covering 2026–2032. We quantify market concentration and include robustness testing against raw-material and regulatory scenarios to deliver high-confidence guidance for mid-sized and large enterprises planning 2026 investments.
Next Steps — Accessing the Full Intelligence
This briefing intentionally omits the granular segmentation schedules and regional/application numeric breakdowns that are core to tactical deployment. Those proprietary outputs — together with the downloadable model, supplier scorecards, and a slide-ready executive deck — are included in PW Consulting’s full Primary Cell Media Market report.
Organizations that secure the full report will be equipped to:
-
Identify the precise product and regional pockets where premiumization strategies will yield the highest ROI in 2026;
-
Run internal “what-if” scenarios for procurement and R&D investments using the embedded financial model;
-
Engage in informed M&A or alliance discussions backed by independent valuation assumptions and strategic fit analysis.
For executives who need a concise advisory session, PW Consulting offers a tailored briefing that walks through the model, highlights the three highest-impact moves for your organization in 2026, and delivers a customized supplier risk dashboard calibrated to your portfolio.
Final Word
The Primary Cell Media market is maturing from a fragmented R&D supply category into a strategically significant platform for translational biology and cell-based therapeutics. Success in 2026 will hinge on combining robust quality systems and supply-chain resilience with sharply targeted product innovation and partnership strategies. PW Consulting’s Primary Cell Media Market study provides the quantitative foundation and the tactical playbook to execute that transition. For complete data, granular segmentation, and the decision tools described above, please refer to the full report available through our website.
For detailed analysis of this topic, please visit the official page: Primary Cell Media Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Self‑Healing Gel Market to Expand at 9.85% CAGR, Reaching USD 551.15 Million by 2032
By pmarketresearch, 2026-07-07
Self-Healing Gel Market 2026: Strategic Playbook from PW Consulting
Executive summary
PW Consulting’s newest industry brief — the Self Healing Gel Market Report (base year 2025; forecast 2026–2032) — reframes how senior executives should approach product development, commercial strategies, and capital allocation in this rapidly maturing technology domain. Our analysis shows the market has moved from a specialist research and niche-application phase into a scale-up window: total market value rose steadily from 2020 through 2025 and is projected to continue expanding through 2032 at a compound annual growth rate of 9.85% (forecast period). By 2026 the market is positioned for a meaningful step-change as clinical validation, regulatory pathways, and manufacturing throughput converge.
Self Healing Gel Market
Why this report matters for 2026 decisions
-
Timing: 2026 is now the inflection year for commercialization. Companies that sequence regulatory, reimbursement and capacity investments correctly will capture disproportionate share as early-adopter clinical pathways open up.
Self Healing Gel Market -
Capital allocation: Our scenario modeling shows that modest shifts in R&D spend, targeted M&A, or co-development agreements in 2026 materially alter revenue curves across the 2026–2032 forecast horizon — given the market’s near double-digit CAGR and relatively low top-three concentration.
Self Healing Gel Market -
Competitive differentiation: Technological novelty (e.g., peptide-based biomimetic matrices, supramolecular chemistries) is only one axis. Outcome-driven commercialization — integrating supply chain resilience, payer evidence, and point-of-care adoption — separates winners from followers.
Macro snapshot (selected highlights)
-
Historical expansion to 2025: The category recorded sustained growth through 2025 following accelerated translational research and early commercial approvals.
-
Short-term outlook: PW Consulting projects the market to increase further in 2026 as clinical evidence sets and regulatory pathways (notably accelerated pathways in the U.S.) streamline market introduction.
-
Long-term trajectory: Under our base-case, the market grows at a 9.85% CAGR over the forecast period, reflecting broader adoption across biomedical, soft robotics, and specialty industrial applications.
-
Market structure: Concentration is moderate — the three- and five-firm concentration ratios are revealing of a market with several relevant global players but meaningful room for innovators and regional scale-ups.
What the PW Consulting report delivers (practical, actionable content)
-
Proven sizing methodology: Transparent market-sizing with reconciled top-down and bottom-up approaches, sensitivity testing, and scenario maps for conservative, base, and aggressive adoption curves.
-
Regulatory & reimbursement playbooks: Comparative pathway matrices for major jurisdictions, accelerated approval vectors (where available), and a payer-evidence checklist tailored to regenerative wound and implantable device use cases.
-
Commercial go-to-market frameworks: Customer segmentation, procurement workflows, channel economics, and a sales-readiness scorecard to prioritize clinics, trauma centers, and OEM partnerships.
-
Manufacturing and supply resilience analysis: CapEx vs. contract-manufacturing decision tools, raw-material exposure heatmaps, and cost-to-serve models that quantify margin sensitivity under commodity price volatility.
-
Competitive intelligence: Executive profiles, capability benchmarking, patent landscape snapshots, and likely strategic moves for tier-one and emerging companies — enabling validation of partnership targets or acquisition candidates.
-
Investment-grade scenarios: Valuation sensitivities, break-even timelines for greenfield plants, and acquisition arbitrage cases calibrated for 2026 deal dynamics.
-
Leadership playbook: 18–24 month priority plan with KPI milestones (clinical endpoints, regulatory submissions, reimbursement decisions, commercial pilots) for boards and CEOs.
Competitive landscape — what to watch
The market’s competitive map comprises legacy medical device and wound-care companies, specialist hydrogel innovators, and cross-disciplinary academic spinouts. Notable corporate participants include Advanced Medical Solutions Group PLC, Axelgaard Manufacturing, Cardinal Health, Hydromer Inc., Gel4Med Inc., Alliqua Biomedical, Contura International, Smith & Nephew, and 3M. Each plays a distinct role:
-
Established wound-care and device firms bring channel access, regulatory experience, and procurement relationships — valuable for scale deployment.
-
Specialist gel developers and university spinouts offer differentiated chemistries and IP — attractive as acquisition or licensing targets for firms seeking innovation lift.
-
OEM partners and contract manufacturers are critical to de-risking scale-up; their selection impacts margins and time-to-market materially.
PW Consulting’s company dossiers synthesize corporate strategy, clinical evidence base, IP positioning and likely near-term moves (e.g., licensing, co-development, targeted M&A), without divulging sensitive financials. This enables buyers to prioritize targets and design negotiation strategies grounded in technical and commercial reality.
Selected recent developments signaling inflection
-
Clinical validation: A high-profile real-world evidence series on a peptide-based biomimetic hydrogel matrix reported faster healing in complex wounds — a commercial accelerant that supports reimbursement discussions.
-
Regulatory momentum: Earlier regulatory clearances and accelerated pathways for advanced wound care in some markets are shortening commercialization timelines, but heterogeneity across jurisdictions requires tailored regulatory roadmaps.
-
Research breakthroughs: Academic teams have demonstrated high-strength, rapidly self-repairing hydrogels that better mimic skin mechanics — enabling new therapeutic and device-adjacent applications.
-
Product innovations: Polysaccharide-based systems enabling pH-triggered release mechanisms point to next-generation value propositions in infection control and healing modulation.
Market dynamics and risk factors
-
Regulatory and reimbursement complexity: While accelerated pathways exist, consistency is lacking across major markets. PW Consulting quantifies the expected time-to-reimbursement under multiple evidence generation strategies.
-
Raw material volatility: Polymer and biomaterial price swings create near-term margin pressure. We model hedging and supplier diversification strategies to protect gross margins.
-
Fragmented innovation: Moderate market concentration means multiple differentiated technologies will compete; first-mover clinical evidence and payer-facing health economics models will decide sustainable pricing.
-
Manufacturing scale risks: Scaling advanced hydrogel production requires specific capabilities (sterility, coating uniformity, mechanical property consistency). Our report maps out capital, timeline, and operational risks for internal versus outsourced manufacturing pathways.
Strategic imperatives for 2026 (executive checklist)
-
Prioritize clinical endpoints that map to payer value — not just biological novelty. Use early real-world evidence pilots to shorten time-to-coverage discussions.
-
Define a hybrid manufacturing strategy: secure short-term CMO capacity for pilots while investing selectively in modular internal capabilities to protect IP and reduce long-term COGS.
-
Pursue targeted partnerships: collaborate with established wound-care distributors and trauma centers to expedite adoption and gather high-value clinical data.
-
Hedge raw-material exposure: negotiate multi-year supply agreements or material-substitution strategies to maintain margin resilience.
-
Design an acquisition funnel: use PW Consulting’s target-scoring model to prioritize bolt-on innovators that fill technology gaps or accelerate entry into adjacent applications (e.g., soft robotics, coatings).
How to use the report — recommended next steps
-
Board briefing: Use the 12–18 month action plan and KPI dashboard to align board expectations and capex requests for 2026 initiatives.
-
Business development: Leverage the company dossiers and partnership scorecards to run 90-day diligence sprints on priority targets.
-
Regulatory and reimbursement teams: Adopt the report’s comparative approval and payer-evidence matrices to build synchronized submission and evidence-generation timelines.
-
Investors and PE sponsors: Use scenario valuations and sensitivity analyses to inform investment timing, earn-out structures, and exit planning calibrated to the market’s projected growth profile.
Final note — why PW Consulting’s insight matters
Our research combines near-term commercial intelligence with rigorous scenario modeling to translate scientific innovation into board-level decisions. The Self Healing Gel Market is transitioning from laboratory promise to clinical and commercial reality — and 2026 is the critical year to align strategy, capacity and capital. PW Consulting’s report provides the playbook: the evidence hierarchy, the regulatory map, the commercial templates, and the M&A-first checklist needed to convert technology into market leadership.
To access the full data tables, segmentation breakdowns, company profiles and step-by-step implementation templates, please visit the PW Consulting report page for the Self Healing Gel Market (report base year 2025, forecast 2026–2032). The full report contains the segment-level intelligence intentionally omitted here to preserve strategic confidentiality in this executive press release.
For detailed analysis of this topic, please visit the official page: Self Healing Gel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 4.52% CAGR for the 4‑Bromoanisole Market Through 2032
By pmarketresearch, 2026-07-07
4-Bromoanisole Market 2026 Preview: Strategic Imperatives for Chemical and Pharma Leaders
PW Consulting’s latest market intelligence on 4-Bromoanisole positions this relatively compact specialty chemical market as a strategic lever for companies planning decisions in 2026 and beyond. Based on a 2025 base year and a forecast horizon through 2032, our analysis synthesizes growth dynamics, supplier economics, regulatory vectors and tactical playbooks. The market, which we valued at USD 56.7 Million in 2025 and project to grow at a steady mid-single-digit CAGR (4.52%) over the 2026–2032 forecast window, is small enough to be nimble and large enough to generate meaningful margins for players that execute with precision.
4 Bromoanisole Market
Why 4-Bromoanisole Matters to Decision-Makers in 2026
- Strategic input for fine chemicals and pharma: 4-Bromoanisole is a critical aryl halide used as a building block for active pharmaceutical ingredients (APIs), intermediates, and select advanced materials. Supply disruptions or cost moves can ripple across high-value value chains.
- Margin and risk management: Given the concentrated supply of key feedstocks and sensitivity to halogen pricing, effective procurement and hedging decisions materially affect product-level margins.
- Regulatory and market access: New and evolving chemical regulatory requirements change time-to-market for product launches and create compliance-driven premiums for manufacturers able to supply documented, high-purity and GMP-compliant material.
Macro Trajectory — What the Numbers Tell Us
Our time-series view shows a consistent expansion from earlier historical years into 2025, with 2026 expected to continue that upward trajectory. With a compounded annual growth rate of 4.52% across the forecast period, the market is characterized by steady, demand-led expansion rather than explosive volume growth. That profile favors companies that can secure higher-value streams (pharma-grade supplies, custom synthesis) and optimize cost-to-serve rather than purely chasing volume-based scale.
4 Bromoanisole Market
Supply-Chain and Cost Dynamics
Two structural cost drivers are front-and-center for 2026 planning. First, upstream halogen feedstock markets experienced notable tightening in late 2025, pushing bromine-related costs materially higher and elevating the cost base for brominated aromatics. Second, anisole and related phenolic feedstock availability tightened across key producing regions, creating price unpredictability and more frequent spot-market volatility.
4 Bromoanisole Market
For buyers and producers, the immediate implication is clear: fixed-price sourcing is increasingly risky. Tactical responses that we model in the report include staggered multi-year procurement contracts with price-collar mechanisms, strategic partnership agreements with bromine and anisole producers, and options-based hedging for critical feedstocks. We also quantify the margin sensitivity of different product specifications to upstream cost swings, enabling CFOs to decide where to preserve gross margins versus where to compete on price.
Regulatory Landscape — Risk, Compliance and Opportunity
Regulatory regimes are tightening in major markets. Among the most consequential developments is updated registration and documentation expectations under European chemical regulation, which now requires expanded safety dossiers and restrictions for substances with certain hazard profiles. For suppliers, this elevates the cost of market access but creates a value premium for reputable vendors offering robust technical and regulatory support (SDS completeness, REACH dossiers, and Annex-based compliance). For purchasers in regulated industries—particularly pharmaceutical manufacturers—suppliers with demonstrated regulatory readiness can shorten project timelines and reduce technical risk.
Competitive Landscape — Who’s Playing and How
The market exhibits moderate concentration: the top-three suppliers collectively represent a meaningful share of global supply while the top-five approach majoritarian scale, a structure that simultaneously enables specialized entrants to thrive. Below, we summarize the strategic positioning of the core commercial providers covered in our analysis:
- Sigma-Aldrich (Merck KGaA) — Positioned as a premium lab-and-pharma supplier with small-pack offerings and lab-grade material up to high-purity specifications. Their global distribution footprint and brand trust make them a first-choice for R&D and early-stage pharma programs.
- Alfa Aesar (Thermo Fisher Scientific) — Focuses on high-purity industrial and research markets with broad catalogue availability, serving organic synthesis and fine-chemical applications. Their catalogue breadth supports rapid prototyping and scale-up workflows.
- TCI America (Tokyo Chemical Industry) — Offers high-purity grades targeted at pharmaceutical intermediates and materials-science applications, with a reputation for consistent analytical support and reliable lot-to-lot quality.
- Apollo Scientific — Acts as a bridge between small-scale research supply and larger industrial needs, distributing across a wide size range and catering to aryl halide chemistry in both academic and industrial settings.
- Combi-Blocks — Differentiates through custom kg-scale manufacturing for drug-discovery building block libraries; attractive for customers needing bespoke quantities with accelerated lead times.
- Biosynth — Focused on GMP-grade production and full analytical support for pharmaceutical R&D—an important partner for companies that must meet regulatory quality standards from the outset of development.
- Oakwood Chemical — Specializes in custom synthesis and offers near-pharma levels of purity in mid-size packages, enabling nimble responses to bespoke customer specifications.
Our competitive analysis goes beyond catalog excerpts to evaluate route-to-market strategies, manufacturing footprints, regulatory competencies, and service-led differentiators such as custom synthesis, GMP certification and analytical support. The result is an actionable supplier scorecard that buyers can use to rationalize vendor panels and for suppliers to benchmark their service gaps.
Report Deliverables — Practical Tools for 2026
PW Consulting’s full report is built to be operationally useful. Highlights include:
- Supply risk heatmaps and supplier concentration indices by use-case (R&D, pharmaceutical, materials), enabling procurement to prioritize vendor continuity planning.
- Cost-sensitivity models that translate feedstock price moves into product-level margin impacts across purity tiers and package sizes.
- A regulatory readiness checklist that maps documentary and testing requirements against timelines for market access in major jurisdictions.
- Go-to-market playbooks for specialty chemical producers—detailing premiumization strategies, packaging optimization, and service bundles that support higher ASPs.
- M&A screening templates and financial multiples guidance to identify bolt-on acquisition targets (custom synthesis houses, small-scale producers, regional distributors) that accelerate market access or backward integration.
- Scenario-based forecasts and stress tests calibrated to a range of feedstock volatility, regulatory tightening, and demand shocks—designed for board-level decision-making in 2026.
Deliberately, the public summary you are reading omits granular segmentation tables and region/application share breakdowns. Those data, including detailed regional demand profiles and application-level revenue splits, are central to tactical planning and are available to subscribers and purchasers of the full report.
Strategic Implications and Recommended Actions for 2026
- Procurement: Lock in staged supply agreements with price-collars, diversify feedstock sources, and consider co-investment agreements with bromine or anisole suppliers to secure preferential allocations.
- Product Strategy: Prioritize development and certification of higher-value, regulatory-ready grades (e.g., GMP or pharma-intermediate specifications) where margin capture is defensible.
- Operations & Capex: Evaluate small-scale capacity additions and toll-manufacturing partnerships as lower-risk routes to capture incremental demand without committing to large greenfield investments.
- Commercial & Sales: Implement value-based pricing for customers that require regulatory documentation and analytical support; utilize supplier scorecards to rationalize distribution channels and reduce SKUs with low contribution margins.
- M&A & Partnerships: Target acquisition or partnership with custom synthesis specialists to secure bespoke capabilities and accelerate market share gains in pharmaceutical intermediates.
- Regulatory Readiness: Invest in dossier development, extended safety data, and post-market surveillance systems to shorten approval cycles and command premiums in regulated markets.
Closing Perspective — Why This Report Is Decision-Grade for 2026
Two features make our 4-Bromoanisole market study uniquely actionable for 2026 planning: first, the synthesis of macro and micro drivers into scenario-focused financial impacts; second, the practical tools (scorecards, contracting playbooks, regulatory checklists) that move teams from insight to execution. With a market size in the mid-tens of millions in USD and steady growth to a substantially higher level by 2032 under our base-case forecast, organizations that align procurement, regulatory and product strategies now will capture disproportionate upside while insulating margins from commodity swings.
For procurement directors, business-unit leaders and corporate strategy teams preparing budgets and M&A pipelines in 2026, the full PW Consulting report provides the segment-level data, regional demand maps, and supplier-level financials needed to make high-confidence decisions. To access the comprehensive datasets, supplier scorecards, and scenario models described above, please consult the full report and subscription resources on our website.
For detailed analysis of this topic, please visit the official page: 4 Bromoanisole Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Liquid Copper Fungicide Market Poised for 4.82% CAGR, New Insights Reveal
By pmarketresearch, 2026-07-07
Liquid Copper Fungicide Market: Strategic Imperatives for 2026 — PW Consulting Insight Brief
As PW Consulting publishes its comprehensive market study on Liquid Copper Fungicides (base year 2025, historical 2020–2025, forecast 2026–2032), this briefing highlights the strategic implications our analysis delivers for executive decision-making in 2026. The report synthesizes macro drivers, regulatory shocks, input-cost dynamics, and competitor positioning into actionable pathways for manufacturers, distributors, input financiers, and strategic investors. Below we preview the high-level findings and the concrete choices they imply—while preserving the detailed segment-level intelligence that is available exclusively in the full report.
Liquid Copper Fungicide Market
Market at a Glance: Growth trajectory and market scale
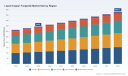
Our market model pegs the global Liquid Copper Fungicide market at approximately USD 346 million in 2025, growing at a compound annual growth rate (CAGR) of 4.82% through 2032. The market expands to an estimated USD 362 million in 2026 and follows a steady upward trajectory to roughly USD 481 million by 2032. This steady mid-single-digit growth masks substantive heterogeneity in risk, margin, and adoption across formulations, geographies, and crop applications—details that are unpacked in the full study.
Liquid Copper Fungicide Market
Why this matters for 2026 strategy
- Timing of investment and product launches. With predictable top-line growth but accelerating regulatory and raw-material volatility, 2026 is a year for targeted, not broad, capital deployment. Companies that time formulation upgrades and commercial roll-outs to regulatory cycles and planting calendars will capture disproportional share.
- Risk-managed supply positioning. Input-cost pressure—amplified by geopolitical trade measures and commodity price spikes—means that firms without proactive hedging or secure long-term feedstock arrangements will face margin compression even with modest top-line growth.
- Regulatory arbitrage and reputation management. The policy environment is increasingly determinative of market access and cost-to-serve. 2026 will reward companies that can demonstrate lower-environmental-impact formulations and robust stewardship programs.
Key market dynamics shaping decisions
- Regulatory tightening and substitution risk. Since 2024–2025 regulatory actions in major markets have raised thresholds for copper use and added worker and environmental safeguards. Some authorities are now treating copper compounds as candidates for substitution due to soil persistence and aquatic toxicity. These trends are crystallizing into dose ceilings, restricted use patterns, and heightened compliance costs—factors that should be incorporated into product life-cycle economics and R&D prioritization in 2026.
- Input-cost volatility and trade policy. Copper feedstock pricing and trade barriers are elevating production risk. Recent episodes demonstrate that tariff proposals and refined-copper import constraints can materially increase landed costs for fungicide manufacturers. For 2026 planning, companies must model scenarios that include sustained elevated raw-material prices and potential supply-chain disruption.
- Innovation as a defensive and offensive lever. Innovation centered on reduced-copper loadings, improved delivery technologies, and synergistic integration with biologicals is shifting the competitive frontier. New product introductions and reformulations that lower environmental load while preserving efficacy create double value—regulatory resilience and market differentiation.
- Channel shifts and farm-level adoption patterns. Adoption among high-value specialty crops continues to drive premiumization, while broad-acre commodities prioritize cost and ease-of-use. Distributors and manufacturers that align portfolio and channel incentives to these distinct buyer logics will outperform.
Competitive landscape: concentration, capability clusters, and tactical moves
The Liquid Copper Fungicide market exhibits moderate concentration. The top three firms account for a material but non-dominant share of revenue, while the top five control just over half of the market—indicating a landscape where national and regional players coexist with global agrichemical majors. This structure creates windows for both scale-driven plays and nimble, local incumbents to exploit differentiated offerings.
Liquid Copper Fungicide Market
- Global agrichemical leaders (scale and channel). Large diversified crop protection companies maintain an advantage in global go-to-market reach, regulatory affairs capacity, and multi-crop bundling. Their ability to combine copper chemistries with systemic products, service models, and farmer programs supports broad uptake in major crop systems.
- Specialists and regional champions (agility and regulatory fit). Firms focused on copper chemistries and regionally tailored formulations are faster at adapting labels, stewardship programs, and distribution partnerships—an asset in markets facing tight, fast-evolving regulatory constraints.
- Recent strategic moves to watch. Mergers, distribution acquisitions, and product launches over the 2024–2025 period demonstrate how participants are responding: expanding regional footprints through distribution acquisitions, introducing lower-impact copper formulations, and seeking regulatory endorsements for revised use patterns. These tactical moves signal where future consolidation and capability aggregation are likely.
What our competitor analysis surfaces
- Competitive positioning is multidimensional: product form (liquid vs. suspension vs. wettable), technical know-how (compound stability and tank-mix compatibility), regulatory dossier depth, and route-to-market strength.
- Global players are investing in stewardship and reformulation; specialist suppliers emphasize conversion paths from granular or powder concentrates into ready-to-apply liquid systems favored by certain crop segments.
- Regional firms leverage local registration acumen and service models for smallholder and high-value markets, retaining resilience even as global players scale back copper exposure in some geographies.
What the full PW Consulting report delivers (practical scope)
- Transparent methodology: historical dataset (2020–2025), detailed forecasting engine (2026–2032) and sensitivity scenarios that isolate regulatory, price, and adoption shocks.
- Segmental intelligence: granular splits by region, formulation type, and application—accompanied by demand drivers, margin profiles, and growth pockets. (Note: segment-level figures are reserved for the full report.)
- Regulatory & stewardship playbook: jurisdiction-level risk scores, compliance cost curves, and recommended label strategies to preserve market access under tightening use limits.
- Supply-chain resilience map: feedstock exposure analysis, tariff and logistics stress tests, and sourcing strategies to mitigate input-cost spikes.
- Commercial playbooks: targeted GTM strategies for channels and crop systems, pricing and promotion scenarios, and farmer adoption roadmaps supported by field-efficacy levers.
- M&A and partnership screening: a proprietary scorecard to identify bolt-on targets and distribution acquisition opportunities that improve regulatory footprint or feedstock security.
Concrete 2026 actions we recommend
- Prioritize reformulation projects that reduce cumulative Cu load. Investing selectively in lower-load or microencapsulated liquid formulations will yield regulatory resilience and premium access in constrained jurisdictions.
- Secure upstream exposure. Negotiate multi-year agreements with copper refiners or diversify to alternative copper chemistries to blunt raw-material swings and tariff-driven cost spikes.
- Accelerate stewardship & compliance investments. Allocate resources to worker-protection measures, environmental monitoring, and label alignment to shorten registration cycles and reduce rework risk.
- Segment GTM by crop economics. Deploy premium, higher-margin formulations in specialty crops while optimizing unit-costs for broad-acre commodity segments through streamlined packaging and logistics.
- Use M&A tactically. Pursue small-to-midscale acquisitions that close distribution gaps in priority markets or add formulation competencies without taking on disproportionate regulatory legacy risk.
Scenario planning essentials for CFOs and strategy teams
Our scenario toolkit models three credible 2026+ environments: (1) Regulatory-Intensified — accelerated phase-out signals and tighter use ceilings; (2) Input-Pressure — persistent elevated copper feedstock prices due to tariffs and supply constraints; (3) Innovation-Accelerated — rapid adoption of reduced-copper and biological-integrated products. Each scenario shifts investment priorities and required working-capital cushions. We recommend stress-testing P&L under each scenario and mapping capital deployment to where optionality and near-term payback overlap.
Closing: strategic value proposition of the report
For 2026, liquid copper fungicide market participants face a paradox: stable aggregate growth alongside intensifying pockets of regulatory and supply risk. Our report equips executives with the quantitative forecasts, regulatory risk scoring, and tactical playbooks needed to convert this complexity into competitive advantage. It is designed not as a static data dump, but as an operational guide that links market intelligence to investment decisions, launch calendars, and M&A prioritization.
To access the full dataset, granular segment breakdowns, proprietary scenario models, and the operational playbooks referenced above, please visit the PW Consulting report page for Liquid Copper Fungicides. The full study includes downloadable spreadsheets, scorecards for acquisition screening, and a customized briefing option for executive teams preparing 2026 operating plans.
For detailed analysis of this topic, please visit the official page: Liquid Copper Fungicide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Automotive Automatic Spray Guns Market Reaches USD 1,025.6 Million in 2025, Set to Expand at a 5.85% CAGR Through 2026–2032
By pmarketresearch, 2026-07-07
Automotive Automatic Spray Guns Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting’s latest industry briefing previews our comprehensive Automotive Automatic Spray Guns Market report (base year 2025, forecast 2026–2032). As OEMs, tier suppliers, coatings formulators, and private capital plan 2026 investments, this preview highlights the practical intelligence and decision frameworks we provide — without disclosing the proprietary, granular segment data reserved for report subscribers.
Automotive Automatic Spray Guns Market
Market at a Glance: Why the Numbers Matter for 2026
-
Market scale and trajectory: The automatic spray guns market reached USD 1,025.6 Million in 2025 and is projected to grow to approximately USD 1,071.6 Million in 2026, with a compound annual growth rate (CAGR) of 5.85% across the 2026–2032 forecast window.
Automotive Automatic Spray Guns Market -
Competitive structure: Market concentration is moderate — our analysis quantifies the three- and five-firm concentration ratios (CR3 ≈ 38.5%, CR5 ≈ 52.7%) — signaling a marketplace where global leaders and specialized challengers coexist and where strategic partnerships or consolidation can quickly change competitive dynamics.
Automotive Automatic Spray Guns Market -
Strategic timing: Multiple regulatory deadlines and technology adoption cycles converge in 2026–2028, making 2026 a pivotal planning year for capex, supplier selection, and product roadmap alignment.
Why 2026 Is a Pivotal Year for Decision-Makers
-
Regulatory inflection points: North American and European regulatory frameworks (including recent EPA and regional VOC and coating rules) are tightening compliance expectations for VOC emissions and transfer-efficiency standards. These regulations accelerate adoption of HVLP or equivalent high-efficiency automatic technologies and create discrete windows for capital deployment and retrofits.
-
Technology and automation: The push toward higher transfer efficiency, robotics and inline electrostatic solutions to support shorter cycle times and lower waste is reshaping supplier requirements. Integrating spray-gun systems with robotic arms and paint applicator lines is now a standard procurement requirement for many OEM paint shops.
-
Input-cost volatility: Rising costs for stainless steel and specialty nozzle alloys are compressing margins for premium offerings and influencing supplier sourcing strategies — an increasingly important consideration for procurement teams and manufacturers planning product upgrades in 2026.
What the PW Consulting Report Delivers — Practical, Transaction-Ready Intelligence
Our full report combines market sizing, scenario modeling and actionable playbooks tailored to executives who must make capital and sourcing decisions in 2026. Highlights include:
-
Robust forecasting: Top-down and bottom-up modeling across the 2026–2032 horizon, including sensitivity scenarios that stress-test regulatory compliance timelines and raw-material price shocks.
-
Supplier scorecards: Vendor performance matrices that rate firms on transfer efficiency, reliability, total cost of ownership (TCO), service footprint, and robotic integration readiness.
-
Technology benchmarking: Comparative assessments of HVLP, airless and electrostatic automatic systems — focusing on cycle-time impact, paint savings, maintenance intervals and retrofit complexity.
-
Procurement playbook: Step-by-step guidance for supplier selection, negotiation levers, spare-parts strategies and service-level agreements to protect uptime during fleet upgrades.
-
Capex prioritization framework: ROI calculators, payback scenarios and project prioritization matrices tuned to typical OEM and refinishing shop profiles.
-
M&A and partnership diagnostics: Identification of strategic inorganic moves, partnership archetypes, and integration risks to inform both acquirers and target management teams.
-
Regulatory compliance map: Practical compliance timelines that tie regulation milestones to investment triggers and replacement cycles.
Note: The full report includes granular regional and application-level forecasts and segment models that are intentionally excluded from this preview to preserve the confidential intelligence that informs buyers’ strategies.
Core Market Dynamics and Strategic Implications
-
Shift to efficiency-first specifications: OEM procurement teams are increasingly mandating high-transfer-efficiency systems to reduce solvent consumption and overspray. This drives preference for HVLP and electrostatic systems in new plant projects and retrofits.
-
Robotics as a procurement filter: Systems that integrate seamlessly with robotic applicators — both in hardware and digital control — command a premium in RFQs. Suppliers lacking robust robotic interfaces face longer sales cycles or must partner with integrators.
-
Aftermarket/resale potential: Refinishing and collision repair present stable demand streams, but they have different cost sensitivities and service-model needs compared to OEM lines. Manufacturers that offer configurable solutions and localized service networks can expand margins here.
-
Supply-chain risk management: Rising alloy costs and spot-price volatility for nozzle materials necessitate hedged procurement strategies, local qualification of alternate suppliers, and design-for-cost adjustments without degrading performance.
Competitive Landscape — Who Moves the Needle
The report provides a pragmatic assessment of incumbent vendors and regional challengers, with a focus on strategic positioning rather than raw market share. Representative firms we analyze include:
-
Graco Inc. (Minneapolis, Minnesota, USA — https://www.graco.com): Strong in high-transfer-efficiency products and robotic integration; well-positioned for large-scale OEM lines where uptime and automation are critical.
-
SATA GmbH & Co. KG (Kornwestheim, Germany — https://www.sata.com): Known for precision atomization and ergonomics; a compelling option for premium paint shops and OEM integrations emphasizing finish quality.
-
Anest Iwata Corporation (Yokohama, Japan — https://www.anestiwata.com): Offers advanced atomization technologies and a broad catalog that appeals to both OEMs and refinishing networks.
-
Nordson Corporation (Westlake, Ohio, USA — https://www.nordson.com): Deep expertise in electrostatic and powder systems, favored where high-speed, high-uniformity coating is required.
-
EXEL Industries / Sames (Épernay, France — https://www.exel-industries.com): Strong assembly-line offerings with diverse application modes, including airspray and electrostatic options.
-
Carlisle Fluid Technologies (DeVilbiss, Binks — Scottsdale, Arizona, USA — https://www.carlisleft.com): Legacy brands trusted for transfer efficiency and reliability across OEM and refinishing segments.
-
Chinese OEMs such as Ningbo Lis Industrial and Zhejiang Rongpeng ( https://www.lispraygun.com, https://www.rongpeng.com): Competitive on price and customization; increasing presence where localized support and cost are decisive.
Recent market moves underscore evolving competitive dynamics: a 2026 partnership positioning Fuji Spray Auto as a preferred supplier for technical training programs; product previews and catalog updates from established European and Japanese vendors signaling upgrades to their premium lines; and continued emphasis on electrostatic and automation-ready systems. These developments validate our thesis that product differentiation, service ecosystems, and integration capabilities will decide winners in the near term.
Actionable Recommendations for 2026 Decision-Makers
-
For OEM paint-shop leaders: Prioritize pilot projects that validate integration of electrostatic/HVLP systems with your robotic controls before committing plant-wide capex. Use staged rollouts to align training, spare parts, and maintenance contracts.
-
For spray-gun manufacturers: Accelerate alloy-sourcing diversification, and invest in digital interfaces and API support for robot control systems. A service-led model (spare parts + Uptime SLAs) increases customer stickiness.
-
For procurement teams: Leverage our supplier scorecards to negotiate performance-linked contracts, including uptime guarantees and material-consumption KPIs rather than unit price alone.
-
For investors and M&A teams: Target acquisition candidates that fill critical gaps — robotic integration, regional service networks, or proprietary electrostatic technologies — to create rapid scale and margin improvement.
-
For aftermarket service providers: Offer bundled retrofit packages that include training, calibration, and consumables contracts to capture recurring revenue from refinishing shops adapting to stricter VOC rules.
Methodology and Data Integrity
Our methodology synthesizes primary interviews with OEM procurement and paint-shop managers, vendor financials and product catalogs, regulatory filings, trade shipment data and proprietary price indices. The base-year reference is 2025, and forecasts cover 2026–2032. Scenario modeling includes policy-driven adoption curves and raw-material price-shock sensitivities to provide a robust decision-making framework for 2026 planning.
Next Steps — Accessing the Full Intelligence Package
This preview is designed to show the strategic value of the full PW Consulting report for teams preparing 2026 budgets and capital plans. The complete report contains the granular, executable datasets — regional and application-level forecasts, product-level TCO models, and downloadable supplier scorecards — that procurement, engineering and M&A teams rely on to shorten decision cycles and reduce investment risk.
For access to the full dataset, proprietary segment models and a tailored briefing for your leadership team, please visit our report page or contact your PW Consulting account representative. Our team can arrange a 60-minute executive briefing that walks through the decision triggers relevant to your specific business, using the full forecast and supplier analytics in the report.
PW Consulting provides the market intelligence leaders need to convert 2026 uncertainty into strategic advantage — equipping you with the clarity to invest, partner and compete where it matters most.
For detailed analysis of this topic, please visit the official page: Automotive Automatic Spray Guns Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aerial Inspections Market to Expand at 13.5% CAGR, Rising from USD 14,500M in 2025 to USD 35,183.5M by 2032 — UAV & Drone Services Lead with USD 9,383.6M
By pmarketresearch, 2026-07-07
Aerial Inspections Service Market: Strategic Outlook for 2026 Decisions
PW Consulting’s latest market research—built on a 2025 base year and a 2026–2032 forecast horizon—provides decision-grade intelligence for executives who must act in 2026. The Global Aerial Inspections Service Market has more than doubled in five years, rising from approximately USD 7.45 billion in 2020 to USD 14.5 billion in 2025, and is projected to continue at a robust compound annual growth rate (CAGR) of 13.5% through 2032, reaching roughly USD 35.2 billion by the end of the forecast period. This growth trajectory is reshaping capital allocation, procurement strategies, and technology roadmaps across energy, utilities, infrastructure, and industrial verticals.
Aerial Inspections Service Market
Why this report matters for 2026
- Actionable timing: 2026 is the inflection year for several regulatory and operational changes—FAA initiatives on BVLOS, new enforcement pathways, and accelerated platform capability releases—that will materially affect implementation feasibility and unit economics.
- Investment prioritization: With a predictable macro growth rate, boards and strategy teams must distinguish between platform play, service scale, and analytics-first propositions; the report provides prioritization frameworks tuned for 2026 budgeting cycles.
- Procurement clarity: Buyers face a fragmented supplier landscape. Our work decodes vendor capabilities into procurement-ready criteria so buyers can reduce time-to-deployment while managing risk.
Market trajectory and macro drivers
The market’s acceleration is driven by a confluence of forces: sensor miniaturization and multispectral maturity, cloud-native data management, AI analytics for anomaly detection, and cost-justifying returns on safety and operational uptime. The report quantifies the historical run-rate (2020–2025) and projects forward under multiple regulatory and technology adoption scenarios for 2026–2032. At the aggregate level, stakeholders should plan against a central case CAGR of 13.5% while stress-testing portfolios against faster automated BVLOS adoption and slower regulatory approvals.
Aerial Inspections Service Market
Operational economics continue to favor aerial approaches: industry benchmarking indicates drone-based industrial inspections can reduce operating costs by 30–70% and compress inspection time by 75–85% relative to traditional rope-access or scaffold-based methods. Those savings, combined with improved inspection cadence and data repeatability, are the primary levers feeding ROI models in our financial templates.
Aerial Inspections Service Market
Competitive landscape — what to watch in 2026
The market remains lightly concentrated (CR3 ≈ 22.5%, CR5 ≈ 31.4%), indicating a vibrant ecosystem where differentiated capability—software platforms, specialized vertical expertise, and integrated data services—matters more than scale alone. Key provider archetypes and representative players covered in the report include:
- Platform-centric leaders: Companies offering end-to-end data platforms and analytics (e.g., DroneDeploy) are pushing enterprise standardization through software features, strategic partnerships, and faster capture-to-insight times.
- Vertical specialists: Firms focused on wind, solar, or LNG (e.g., SkySpecs for wind blade autonomy; Raptor Maps for solar analytics; Cyberhawk for energy-sector operations) continue to capture premium pricing through domain-specific IP and regulatory know-how.
- Global operators: Providers with geographically distributed service delivery and local regulatory footprints (e.g., Terra Drone) are converting multinational maintenance contracts into multi-year recurring revenue.
- Integrated service firms: Surveying and LiDAR specialists (e.g., SAM) and enterprise drone integrators (e.g., Measure) are combining hardware, geospatial engineering, and data pipelines to serve infrastructure and utilities customers.
Recent visible moves emphasize the market’s dual track: platform enhancement and enterprise partnerships. Notable developments tracked in the report include a multi-year expansion of DroneDeploy’s enterprise footprint with large construction clients and sequential software releases that significantly improve capture performance and BIM integration; Cyberhawk’s contract extensions in energy markets; and new offshore-focused divisions launched to address subsea and maritime inspection needs. These transactions and product cycles signal that 2026 procurement conversations will center not only on flight capability but on enterprise-scale data flows and long-term SLAs.
What the report contains — practical, implementable content
Beyond headline sizing and competitive maps, the report is organized to be operational from day one. Highlights include:
- Deployment playbooks: step-by-step templates for internal pilots, scale-up, and integration with existing maintenance management systems (CMMS/EAM).
- Procurement and vendor-selection frameworks: weighted criteria matrices covering safety compliance, data fidelity, analytics maturity, and commercial terms.
- Unit-economics models: modular TCO templates that let users compare CapEx vs. OpEx options, insourcing vs. managed services, and sensor-suite trade-offs.
- Regulatory risk matrices: scenario planning for FAA rule changes (e.g., BVLOS approval pathways, DETER enforcement processes) and recommended mitigations by jurisdiction.
- Technology roadmaps: timelines for key capability adoptions—autonomy, AI anomaly detection, multisensor fusion, and satellite-data integration—and how each impacts inspection cadence and accuracy.
- Case studies and contract clauses: anonymized client engagements that surface structure, pricing dynamics, and SLA language that procurement teams can adapt immediately.
We intentionally structured deliverables for 90-day, 12-month, and three-year implementation windows so C-suite owners and program managers can align tactical steps with strategic outcomes.
Strategic implications and recommended actions for 2026
- For asset owners (energy, utilities, infrastructure): Move from single-point pilots to portfolio-level pilots that prioritize asset classes with the fastest payback and regulatory permissibility. Embed analytics SLAs in contracts to ensure actionable outputs, not merely imagery.
- For integrators and vendors: Differentiate through analytics IP and domain expertise. Pursue enterprise partnerships that lock in standardized reality-capture workflows—invest in platform API maturity and BIM/CMMS connectors.
- For investors and private equity: Seek consolidation plays where software and data assets can be stacked on service operations to drive recurring revenue and margin expansion. Fragmentation indicates attractive roll-up opportunities, but due diligence must surface regulatory compliance capabilities.
- For regulators and policy teams: Prioritize flexible proof-of-concept corridors and clearer BVLOS certification paths to maintain safety without stifling commercial adoption. The FAA’s DETER program and proposed BVLOS rules will be critical to monitor and engage with in 2026.
Risks and downside scenarios
No growth thesis is unconditionally secure. Our downside scenarios focus on three categories:
- Regulatory headwinds: Delays or restrictive BVLOS policies would slow the most capital-efficient use cases and keep inspection costs higher for longer.
- Operational and labor constraints: Specialized inspection labor and certified pilots remain a bottleneck; typical drone roof and building inspection pricing ranges in the market reflect this scarcity. Enforcement actions under new regulator programs can temporarily disrupt provider capacity.
- Data governance and cyber risk: As inspection platforms become operationally critical, vendors and buyers must harden data chains and ownership contracts to prevent downstream liability.
How to use this report in boardroom decisions
- Use our scenario-based financial models to stress-test CAPEX approvals and OPEX conversions scheduled in 2026 budgets.
- Adopt the vendor-selection scorecard for RFPs issued in 2026 to accelerate procurement cycles and reduce sourcing risk.
- Leverage our regulatory matrix to sequence pilots where approvals are most likely in 2026, de-risking capital commitments for scale-up phases.
Conclusion — the strategic window for 2026
2026 represents a decisive year: technology capability and regulatory evolution will either synchronize to unlock widespread BVLOS and automated inspections or produce a more gradual migration where fleet economics take longer to materialize. PW Consulting’s Aerial Inspections Service Market research synthesizes the quantitative trajectory—from USD 14.5 billion in 2025 to a projected USD 35.2 billion by 2032 at a 13.5% CAGR—with the qualitative playbooks organizations need to convert market potential into operational value.
For executives planning capital deployment, vendor selection, or M&A activity in 2026, the report functions as both a strategic compass and a tactical toolkit. For full subsegment tables, regional scenarios, vendor scorecards, and downloadable financial models that underpin our recommendations, please visit the full report landing page to access the complete dataset and supplementary materials.
For detailed analysis of this topic, please visit the official page: Aerial Inspections Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Maritime Missile Launch System Market Poised to Reach USD 23,224.47 Million by 2032, Expanding at a 7.12% CAGR (2026–2032 Forecast)
By pmarketresearch, 2026-07-07
Maritime Missile Launch System Market: Strategic Imperatives for 2026 — PW Consulting Insights
PW Consulting today publishes an executive briefing derived from our comprehensive Maritime Missile Launch System Market report (base year 2025, historical analysis 2020–2025, forecast period 2026–2032). The global market reached USD 14,350 Million in 2025 and, under our central-case scenario, is forecast to expand at a compound annual growth rate (CAGR) of 7.12% through 2032, reaching roughly USD 23,224 Million. This briefing is designed to translate those macro dynamics into concrete decisions for leaders preparing procurement, product and M&A strategies in 2026. In keeping with our “trailer” approach, we surface analytical frameworks, strategic implications and vendor-level context while withholding detailed segment-level tables to preserve the consultative value of the full report.
Maritime Missile Launch System Market
Why 2026 Is an Inflection Point
Several concurrent forces are converging to make 2026 decisive for maritime missile launch systems (MMLS). Geopolitical pressure in the Indo‑Pacific and heightened modernization cycles among NATO and partner navies are increasing demand velocity for vertical and multi-mission launch architectures. Strategic partnerships—most notably interoperability initiatives underpinned by the AUKUS framework—are reshaping specifications and procurement timelines. At the same time, supply chain stress and export-control regimes are elevating program risk, which amplifies the value of robust scenario planning when committing capital or signing long-term supply contracts.
Maritime Missile Launch System Market
Taken together, these drivers mean that market growth is not uniform: it is driven by large-scale platform upgrades, new-build programs, and an accelerating aftermarket for modernization and services. The implication for 2026 decision-makers is clear: timing, procurement structure and partner selection matter as much as product capability.
Maritime Missile Launch System Market
What the PW Consulting Report Delivers
- Proven market-sizing and forecasting methodology calibrated to 2020–2025 historicals and stress‑tested across demand, cost and regulatory scenarios for 2026–2032.
- Scenario-planning playbooks (three core market trajectories) that translate macro uncertainties into procurement- and balance-sheet-ready actions.
- Vendor scorecards and a competitive-matrix that evaluate capability, program execution, integration risk and service potential.
- Supply-chain heatmaps and mitigation templates including raw-material exposures, alternate sourcing pathways and inventory hedging tactics.
- Regulatory and export-control diagnostics with pragmatic compliance roadmaps tailored to ITAR and allied export regimes.
- Commercial strategies: partner selection frameworks, JV structures for local-content compliance, aftermarket service roadmaps and M&A playbooks for mid-tier consolidation.
Competitive Landscape: Established Leaders and Tactical Specialists
The MMLS market is concentrated, with the top three players controlling a substantial majority of market share (CR3 ~62.5%) and the top five accounting for nearly four-fifths of the market (CR5 ~78.9%). This structure favors incumbents capable of delivering platform-integrated systems and multi-year sustainment, while creating targeted openings for specialized firms that can offer disruptive capabilities or cost-effective upgrade packages.
- BAE Systems (United Kingdom) — A long-standing systems integrator with deep naval-shipyard relationships. The company continues to leverage its Mk 41 VLS heritage through upgrade programs and platform integrations for allied navies; recent contract awards for Mk 41 upgrades underscore its role in sustainment and refresh cycles.
- Lockheed Martin (United States) — Dominant in combat-system integration and a primary Mk 41 supplier; ongoing deliveries to major destroyer programs demonstrate the company’s ability to lock in long-term platform-level revenues and sustainment flows.
- Raytheon Technologies (RTX) (United States) — Focused on integrating advanced weapons and launch systems, with product strategies emphasizing modularity and sensor-shooter integration for distributed lethality architectures.
- MBDA (France/UK/Italy) — European powerhouse for integrated vertical launch solutions, advancing upgrade paths and modular interfaces compatible with a range of missile families; active in regional exhibitions and upgrade showcases.
- Naval Group (France) — Shipbuilder-integrator positioning Sylver-type launch solutions on new frigate classes, capturing lifecycle package opportunities from hull to launcher to test and trials.
- Leonardo (Italy) — Supplier of launcher hardware and system elements, capitalizing on platform-specific relationships and offering tailored retrofit options for legacy fleets.
- Thales Group (France) — Focuses on sensor and combat-system integration with a systems-first approach that reduces integration risk for navies adopting new launchers.
- Saab (Sweden) — A niche competitor with strong combat-management systems and launcher integrations for corvette and patrol-ship classes, attractive to navies seeking compact, cost-effective packages.
Recent industry moves—deliveries of Mk 41 modules to major destroyer programs, VLS upgrade contracts, and platform launches integrating modern VLS—signal continued investment in both new-build and upgrade markets through late 2025. These developments create near-term program windows that suppliers and customers must exploit strategically in 2026.
Supply Chain, Regulation and Geopolitical Noise — Practical Impacts
- Raw-materials volatility: Specialized high-strength steel used for canisters and structural elements experienced a mid‑2025–2026 price shock (≈8% uplift reported by DoD industrial assessments), pressuring margins and contract pricing on short lead-time programs.
- Export controls: ITAR and allied export compliance regimes are actively shaping partner selection and offset requirements; technology transfer limitations are a critical gating factor for cross-border JV strategies.
- Geopolitics and defense budgets: Heightened regional tensions—particularly in the Indo‑Pacific—are accelerating procurement timelines and raising the share of budgets dedicated to VLS-capable ships among key allies.
- Interoperability initiatives: AUKUS and similar frameworks push toward common interfaces and standards, advantaging suppliers who can demonstrate cross-platform compatibility and software-defined launcher management.
For executives, these dynamics translate into three concrete program risks: cost escalation, timeline slippage from compliance approval processes, and competitive displacement if interoperability is not demonstrably addressed in proposals. Each risk has a corresponding mitigation play detailed in the full report.
Actionable Recommendations for 2026 Decision‑Makers
- Prioritize modularity in procurement RFPs: specify open interfaces and software-defined control layers to reduce lifecycle obsolescence risk and enable multi-missile integration.
- Lock in raw-material supply through multi-year contracts and strategic inventory buffers; consider supplier equity or offtake agreements for critical components.
- Embed export‑control compliance into commercial bids early—design consortia and JVs so that sensitive components and technical IP flows are legally segregated while meeting host-nation industrial requirements.
- Shift go-to-market mix toward services and modernization: aftermarket sustainment contracts and mid-life upgrades provide higher-margin, recurring revenue as fleets age.
- Pursue targeted M&A and partnerships to close capability gaps quickly—mid-tier acquisition targets often yield integration know-how and local-content leverage essential to win national tenders.
- Use portfolio scenario analytics: stress-test capital allocation against demand shocks, procurement delays and regulatory friction to identify robust investment pathways under our three forecast trajectories.
How PW Consulting’s Report Enables 2026 Execution
Our full Maritime Missile Launch System Market report translates the macro numbers and competitive map into executable initiatives. Clients receive:
- Complete forecast tables and segmentation (available in the paid report) with sensitivity runs so procurement planners can align capex to realistic demand curves.
- Vendor scorecards and contract negotiation templates tuned to different buyer archetypes (national navy, prime contractor, systems integrator).
- Supply-chain stress-test outputs, including alternative sourcing playbooks for critical raw materials and a supplier-risk index calibrated to 2026 market realities.
- Practical templates for interoperability validation and certification pathways that reduce integration timelines for multi‑national programs.
- A concise M&A playbook: target profiles, valuation multipliers for recurring-service streams, and integration milestones for two- to three-year value capture.
Note: This briefing intentionally omits detailed sub‑segment revenue breakdowns and regional splits to preserve the actionable utility of the full research package. Those detailed tables and our proprietary scenario engine are accessible through PW Consulting’s client portal.
Concluding Note — Time-Sensitive Strategic Windows
2026 presents a compressed decision window for vendors, investors and procurement authorities in the maritime missile launch space. Growth is robust at the macro level, but the shape of that growth will be determined by decisions taken this year around interoperability standards, supply-chain commitments and cross-border industrial partnerships. PW Consulting’s report equips executives with the foresight and the playbooks necessary to capture market share, de‑risk programs and accelerate margin expansion in a landscape where seconds matter as much as ships.
For organizations preparing 2026 procurement or investment plans, the complete report is a practical tool: it converts a USD 14+ billion market underpinned by a 7.12% CAGR into prioritized, executable strategies. Contact PW Consulting to access the full dataset, vendor matrices and the scenario engine that underlies our forecasts.
For detailed analysis of this topic, please visit the official page: Maritime Missile Launch System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: End-Stage Renal Disease Market Projected to Reach USD 305,407.41 Million by 2032, Driven by a 10.45% CAGR
By pmarketresearch, 2026-07-07
End Stage Renal Disease Market 2026: Strategic Imperatives from PW Consulting’s New Market Intelligence
Executive summary
PW Consulting’s End Stage Renal Disease (ESRD) Market report—anchored on a 2025 base year and projecting through 2032—provides executives with the forward-looking intelligence required to make high-stakes commercial, R&D, and M&A decisions in 2026. Our analysis shows a high-growth market trajectory with an embedded compound annual growth rate of 10.45% across the forecast horizon. The report combines rigorous market sizing, competitive mapping, reimbursement scenario modeling, and executable go-to-market playbooks designed for device manufacturers, service providers, and biopharma players navigating the evolving ESRD ecosystem.
End Stage Renal Disease Market
Why this matters for 2026 decision makers
-
Acceleration and convergence: ESRD is no longer a bifurcated market of in-center versus transplant therapy alone. Technological miniaturization, digital therapeutics, and bundled-care models are converging to create new addressable opportunities across acute, chronic, and home care settings.
End Stage Renal Disease Market -
Commercial inflection points: 2026 is shaping up as an inflection year—product launches, regulatory clearances, and payment-rule updates are moving adoption cycles faster, while facility economics are under renewed pressure to optimize throughput and reduce total cost of care.
End Stage Renal Disease Market -
Consolidation and concentration: Market concentration is meaningful—our analysis indicates a concentrated leadership across manufacturing and services, reinforcing the importance of strategic partnerships, differentiated IP, and scale-enabled distribution to win share.
What PW Consulting’s report delivers (practical, transaction-ready content)
-
Validated market sizing and scenario-driven forecasting: A transparent, auditable top-line model with alternate scenarios that reflect adoption curves for home hemodialysis, incremental uptake of high-volume hemodiafiltration, and transplant-rate sensitivity.
-
Reimbursement and regulatory playbook: Line-item analysis showing how recent payment-rule changes, labor-share mechanics, and drug-bundle policies materially affect facility margins and device utilization economics—plus tactical levers for commercial teams to optimize contract negotiations with payors and provider networks.
-
Competitive landscape and capability mapping: Company-by-company strategic profiles, capability heatmaps, and an M&A attrition model that prioritize targets by technology fit, commercial footprint, and integration risk.
-
Commercial go-to-market templates: Pragmatic channel strategies for launching devices and consumables into hospital, outpatient, and home markets; pricing frameworks that reflect bundled-care dynamics; and customer segmentation for salesforce resource allocation.
-
Due-diligence dossier and investment thesis builder: For private equity and corporate development teams—concise checklists, downside-scenario stress tests, and synergy capture roadmaps tailored for acquisitions in ESRD equipment, services, and digital care platforms.
Market dynamics shaping 2026 strategy
Our research synthesizes macro demand drivers (aging demographics, diabetes and hypertension prevalence), technology trends (portable dialysis systems, membrane innovations, and cloud-enabled device connectivity), and policy shifts (payment bundling and labor share adjustments). The net effect is a market expanding rapidly from a sizable 2025 baseline into materially higher levels over the forecast period, with growth concentrated in segments where clinical outcomes and total cost savings can be demonstrated.
Policymakers and payors remain a potent influence. Recent regulatory updates in the ESRD payment framework have adjusted base reimbursement parameters and maintained protections around wage-index volatility—changes that alter the economics of both in-center care and alternatives such as home dialysis and peritoneal modalities. For manufacturers, the implication is clear: demonstrating reduced downstream utilization and simplified operational workflows is as strategically important as device performance.
Competitive landscape: strengths, strategic moves, and risks
The ESRD landscape is populated by legacy OEMs, vertically integrated service providers, and ambitious medtech challengers. Key dynamics to watch in 2026 include product platform rollouts, expanded clinical-service offerings, and the race to secure home-care adoption.
-
Fresenius Medical Care —A global leader with deep clinic ownership and an expansive dialysis product portfolio. Its strategic push into value-based care and the staged commercial introduction of an advanced HVHDF-capable platform position it to capture higher-acuity volume if clinical and reimbursement pathways align. Risk: balancing capital intensity of clinic operations with margin pressures under evolving payor mix.
-
Baxter —Strong in peritoneal solutions and renal consumables, Baxter is well positioned where home modalities and simplified supply chains matter. Their advantage lies in channel reach and product breadth; the challenge is defending against specialized home-system entrants and commoditization on core consumables.
-
DaVita —A service-centric operator with scale in outpatient centers and growing home dialysis programs. DaVita’s leverage is operational expertise and care-management capabilities; strategic partnerships or platform acquisitions could accelerate home adoption, while regulatory payment shifts will influence facility optimization priorities.
-
B. Braun, Nipro, Nikkiso, Toray, JMS, Asahi Kasei —These manufacturers collectively supply machines, dialyzers, membranes, and consumables across global markets. Their competitive playbook is continuous improvement on membranes and device reliability, supply-chain resilience, and regional partnerships. Competitive pressure is highest where differentiation is limited to price.
-
Medtronic —With a focus on vascular access and catheter technologies, Medtronic’s role is critical to improving procedure safety and reducing access-related complications—an area that delivers downstream cost savings and better outcomes, central to payor conversations.
-
Outset Medical & Quanta Dialysis Technologies —Representative of a new breed of modular, all-in-one systems optimized for acute, chronic, and home settings. Outset’s recent regulatory clearance for an upgraded platform and Quanta’s multi-setting clearance underscore the competitive threat to incumbents—these challengers excel in connectivity, cybersecurity, and streamlined consumable usage. Risk profile: commercial scale and service network coverage.
Strategic implications and recommended actions for 2026
-
For device manufacturers: Prioritize platform interoperability, cybersecurity hygiene, and field-service economics. Invest in clinical evidence that quantifies reduced total cost of care and fewer hospitalizations—this will accelerate coverage conversations with payors and accelerate procurement cycles in integrated delivery networks.
-
For service providers and clinics: Re-evaluate facility footprints and labor models in light of reimbursement adjustments that reward efficiency. Expand home-dialysis programs selectively, using cohort-based pilots to demonstrate patient satisfaction and clinical equivalence before large-scale rollouts.
-
For biopharma: Focus on adjunct therapies that reduce dialysis intensity or manage comorbidities common in ESRD. Position products to be meaningfully captured within bundled-payment frameworks by demonstrating additive value to payors.
-
For private equity and M&A strategists: Target assets that bring recurring consumable revenue, scalable service platforms, or differentiated digital tools enabling remote monitoring. Use our scenario models to stress-test exit multiples under alternative reimbursement assumptions.
How to use this report in 90 days
-
90-day commercial sprint: Use the report’s go-to-market templates to re-align sales territories, launch a targeted clinical pilot for a home-dialysis option, or renegotiate distributor agreements with a focus on service SLA and consumable replenishment cadence.
-
90-day regulatory/reimbursement play: Deploy the reimbursement playbook to update payer presentations, align economic models with recent policy changes, and structure value-based contracts that share clinical and financial risk.
-
90-day M&A diligence: Apply the report’s due-diligence checklist and synergy capture workbook to evaluate acquisition targets, using sensitivity analyses to quantify downside exposure from reimbursement shifts.
The PW Consulting advantage
Our report blends primary interviews with dialysis providers, procurement decision-makers, payors, and technology adopters; proprietary shipment and clinic-utilization data; and a repeatable forecasting engine validated against historical out-turns. We intentionally surface strategic levers and commercially actionable insights while withholding granular proprietary splits to preserve competitive confidentiality. For clients, this means immediate, executable guidance plus access to the underlying data tables under license.
Next steps
PW Consulting’s ESRD Market report is designed as a decision-support tool for organizations that need to act confidently in 2026. The public summary establishes the strategic context and headline growth trajectory; the full report contains the detailed segmentation, proprietary models, and company scorecards that will enable precise target selection and commercial planning. To access the complete dataset and unlock the playbooks described above, visit our report page or contact PW Consulting’s ESRD practice team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: End Stage Renal Disease Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com