

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Automotive Automatic Spray Guns Market Reaches USD 1,025.6 Million in 2025, Set to Expand at a 5.85% CAGR Through 2026–2032

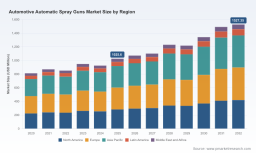
Automotive Automatic Spray Guns Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting’s latest industry briefing previews our comprehensive Automotive Automatic Spray Guns Market report (base year 2025, forecast 2026–2032). As OEMs, tier suppliers, coatings formulators, and private capital plan 2026 investments, this preview highlights the practical intelligence and decision frameworks we provide — without disclosing the proprietary, granular segment data reserved for report subscribers.
Automotive Automatic Spray Guns Market
Market at a Glance: Why the Numbers Matter for 2026
-
Market scale and trajectory: The automatic spray guns market reached USD 1,025.6 Million in 2025 and is projected to grow to approximately USD 1,071.6 Million in 2026, with a compound annual growth rate (CAGR) of 5.85% across the 2026–2032 forecast window.
Automotive Automatic Spray Guns Market -
Competitive structure: Market concentration is moderate — our analysis quantifies the three- and five-firm concentration ratios (CR3 ≈ 38.5%, CR5 ≈ 52.7%) — signaling a marketplace where global leaders and specialized challengers coexist and where strategic partnerships or consolidation can quickly change competitive dynamics.
Automotive Automatic Spray Guns Market -
Strategic timing: Multiple regulatory deadlines and technology adoption cycles converge in 2026–2028, making 2026 a pivotal planning year for capex, supplier selection, and product roadmap alignment.
Why 2026 Is a Pivotal Year for Decision-Makers
-
Regulatory inflection points: North American and European regulatory frameworks (including recent EPA and regional VOC and coating rules) are tightening compliance expectations for VOC emissions and transfer-efficiency standards. These regulations accelerate adoption of HVLP or equivalent high-efficiency automatic technologies and create discrete windows for capital deployment and retrofits.
-
Technology and automation: The push toward higher transfer efficiency, robotics and inline electrostatic solutions to support shorter cycle times and lower waste is reshaping supplier requirements. Integrating spray-gun systems with robotic arms and paint applicator lines is now a standard procurement requirement for many OEM paint shops.
-
Input-cost volatility: Rising costs for stainless steel and specialty nozzle alloys are compressing margins for premium offerings and influencing supplier sourcing strategies — an increasingly important consideration for procurement teams and manufacturers planning product upgrades in 2026.
What the PW Consulting Report Delivers — Practical, Transaction-Ready Intelligence
Our full report combines market sizing, scenario modeling and actionable playbooks tailored to executives who must make capital and sourcing decisions in 2026. Highlights include:
-
Robust forecasting: Top-down and bottom-up modeling across the 2026–2032 horizon, including sensitivity scenarios that stress-test regulatory compliance timelines and raw-material price shocks.
-
Supplier scorecards: Vendor performance matrices that rate firms on transfer efficiency, reliability, total cost of ownership (TCO), service footprint, and robotic integration readiness.
-
Technology benchmarking: Comparative assessments of HVLP, airless and electrostatic automatic systems — focusing on cycle-time impact, paint savings, maintenance intervals and retrofit complexity.
-
Procurement playbook: Step-by-step guidance for supplier selection, negotiation levers, spare-parts strategies and service-level agreements to protect uptime during fleet upgrades.
-
Capex prioritization framework: ROI calculators, payback scenarios and project prioritization matrices tuned to typical OEM and refinishing shop profiles.
-
M&A and partnership diagnostics: Identification of strategic inorganic moves, partnership archetypes, and integration risks to inform both acquirers and target management teams.
-
Regulatory compliance map: Practical compliance timelines that tie regulation milestones to investment triggers and replacement cycles.
Note: The full report includes granular regional and application-level forecasts and segment models that are intentionally excluded from this preview to preserve the confidential intelligence that informs buyers’ strategies.
Core Market Dynamics and Strategic Implications
-
Shift to efficiency-first specifications: OEM procurement teams are increasingly mandating high-transfer-efficiency systems to reduce solvent consumption and overspray. This drives preference for HVLP and electrostatic systems in new plant projects and retrofits.
-
Robotics as a procurement filter: Systems that integrate seamlessly with robotic applicators — both in hardware and digital control — command a premium in RFQs. Suppliers lacking robust robotic interfaces face longer sales cycles or must partner with integrators.
-
Aftermarket/resale potential: Refinishing and collision repair present stable demand streams, but they have different cost sensitivities and service-model needs compared to OEM lines. Manufacturers that offer configurable solutions and localized service networks can expand margins here.
-
Supply-chain risk management: Rising alloy costs and spot-price volatility for nozzle materials necessitate hedged procurement strategies, local qualification of alternate suppliers, and design-for-cost adjustments without degrading performance.
Competitive Landscape — Who Moves the Needle
The report provides a pragmatic assessment of incumbent vendors and regional challengers, with a focus on strategic positioning rather than raw market share. Representative firms we analyze include:
-
Graco Inc. (Minneapolis, Minnesota, USA — https://www.graco.com): Strong in high-transfer-efficiency products and robotic integration; well-positioned for large-scale OEM lines where uptime and automation are critical.
-
SATA GmbH & Co. KG (Kornwestheim, Germany — https://www.sata.com): Known for precision atomization and ergonomics; a compelling option for premium paint shops and OEM integrations emphasizing finish quality.
-
Anest Iwata Corporation (Yokohama, Japan — https://www.anestiwata.com): Offers advanced atomization technologies and a broad catalog that appeals to both OEMs and refinishing networks.
-
Nordson Corporation (Westlake, Ohio, USA — https://www.nordson.com): Deep expertise in electrostatic and powder systems, favored where high-speed, high-uniformity coating is required.
-
EXEL Industries / Sames (Épernay, France — https://www.exel-industries.com): Strong assembly-line offerings with diverse application modes, including airspray and electrostatic options.
-
Carlisle Fluid Technologies (DeVilbiss, Binks — Scottsdale, Arizona, USA — https://www.carlisleft.com): Legacy brands trusted for transfer efficiency and reliability across OEM and refinishing segments.
-
Chinese OEMs such as Ningbo Lis Industrial and Zhejiang Rongpeng ( https://www.lispraygun.com, https://www.rongpeng.com): Competitive on price and customization; increasing presence where localized support and cost are decisive.
Recent market moves underscore evolving competitive dynamics: a 2026 partnership positioning Fuji Spray Auto as a preferred supplier for technical training programs; product previews and catalog updates from established European and Japanese vendors signaling upgrades to their premium lines; and continued emphasis on electrostatic and automation-ready systems. These developments validate our thesis that product differentiation, service ecosystems, and integration capabilities will decide winners in the near term.
Actionable Recommendations for 2026 Decision-Makers
-
For OEM paint-shop leaders: Prioritize pilot projects that validate integration of electrostatic/HVLP systems with your robotic controls before committing plant-wide capex. Use staged rollouts to align training, spare parts, and maintenance contracts.
-
For spray-gun manufacturers: Accelerate alloy-sourcing diversification, and invest in digital interfaces and API support for robot control systems. A service-led model (spare parts + Uptime SLAs) increases customer stickiness.
-
For procurement teams: Leverage our supplier scorecards to negotiate performance-linked contracts, including uptime guarantees and material-consumption KPIs rather than unit price alone.
-
For investors and M&A teams: Target acquisition candidates that fill critical gaps — robotic integration, regional service networks, or proprietary electrostatic technologies — to create rapid scale and margin improvement.
-
For aftermarket service providers: Offer bundled retrofit packages that include training, calibration, and consumables contracts to capture recurring revenue from refinishing shops adapting to stricter VOC rules.
Methodology and Data Integrity
Our methodology synthesizes primary interviews with OEM procurement and paint-shop managers, vendor financials and product catalogs, regulatory filings, trade shipment data and proprietary price indices. The base-year reference is 2025, and forecasts cover 2026–2032. Scenario modeling includes policy-driven adoption curves and raw-material price-shock sensitivities to provide a robust decision-making framework for 2026 planning.
Next Steps — Accessing the Full Intelligence Package
This preview is designed to show the strategic value of the full PW Consulting report for teams preparing 2026 budgets and capital plans. The complete report contains the granular, executable datasets — regional and application-level forecasts, product-level TCO models, and downloadable supplier scorecards — that procurement, engineering and M&A teams rely on to shorten decision cycles and reduce investment risk.
For access to the full dataset, proprietary segment models and a tailored briefing for your leadership team, please visit our report page or contact your PW Consulting account representative. Our team can arrange a 60-minute executive briefing that walks through the decision triggers relevant to your specific business, using the full forecast and supplier analytics in the report.
PW Consulting provides the market intelligence leaders need to convert 2026 uncertainty into strategic advantage — equipping you with the clarity to invest, partner and compete where it matters most.
For detailed analysis of this topic, please visit the official page: Automotive Automatic Spray Guns Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com