

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Liquid Copper Fungicide Market Poised for 4.82% CAGR, New Insights Reveal

Liquid Copper Fungicide Market: Strategic Imperatives for 2026 — PW Consulting Insight Brief
As PW Consulting publishes its comprehensive market study on Liquid Copper Fungicides (base year 2025, historical 2020–2025, forecast 2026–2032), this briefing highlights the strategic implications our analysis delivers for executive decision-making in 2026. The report synthesizes macro drivers, regulatory shocks, input-cost dynamics, and competitor positioning into actionable pathways for manufacturers, distributors, input financiers, and strategic investors. Below we preview the high-level findings and the concrete choices they imply—while preserving the detailed segment-level intelligence that is available exclusively in the full report.
Liquid Copper Fungicide Market
Market at a Glance: Growth trajectory and market scale
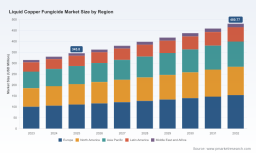
Our market model pegs the global Liquid Copper Fungicide market at approximately USD 346 million in 2025, growing at a compound annual growth rate (CAGR) of 4.82% through 2032. The market expands to an estimated USD 362 million in 2026 and follows a steady upward trajectory to roughly USD 481 million by 2032. This steady mid-single-digit growth masks substantive heterogeneity in risk, margin, and adoption across formulations, geographies, and crop applications—details that are unpacked in the full study.
Liquid Copper Fungicide Market
Why this matters for 2026 strategy
- Timing of investment and product launches. With predictable top-line growth but accelerating regulatory and raw-material volatility, 2026 is a year for targeted, not broad, capital deployment. Companies that time formulation upgrades and commercial roll-outs to regulatory cycles and planting calendars will capture disproportional share.
- Risk-managed supply positioning. Input-cost pressure—amplified by geopolitical trade measures and commodity price spikes—means that firms without proactive hedging or secure long-term feedstock arrangements will face margin compression even with modest top-line growth.
- Regulatory arbitrage and reputation management. The policy environment is increasingly determinative of market access and cost-to-serve. 2026 will reward companies that can demonstrate lower-environmental-impact formulations and robust stewardship programs.
Key market dynamics shaping decisions
- Regulatory tightening and substitution risk. Since 2024–2025 regulatory actions in major markets have raised thresholds for copper use and added worker and environmental safeguards. Some authorities are now treating copper compounds as candidates for substitution due to soil persistence and aquatic toxicity. These trends are crystallizing into dose ceilings, restricted use patterns, and heightened compliance costs—factors that should be incorporated into product life-cycle economics and R&D prioritization in 2026.
- Input-cost volatility and trade policy. Copper feedstock pricing and trade barriers are elevating production risk. Recent episodes demonstrate that tariff proposals and refined-copper import constraints can materially increase landed costs for fungicide manufacturers. For 2026 planning, companies must model scenarios that include sustained elevated raw-material prices and potential supply-chain disruption.
- Innovation as a defensive and offensive lever. Innovation centered on reduced-copper loadings, improved delivery technologies, and synergistic integration with biologicals is shifting the competitive frontier. New product introductions and reformulations that lower environmental load while preserving efficacy create double value—regulatory resilience and market differentiation.
- Channel shifts and farm-level adoption patterns. Adoption among high-value specialty crops continues to drive premiumization, while broad-acre commodities prioritize cost and ease-of-use. Distributors and manufacturers that align portfolio and channel incentives to these distinct buyer logics will outperform.
Competitive landscape: concentration, capability clusters, and tactical moves
The Liquid Copper Fungicide market exhibits moderate concentration. The top three firms account for a material but non-dominant share of revenue, while the top five control just over half of the market—indicating a landscape where national and regional players coexist with global agrichemical majors. This structure creates windows for both scale-driven plays and nimble, local incumbents to exploit differentiated offerings.
Liquid Copper Fungicide Market
- Global agrichemical leaders (scale and channel). Large diversified crop protection companies maintain an advantage in global go-to-market reach, regulatory affairs capacity, and multi-crop bundling. Their ability to combine copper chemistries with systemic products, service models, and farmer programs supports broad uptake in major crop systems.
- Specialists and regional champions (agility and regulatory fit). Firms focused on copper chemistries and regionally tailored formulations are faster at adapting labels, stewardship programs, and distribution partnerships—an asset in markets facing tight, fast-evolving regulatory constraints.
- Recent strategic moves to watch. Mergers, distribution acquisitions, and product launches over the 2024–2025 period demonstrate how participants are responding: expanding regional footprints through distribution acquisitions, introducing lower-impact copper formulations, and seeking regulatory endorsements for revised use patterns. These tactical moves signal where future consolidation and capability aggregation are likely.
What our competitor analysis surfaces
- Competitive positioning is multidimensional: product form (liquid vs. suspension vs. wettable), technical know-how (compound stability and tank-mix compatibility), regulatory dossier depth, and route-to-market strength.
- Global players are investing in stewardship and reformulation; specialist suppliers emphasize conversion paths from granular or powder concentrates into ready-to-apply liquid systems favored by certain crop segments.
- Regional firms leverage local registration acumen and service models for smallholder and high-value markets, retaining resilience even as global players scale back copper exposure in some geographies.
What the full PW Consulting report delivers (practical scope)
- Transparent methodology: historical dataset (2020–2025), detailed forecasting engine (2026–2032) and sensitivity scenarios that isolate regulatory, price, and adoption shocks.
- Segmental intelligence: granular splits by region, formulation type, and application—accompanied by demand drivers, margin profiles, and growth pockets. (Note: segment-level figures are reserved for the full report.)
- Regulatory & stewardship playbook: jurisdiction-level risk scores, compliance cost curves, and recommended label strategies to preserve market access under tightening use limits.
- Supply-chain resilience map: feedstock exposure analysis, tariff and logistics stress tests, and sourcing strategies to mitigate input-cost spikes.
- Commercial playbooks: targeted GTM strategies for channels and crop systems, pricing and promotion scenarios, and farmer adoption roadmaps supported by field-efficacy levers.
- M&A and partnership screening: a proprietary scorecard to identify bolt-on targets and distribution acquisition opportunities that improve regulatory footprint or feedstock security.
Concrete 2026 actions we recommend
- Prioritize reformulation projects that reduce cumulative Cu load. Investing selectively in lower-load or microencapsulated liquid formulations will yield regulatory resilience and premium access in constrained jurisdictions.
- Secure upstream exposure. Negotiate multi-year agreements with copper refiners or diversify to alternative copper chemistries to blunt raw-material swings and tariff-driven cost spikes.
- Accelerate stewardship & compliance investments. Allocate resources to worker-protection measures, environmental monitoring, and label alignment to shorten registration cycles and reduce rework risk.
- Segment GTM by crop economics. Deploy premium, higher-margin formulations in specialty crops while optimizing unit-costs for broad-acre commodity segments through streamlined packaging and logistics.
- Use M&A tactically. Pursue small-to-midscale acquisitions that close distribution gaps in priority markets or add formulation competencies without taking on disproportionate regulatory legacy risk.
Scenario planning essentials for CFOs and strategy teams
Our scenario toolkit models three credible 2026+ environments: (1) Regulatory-Intensified — accelerated phase-out signals and tighter use ceilings; (2) Input-Pressure — persistent elevated copper feedstock prices due to tariffs and supply constraints; (3) Innovation-Accelerated — rapid adoption of reduced-copper and biological-integrated products. Each scenario shifts investment priorities and required working-capital cushions. We recommend stress-testing P&L under each scenario and mapping capital deployment to where optionality and near-term payback overlap.
Closing: strategic value proposition of the report
For 2026, liquid copper fungicide market participants face a paradox: stable aggregate growth alongside intensifying pockets of regulatory and supply risk. Our report equips executives with the quantitative forecasts, regulatory risk scoring, and tactical playbooks needed to convert this complexity into competitive advantage. It is designed not as a static data dump, but as an operational guide that links market intelligence to investment decisions, launch calendars, and M&A prioritization.
To access the full dataset, granular segment breakdowns, proprietary scenario models, and the operational playbooks referenced above, please visit the PW Consulting report page for Liquid Copper Fungicides. The full study includes downloadable spreadsheets, scorecards for acquisition screening, and a customized briefing option for executive teams preparing 2026 operating plans.
For detailed analysis of this topic, please visit the official page: Liquid Copper Fungicide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com