

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Maritime Missile Launch System Market Poised to Reach USD 23,224.47 Million by 2032, Expanding at a 7.12% CAGR (2026–2032 Forecast)

Maritime Missile Launch System Market: Strategic Imperatives for 2026 — PW Consulting Insights
PW Consulting today publishes an executive briefing derived from our comprehensive Maritime Missile Launch System Market report (base year 2025, historical analysis 2020–2025, forecast period 2026–2032). The global market reached USD 14,350 Million in 2025 and, under our central-case scenario, is forecast to expand at a compound annual growth rate (CAGR) of 7.12% through 2032, reaching roughly USD 23,224 Million. This briefing is designed to translate those macro dynamics into concrete decisions for leaders preparing procurement, product and M&A strategies in 2026. In keeping with our “trailer” approach, we surface analytical frameworks, strategic implications and vendor-level context while withholding detailed segment-level tables to preserve the consultative value of the full report.
Maritime Missile Launch System Market
Why 2026 Is an Inflection Point
Several concurrent forces are converging to make 2026 decisive for maritime missile launch systems (MMLS). Geopolitical pressure in the Indo‑Pacific and heightened modernization cycles among NATO and partner navies are increasing demand velocity for vertical and multi-mission launch architectures. Strategic partnerships—most notably interoperability initiatives underpinned by the AUKUS framework—are reshaping specifications and procurement timelines. At the same time, supply chain stress and export-control regimes are elevating program risk, which amplifies the value of robust scenario planning when committing capital or signing long-term supply contracts.
Maritime Missile Launch System Market
Taken together, these drivers mean that market growth is not uniform: it is driven by large-scale platform upgrades, new-build programs, and an accelerating aftermarket for modernization and services. The implication for 2026 decision-makers is clear: timing, procurement structure and partner selection matter as much as product capability.
Maritime Missile Launch System Market
What the PW Consulting Report Delivers
- Proven market-sizing and forecasting methodology calibrated to 2020–2025 historicals and stress‑tested across demand, cost and regulatory scenarios for 2026–2032.
- Scenario-planning playbooks (three core market trajectories) that translate macro uncertainties into procurement- and balance-sheet-ready actions.
- Vendor scorecards and a competitive-matrix that evaluate capability, program execution, integration risk and service potential.
- Supply-chain heatmaps and mitigation templates including raw-material exposures, alternate sourcing pathways and inventory hedging tactics.
- Regulatory and export-control diagnostics with pragmatic compliance roadmaps tailored to ITAR and allied export regimes.
- Commercial strategies: partner selection frameworks, JV structures for local-content compliance, aftermarket service roadmaps and M&A playbooks for mid-tier consolidation.
Competitive Landscape: Established Leaders and Tactical Specialists
The MMLS market is concentrated, with the top three players controlling a substantial majority of market share (CR3 ~62.5%) and the top five accounting for nearly four-fifths of the market (CR5 ~78.9%). This structure favors incumbents capable of delivering platform-integrated systems and multi-year sustainment, while creating targeted openings for specialized firms that can offer disruptive capabilities or cost-effective upgrade packages.
- BAE Systems (United Kingdom) — A long-standing systems integrator with deep naval-shipyard relationships. The company continues to leverage its Mk 41 VLS heritage through upgrade programs and platform integrations for allied navies; recent contract awards for Mk 41 upgrades underscore its role in sustainment and refresh cycles.
- Lockheed Martin (United States) — Dominant in combat-system integration and a primary Mk 41 supplier; ongoing deliveries to major destroyer programs demonstrate the company’s ability to lock in long-term platform-level revenues and sustainment flows.
- Raytheon Technologies (RTX) (United States) — Focused on integrating advanced weapons and launch systems, with product strategies emphasizing modularity and sensor-shooter integration for distributed lethality architectures.
- MBDA (France/UK/Italy) — European powerhouse for integrated vertical launch solutions, advancing upgrade paths and modular interfaces compatible with a range of missile families; active in regional exhibitions and upgrade showcases.
- Naval Group (France) — Shipbuilder-integrator positioning Sylver-type launch solutions on new frigate classes, capturing lifecycle package opportunities from hull to launcher to test and trials.
- Leonardo (Italy) — Supplier of launcher hardware and system elements, capitalizing on platform-specific relationships and offering tailored retrofit options for legacy fleets.
- Thales Group (France) — Focuses on sensor and combat-system integration with a systems-first approach that reduces integration risk for navies adopting new launchers.
- Saab (Sweden) — A niche competitor with strong combat-management systems and launcher integrations for corvette and patrol-ship classes, attractive to navies seeking compact, cost-effective packages.
Recent industry moves—deliveries of Mk 41 modules to major destroyer programs, VLS upgrade contracts, and platform launches integrating modern VLS—signal continued investment in both new-build and upgrade markets through late 2025. These developments create near-term program windows that suppliers and customers must exploit strategically in 2026.
Supply Chain, Regulation and Geopolitical Noise — Practical Impacts
- Raw-materials volatility: Specialized high-strength steel used for canisters and structural elements experienced a mid‑2025–2026 price shock (≈8% uplift reported by DoD industrial assessments), pressuring margins and contract pricing on short lead-time programs.
- Export controls: ITAR and allied export compliance regimes are actively shaping partner selection and offset requirements; technology transfer limitations are a critical gating factor for cross-border JV strategies.
- Geopolitics and defense budgets: Heightened regional tensions—particularly in the Indo‑Pacific—are accelerating procurement timelines and raising the share of budgets dedicated to VLS-capable ships among key allies.
- Interoperability initiatives: AUKUS and similar frameworks push toward common interfaces and standards, advantaging suppliers who can demonstrate cross-platform compatibility and software-defined launcher management.
For executives, these dynamics translate into three concrete program risks: cost escalation, timeline slippage from compliance approval processes, and competitive displacement if interoperability is not demonstrably addressed in proposals. Each risk has a corresponding mitigation play detailed in the full report.
Actionable Recommendations for 2026 Decision‑Makers
- Prioritize modularity in procurement RFPs: specify open interfaces and software-defined control layers to reduce lifecycle obsolescence risk and enable multi-missile integration.
- Lock in raw-material supply through multi-year contracts and strategic inventory buffers; consider supplier equity or offtake agreements for critical components.
- Embed export‑control compliance into commercial bids early—design consortia and JVs so that sensitive components and technical IP flows are legally segregated while meeting host-nation industrial requirements.
- Shift go-to-market mix toward services and modernization: aftermarket sustainment contracts and mid-life upgrades provide higher-margin, recurring revenue as fleets age.
- Pursue targeted M&A and partnerships to close capability gaps quickly—mid-tier acquisition targets often yield integration know-how and local-content leverage essential to win national tenders.
- Use portfolio scenario analytics: stress-test capital allocation against demand shocks, procurement delays and regulatory friction to identify robust investment pathways under our three forecast trajectories.
How PW Consulting’s Report Enables 2026 Execution
Our full Maritime Missile Launch System Market report translates the macro numbers and competitive map into executable initiatives. Clients receive:
- Complete forecast tables and segmentation (available in the paid report) with sensitivity runs so procurement planners can align capex to realistic demand curves.
- Vendor scorecards and contract negotiation templates tuned to different buyer archetypes (national navy, prime contractor, systems integrator).
- Supply-chain stress-test outputs, including alternative sourcing playbooks for critical raw materials and a supplier-risk index calibrated to 2026 market realities.
- Practical templates for interoperability validation and certification pathways that reduce integration timelines for multi‑national programs.
- A concise M&A playbook: target profiles, valuation multipliers for recurring-service streams, and integration milestones for two- to three-year value capture.
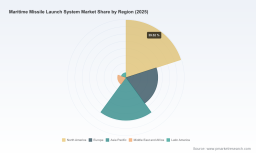
Note: This briefing intentionally omits detailed sub‑segment revenue breakdowns and regional splits to preserve the actionable utility of the full research package. Those detailed tables and our proprietary scenario engine are accessible through PW Consulting’s client portal.
Concluding Note — Time-Sensitive Strategic Windows
2026 presents a compressed decision window for vendors, investors and procurement authorities in the maritime missile launch space. Growth is robust at the macro level, but the shape of that growth will be determined by decisions taken this year around interoperability standards, supply-chain commitments and cross-border industrial partnerships. PW Consulting’s report equips executives with the foresight and the playbooks necessary to capture market share, de‑risk programs and accelerate margin expansion in a landscape where seconds matter as much as ships.
For organizations preparing 2026 procurement or investment plans, the complete report is a practical tool: it converts a USD 14+ billion market underpinned by a 7.12% CAGR into prioritized, executable strategies. Contact PW Consulting to access the full dataset, vendor matrices and the scenario engine that underlies our forecasts.
For detailed analysis of this topic, please visit the official page: Maritime Missile Launch System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com