

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Bluetooth Audio IC Market Set to Expand at an 11.85% CAGR Through 2032 as TWS and Dual‑Mode ICs Drive Growth

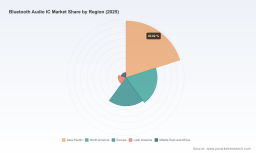
Bluetooth Audio IC Market 2026: Strategic Imperatives from PW Consulting’s Forthcoming Industry Brief
Executive snapshot
PW Consulting’s new Bluetooth Audio IC Market report (base year 2025, forecast 2026–2032) synthesizes market, technology and competitive intelligence into an operational playbook for decision-makers entering 2026. At a macro level, the Bluetooth audio IC market expanded from USD 3,820.5 Million in 2020 to USD 6,720.0 Million in 2025, and our top-line model projects the market to grow to approximately USD 14,717.08 Million by 2032 — implying a compound annual growth rate (CAGR) of 11.85% over the forecast window. Market concentration remains meaningful (CR3 ~58.4%; CR5 ~72.2%), creating both opportunity and entry barriers depending on a firm’s strategic posture.
Bluetooth Audio Ic Market
Why this report matters for 2026 planning
-
Strategic clarity in a technology inflection: 2024–2026 marks the industry’s transition from legacy audio profiles to LE Audio, LC3 codecs and expanded low‑power topologies. Firms that align product roadmaps and supply strategies with these shifts will capture disproportionate value.
Bluetooth Audio Ic Market -
Supply‑chain resilience during geopolitical friction: export controls, tariffs and foundry lead‑time normalization are tangible constraints that must be embedded in sourcing and product timing decisions.
Bluetooth Audio Ic Market -
Competitive positioning: with a moderate-to-high concentration among top vendors, nuanced vendor selection, IP licensing and co‑development strategies are critical for OEMs and fabless entrants.
What the report delivers — practical, transaction‑ready intelligence
This is not a theoretical forecast. The report is structured to be used at the board and product‑line level to make 2026 resource allocation, procurement and M&A decisions. Key deliverables include:
-
A validated top‑down market model that reconciles historical shipments and revenue (2020–2025) with a granular forecast (2026–2032) — including scenario runs for technology adoption and price deflation curves.
-
Technology adoption maps that align Bluetooth core releases (including Bluetooth 5.4 and LE Audio mandates such as LC3) with product life cycles across hearables, speakers, automotive gateways and wearable segments.
-
Supplier and component risk matrices that integrate foundry lead times (post‑shortage normalization in 40nm processes), export control exposure and tariff impacts to quantify supply risk and cost exposure by sourcing strategy.
-
Commercial playbooks for OEMs and chip vendors — including go‑to‑market sequencing, channel structuring, pricing levers and software/service monetization options (e.g., codec licensing, bundled voice/ANC algorithms, and ecosystem integrations such as Matter).
-
Deal support tools: vendor scorecards, an M&A screening framework tuned to Bluetooth IC economics, and LBO/ROI templates for near‑term consolidation opportunities.
Market dynamics: drivers, constraints and inflection points
-
Driver — LE Audio and Low‑Power Codecs: The LC3 codec and LE Audio profile represent the most significant tech driver for the next phase of growth. They enable superior perceived quality at lower bitrates and open functionality (audio sharing, improved hearing aids support) that widens addressable markets.
-
Driver — Consumer hearables and immersive audio: Continued demand for true wireless stereo (TWS) with better ANC, spatial audio and lower latency keeps product cycles short and upgrade rates high for premium segments.
-
Constraint — Geopolitical and regulatory overlay: Export controls on advanced semiconductor manufacturing equipment and trade actions (including recent tariff considerations) are reshaping supplier strategies and may lengthen qualification cycles for cross‑border sourcing.
-
Constraint — Foundry cadence and node economics: While lead times for legacy nodes (e.g., 40nm) have stabilized versus the shortages of 2020–2023, capacity planning and multi‑node sourcing remain essential for cost and time‑to‑market control.
Competitive landscape — what to watch in 2026
The market exhibits a hybrid structure: several large, vertically integrated incumbents maintain substantial share while specialized regional and systems‑level players push on price/performance or unique IP. Our report profiles each strategic player across product roadmaps, channel reach and IP stacks. Highlights:
-
Qualcomm (San Diego): Continues to lead on integrated solutions and value‑added software stacks (e.g., Snapdragon Sound, aptX family, and LE Audio support). Expect continued emphasis on system‑level differentiation — silicon + software + certification pathways.
-
Realtek (Hsinchu): Competes aggressively on cost‑performance for mass segments with SoC families optimized for TWS. Watch their moves on platform integrations and reference designs that accelerate OEM qualification cycles.
-
Airoha Technology (Zhubei): Positioned for premium TWS with low‑latency and AI‑assisted ANC; certifications around LE Audio increase attractiveness to premium hearable OEMs.
-
BES Technic (Shanghai): Focused on high‑fidelity audio and power efficiency specific to TWS and hearables — incremental innovations in ANC and spatial audio are differentiators.
-
Nordic Semiconductor (Trondheim) and Texas Instruments (Dallas): Niche leadership in LE Audio stacks and low‑power SoCs for hearables, wearables and audio gateways; valuable partners for OEMs targeting fast time‑to‑market with new Bluetooth profiles.
-
Espressif (Shanghai) and STMicroelectronics (Geneva): Compete on embedded platforms combining Wi‑Fi/Bluetooth convergence and MCU integration — relevant for IoT and smart speaker implementations.
Recent vendor moves we track (examples): new LE Audio‑capable SoC introductions, sample programs for ultra‑low power chips, and product certifications that shorten OEM adoption cycles. These signals accelerate adoption curves and should be read as leading indicators rather than isolated press items.
Strategic implications and recommended actions for 2026
Our work translates insight into immediate actions. For C‑suite and product leads preparing 2026 plans, PW Consulting recommends the following prioritized steps:
-
Embed LE Audio into the product roadmap now: prioritize LC3 codec plans and software stack readiness in product specifications for any new hearable or gateway launches scheduled in 2026–2027.
-
Adopt a dual‑track sourcing strategy: qualify at least two suppliers across different geographies and node ecosystems to mitigate export control and tariff shocks while preserving price competitiveness.
-
Pursue software and services monetization: move beyond silicon sales — codec licensing, cloud‑enabled audio features and subscription services increase lifetime value and create differentiation.
-
Accelerate collaboration with hyperscalers and standards bodies: interoperability and certification (e.g., Matter integrations, Bluetooth SIG timelines) materially shorten OEM time to market — engage early.
-
Use concentration strategically: small-to-medium players should target white‑space product niches and partner with higher‑tier vendors for co‑development. Large incumbents should consider tuck‑ins to secure IP in ANC/spatial audio or low‑power audio algorithms.
-
Operationalize a regulatory‑aware product calendar: layer compliance and export risk into lead‑time assumptions and inventory policy to avoid late‑stage qualification delays and pricing shocks.
What we intentionally withhold — and why
In keeping with our “trailer” principle, this release highlights the analytical depth, strategic conclusions and operational tools included in PW Consulting’s Bluetooth Audio IC Market report, but it does not reproduce the detailed segmentation tables, regional/application percentage splits or supplier scorecard numerical grids that are central to vendor selection and deal execution. Those datasets are curated, proprietary, and presented in interactive formats (model workbooks, supplier matrices and scenario dashboards) within the paid report to preserve commercial value and prevent misinterpretation outside context.
How to use the full report in 2026 decision cycles
Clients typically use our deliverables in three ways: (1) immediate 90‑day actions (supplier qualification and roadmap adjustments), (2) medium‑term investment planning (capex and R&D prioritization aligned with forecasted price declines and volume ramps), and (3) M&A screening (target lists based on product/technology gaps and market access). The report’s scenario module enables finance and strategy teams to stress‑test plans under different technology adoption and tariff outcomes — making it a practical tool for 2026 budgeting rounds.
Next steps
For procurement leads, product managers and corporate strategists preparing 2026 plans, the full PW Consulting Bluetooth Audio IC Market report contains the operational datasets, vendor playbooks and financial templates needed to translate market momentum into measurable outcomes. To access the interactive models, supplier scorecards and full vendor profiles, please visit PW Consulting’s reports page or contact our industry practice team for a briefing and tailored executive summary.
For detailed analysis of this topic, please visit the official page: Bluetooth Audio Ic Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com