

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts IoT UTM Market to Surge at 22.15% CAGR, Reaching USD 25.5 Billion by 2032

PW Consulting Strategic Brief: IoT Security Solution for Unified Threat Management (UTM) Market — A 2026 Playbook for Decision-Makers
The convergence of pervasive IoT deployments and escalating threat sophistication has pushed Unified Threat Management (UTM) for IoT from a niche network hygiene topic to a board‑level strategic imperative. Our new market study, "IoT Security Solution For Unified Threat Management (UTM) Market," synthesizes five years of historical data and a seven‑year forecast to deliver operational guidance for procurement, architecture, and risk governance teams making investment decisions in 2026.
Iot Security Solution For Unified Threat Management Utm Market
Why this report matters in 2026
-
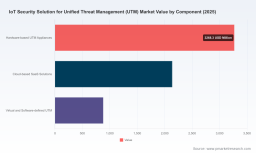
Market momentum: The IoT UTM market has moved from early consolidation into rapid commercialization. In numeric terms, our base‑year analysis shows the market expanded from USD 4,212.45 million in 2023 to USD 6,285.20 million in 2025, and is forecast to grow to USD 25,501.94 million by 2032. The forecast period (2026–2032) implies a compound annual growth rate (CAGR) of 22.15%, underscoring both opportunity and disruption.
Iot Security Solution For Unified Threat Management Utm Market -
Strategic timing: 2026 is the inflection point for many enterprises — regulators are tightening product and data responsibilities, architectures are shifting toward cloud‑native and service models, and suppliers are layering AI and zero‑trust capabilities into core UTM offerings. Decisions made this year define security posture and procurement exposure across the next hardware and software refresh cycles.
Iot Security Solution For Unified Threat Management Utm Market -
Practical orientation: This report is designed as a practitioner's toolkit for C‑suite and security leaders — not an academic exercise. It maps market trajectories to operational choices that matter to 2026 budget cycles and 3–5 year roadmaps.
What the report delivers: operational, decision‑grade intelligence
-
Robust market sizing and trend diagnostics — an audited historical series (2020–2025) and a detailed seven‑year forecast (2026–2032) that link macro drivers to addressable spend categories.
-
Buyer personas and procurement playbooks — role‑specific checklists for CISOs, procurement directors, and MSP partners that translate risk appetite into procurement language (service levels, patch cadences, indemnities, and escrow provisions).
-
Deployment and migration frameworks — validated blueprints for integrating UTM into heterogeneous IoT estates, covering brownfield segmentation, telemetry collection, SOC ingestion, and automation paths for incident response.
-
Vendor evaluation tools — scorecards that combine technical capability, product roadmaps, delivery model maturity (hardware, virtual, cloud), and commercial flexibility—designed to be used in RFPs and due diligence.
-
Regulatory and compliance mapping — alignment matrices that translate obligations under emerging frameworks (e.g., EU Cyber Resilience Act, EU Data Act, China’s network/data rules, and U.S. Bulk Data controls) into contract clauses and operational controls.
-
Financial models and TCO scenarios — configurable templates that quantify direct costs, service fees, integration effort, and the implied value of managed/co‑managed service options over multi‑year horizons.
-
Risk scenarios and playbooks — prioritized threat scenarios for industrial, healthcare, and critical‑infrastructure IoT use cases, with actionable mitigation sequences and measurable KPIs.
Competitive landscape — who matters and why
The vendor landscape blends established network security vendors, cloud developers, and specialist appliance suppliers. Market concentration is material but not prohibitive: our CR3 sits in the high‑thirties and CR5 is slightly north of the mid‑fifties, indicating a field where a few leaders set broadly accepted technical and commercial norms, while mid‑tier and regional players maintain important niches.
-
Fortinet, Inc. (Sunnyvale, CA — https://www.fortinet.com) continues to leverage integrated NGFW/UTM platforms that emphasize IoT device visibility, segmentation, and scalable threat management for distributed estates.
-
Cisco Systems, Inc. (San Jose, CA — https://www.cisco.com) advances a blended model across Secure Firewall and Meraki lines, integrating device profiling and threat intelligence into a single operational fabric.
-
Check Point Software Technologies Ltd. (Tel Aviv — https://www.checkpoint.com) positions its NGFW and cloud products to emphasize policy enforcement and threat prevention across hybrid deployments.
-
Sophos Ltd. (Abingdon, UK — https://www.sophos.com) focuses on unified management simplicity and continuous update streams for UTM appliances and virtual platforms.
-
WatchGuard Technologies, Inc. (Seattle, WA — https://www.watchguard.com) and SonicWall Inc. (Milpitas, CA — https://www.sonicwall.com) continue to serve channel ecosystems with differentiated appliance portfolios and partner‑centric services.
-
Barracuda Networks, Inc. (Campbell, CA — https://www.barracuda.com) and Juniper Networks, Inc. (Sunnyvale, CA — https://www.juniper.net) prioritize cloud connectivity and AI‑driven management for multi‑site environments.
-
Huawei Technologies Co. Ltd. (Shenzhen — https://www.huawei.com) addresses global telco and large enterprise accounts with integrated UTM features and network stack tightness in its portfolio.
-
Palo Alto Networks, Inc. (Santa Clara, CA — https://www.paloaltonetworks.com) emphasizes device identification, Zero Trust enforcement, and high fidelity telemetry for SOC integration.
Recent vendor moves underscore the pace of innovation and go‑to‑market shifts: product refreshes that embed ZTNA and cyber warranties, new SASE/SASE‑adjacent entries for SME channels, and continuous firmware/software refreshes that bear directly on lifecycle risk. These shifts influence which vendors are suitable for greenfield, brownfield, or heavily regulated environments.
Regulatory and infrastructure dynamics that will shape 2026 choices
-
Regulation: The EU Cyber Resilience Act and the EU Data Act are moving liability and data portability obligations into product lifecycles — procurement must now evaluate supplier update commitments, vulnerability disclosure policies, and contractual liability caps.
-
Cross‑border data constraints: New rules in large markets require careful architecture decisions on telemetry storage and cross‑border transfers; procurement must bake localization and legal assessments into vendor selection.
-
Cost inputs: Rising data center and infrastructure costs are increasing the attractiveness of cloud‑first and managed consumption models for telemetry and analytics, altering comparative TCOs for on‑prem appliances versus SaaS/virtual options.
Actionable recommendations for 2026 decision cycles
-
For CISOs: Prioritize a roadmap that converts asset‑rich IoT environments into enforceable security domains. Insist on vendor commitments for secure-by‑design patch cadences, SBOM availability, and integration with SIEM/SOAR platforms. Treat UTM selection as a control platform, not just a perimeter appliance.
-
For Procurement: Move beyond price and horsepower. Use the report’s vendor scorecards to evaluate supply‑chain resilience, indemnity language aligned to new regulations, and co‑managed service options that reduce in‑house lifecycle burden.
-
For MSPs/MSSPs: Design co‑managed bundles that combine device discovery, segmentation policy templates, and continuous monitoring, creating predictable revenue streams as enterprises outsource operational complexity.
-
For Technology Leaders: Adopt a hybrid architecture play that allows selective offload to cloud analytics while keeping critical enforcement points on premises. Implement identity‑first segmentation and automated micro‑containment for high‑risk device classes.
Risks and scenarios executives should model now
-
Regulatory acceleration: Faster or broader adoption of product‑liability regimes could materially shift vendor economics — build clauses that require regular evidence of OTA update practices and vulnerability management.
-
Lock‑in and migration friction: Avoid hard dependency on single‑vendor telemetry formats; insist on exportable telemetry, documented APIs, and migration playbooks.
-
Supply and cost shocks: Infrastructure and raw material cost escalation can change the balance of appliance vs. service economics; stress‑test TCO models under higher data center costs.
-
Threat evolution: AI‑augmented offensive capabilities and supply‑chain attacks mean that detection and response timelines must compress — evaluate vendors on detection speed and automation depth, not just prevention metrics.
How to use this study as a decisioning instrument
The study is intentionally tactical: each chapter connects market dynamics to executable choices. Use the market forecast to set portfolio allocation envelopes; use the regulatory mapping to adjust contract language; use the vendor scorecards to narrow a long list to a defensible short list; and use the deployment blueprints to accelerate secure rollout with measurable KPIs.
Our "trailer" approach here highlights the strategic contours and operational takeaways that will matter in 2026. For procurement‑grade subsegment economics, country‑level forecasts, granular component breakouts, and the full vendor scorecards (including third‑party validation and channel positioning), refer to the full report available from PW Consulting. The full dataset and appendices contain the granular inputs you will need to finalize RFPs, capital plans, and compliance attestations for the coming planning cycles.
Final note
Enterprises that treat IoT UTM as an architectural program rather than a point purchase will capture disproportionate risk reduction and operational efficiencies across their IoT lifecycles. With the market expanding rapidly and regulation increasing supplier accountability, 2026 is the year to convert market intelligence into procurement discipline, architecture clarity, and measurable security outcomes. PW Consulting’s full report equips teams to do precisely that.
For detailed analysis of this topic, please visit the official page: Iot Security Solution For Unified Threat Management Utm Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com