

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Fully Closed Ventilator Breathing Circuit Market to Grow at 5.22% CAGR, Reaching USD 1,693.25 Million by 2032

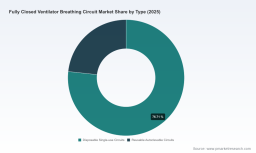
Fully Closed Ventilator Breathing Circuit Market — Strategic Imperatives for 2026
PW Consulting’s new market study on Fully Closed Ventilator Breathing Circuits is designed as the operational intelligence playbook that healthcare OEMs, strategic buyers, hospital procurement teams, and investors will use to shape decisions in 2026. Built on a publicly validated forecasting approach and primary interviews across clinical, regulatory and procurement stakeholders, the report translates macro momentum into executable strategic choices. The headline: the market has expanded from roughly USD 940.3 Million in 2020 to an estimated USD 1,185.86 Million in 2025 (base year), and is forecast to grow to approximately USD 1,278.06 Million in 2026 and beyond — a compounded annual growth rate (CAGR) of 5.22% across the 2026–2032 forecast window, reaching roughly USD 1,693.25 Million by 2032.
Fully Closed Ventilator Breathing Circuit Market
Why 2026 is a Pivotal Year
-
Market inflection: After a period of post-pandemic consolidation, 2026 is when product differentiation — not just capacity — will determine winners. Growth is steady and driven by clinical emphasis on infection control, closed-system compatibility with modern ventilators, and technologies that materially reduce condensate and circuit maintenance frequency.
Fully Closed Ventilator Breathing Circuit Market -
Procurement transition: Hospitals and integrated delivery networks are shifting procurement criteria from lowest cost per unit to total cost of ownership (TCO), factoring in reduced circuit breaks, lower device-associated infection rates, and servicing overhead. For manufacturers, this creates an opening for bundled consumable-service models.
Fully Closed Ventilator Breathing Circuit Market -
Regulatory and reimbursement pressure: Continued harmonization around ISO connector standards and guidance within 21 CFR pathways means product interoperability and documented performance will be commercial prerequisites in many markets. Meanwhile reimbursement complexity (e.g., HCPCS billing constraints) is squeezing standalone pricing leverage for breathing circuits, especially where they are tied to higher-frequency servicing codes.
Technology and Clinical Drivers — What Really Moves Adoption
-
Condensate management technologies — permeable membranes, vapour-permeable tubing, and embedded heated-wire approaches — are no longer niche: they materially extend closed-system run-times and reduce water trap changes, directly affecting clinical workflow and device-associated pneumonia risk. Examples of these approaches appear across leading vendors’ portfolios and are central to clinical value propositions.
-
Disposable versus reusable dynamics are being re-evaluated through lifecycle lenses: infection-control priorities and single-patient disposable strategies increase demand for single-use, while sustainability and cost pressures keep reusable autoclave-capable options relevant in specific settings.
-
Closed suction integration: systems that preserve circuit integrity while enabling secretion management are becoming essential in bundled ventilator-care pathways. Clinical guidelines and hospital protocols increasingly list closed suctioning as part of VAP reduction bundles.
Competitive Landscape — Leaders, Challengers and Strategic Positioning
The competitive field is mixed: global ventilator and anesthesia players offer integrated systems and scale; specialised respiratory-supply manufacturers emphasise niche technical differentiation and fast innovation cycles. Market concentration is moderate — the combined share of the top three players is approximately 38.5%, and the top five combine for roughly 52.3% — indicating meaningful room for niche specialists and M&A consolidation.
-
Fisher & Paykel Healthcare (Auckland) — A technology leader in humidification and condensate management with the Evaqua family and permeable membranes. Recent regulatory activity (including multiple 510(k) clearances in 2025) reinforces their product-compatibility play across single- and dual-limb applications and extends their non-invasive ventilation accessory footprint.
-
Armstrong Medical (UK) — Focused on heated circuits with vapour-permeable approaches that reduce water-trap dependency. Their product design philosophy targets long closed-circuit runs, an attractive proposition for high-acuity hospitals looking to reduce circuit handling.
-
Major ventilator OEMs and critical-care suppliers (Dräger, Medtronic, Hamilton Medical, Teleflex, ICU Medical) — Leverage integrated device-channel relationships and established hospital procurement contracts to bundle circuits with ventilator systems or disposables portfolios; their scale supports global distribution but can be slower to iterate niche condensate innovations.
-
Regional and specialised manufacturers (Plasti-med, Unimax, Besdata, GaleMed, Cathwide, Besmed) — Compete through localized manufacturing, cost flexibility, and focused product variants such as closed suction-compatible circuits, spiral embedded heated-wire designs, and short-run customization for neonatal or specialty ventilation.
For market entrants and investors, the strategic calculus is clear: mobility across contract channels and a defensible IP/technology advantage in humidity and condensate management will win premium positioning, while scale and integration enable steady share capture in institutional channels.
Regulatory, Reimbursement and Clinical Context — Framing Risk and Opportunity
-
Regulatory baseline: Breathing circuits fall under established device classifications (including 21 CFR 868.5240 and related accessory classifications) and must meet ISO connector and performance standards (e.g., ISO 5367). Compliance plus clear clinical-use validations materially reduces adoption friction among buying hospitals.
-
Reimbursement nuance: In certain jurisdictions, breathing-circuit codes exist but are constrained when billed alongside frequent servicing codes — a dynamic that erodes unit-level pricing power and elevates the importance of demonstrating TCO advantages tied to clinical outcomes.
-
Clinical imperative: Closed systems that demonstrably reduce ventilator-associated complications align with infection-control bundles and are increasingly used as evidence in procurement RFPs. Clinical evidence and real-world utilization data are decisive in converting pilot projects into enterprise contracts.
What PW Consulting’s Report Delivers — Practical, Executable Intelligence
-
Market forecast model (USD Million) with sensitivity scenarios across 2026–2032, including downside/recovery and adoption inflection permutations.
-
Technology ROI calculators that quantify savings from extended closed-circuit runtime, reduced water-trap changes, and lower VAP incidents — convertible into hospital procurement scorecards.
-
Supplier scorecards and comparative matrices covering product specifications, clinical evidence strength, regulatory status, manufacturing footprint and supply-chain resilience.
-
Regulatory roadmap and ISO/21 CFR conformance checklist for rapid product registration planning and risk mitigation by geography.
-
Commercial playbooks: tender and RFP templates, channel-partner models, and pricing architectures aligned to TCO messaging rather than unit price competition.
-
M&A and partnership shortlists: targeted diligence checklists for bolt-on technology, clinical data asset acquisition, and regional manufacturing scale-ups.
-
Patient-setting adoption maps and go-to-market segmentation that translate macro forecasts into targeted near-term opportunities — from high-acuity hospital ICUs to ambulatory and home-care settings.
Actionable Recommendations for 2026
-
For manufacturers: Prioritise condensate-management IP and interoperability with leading ventilator platforms. Invest now in clinical outcomes studies that convert operational benefits (reduced handling, fewer circuit breaks) into procurement KPIs.
-
For distributors and service providers: Build bundled maintenance and consumables offers that explicitly reduce buyer TCO; create flexible contract terms that scale with usage intensity.
-
For hospital systems and IDNs: Reframe procurement metrics to include clinical impact and lifecycle cost. Pilot closed-circuit technologies in high-acuity units where benefits on device-associated infection and staff time are most measurable.
-
For investors and M&A teams: Target specialised technology vendors with demonstrable condensate-management advantages and strong clinical evidence. Consider roll-up strategies to create a full-stack respiratory-consumables provider with cross-sell synergies.
How to Use This Report in Your 2026 Planning Cycle
This study is structured as an execution tool for 2026 planning cycles. Use the forecast and scenario outputs to size near-term addressable markets for new product launches. Leverage supplier scorecards during RFP reformulation. Deploy the ROI tools in internal business-cases to reprice circuits on a TCO basis. And, for C-suite decision-making, apply the M&A screen to prioritize targets that accelerate time-to-market for differentiated humidification solutions.
Next Steps — Where to Find the Full Intelligence
PW Consulting’s full report contains the granular segment and regional breakdowns, vendor-specific scorecards, and downloadable financial models that procurement teams, corporate strategy groups, and investors will need to finalize 2026 initiatives. This release intentionally highlights the strategic insights and market trajectory without disclosing sensitive segment-level tables — to access the complete dataset, vendor benchmarking and templated playbooks, please visit PW Consulting’s report portal or contact our industry practice.
For detailed analysis of this topic, please visit the official page: Fully Closed Ventilator Breathing Circuit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com