

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Friction Stir Welding Equipment Market to Reach USD 341.75M by 2032 (6.7% CAGR)
By pmarketresearch, 2026-07-08
Friction Stir Welding Equipment Market: Strategic Imperatives for 2026
Executive synopsis
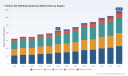
As manufacturers accelerate electrification, lightweighting and high-integrity joining in aerospace, automotive, rail and shipbuilding, Friction Stir Welding (FSW) has moved from niche innovation to mainstream production technology. Our latest PW Consulting market study — anchored on a 2025 base year and projecting through 2032 — shows the global FSW equipment market expanding at a steady compound annual growth rate of approximately 6.7%. Market value growth between 2025 and 2032 underscores material demand for scalable, robot-enabled and hybrid FSW systems across multiple heavy-industry value chains.
Friction Stir Welding Equipment Market
Why this research matters to corporate decision-makers in 2026
-
Strategic capital allocation: With predictable mid-single-digit CAGR and visible upside from EV and aerospace programs, executive teams can time CAPEX for FSW automation with greater confidence. Our study translates macro growth into phased investment horizons, payback scenarios and technology-risk overlays that align with fiscal planning cycles.
Friction Stir Welding Equipment Market -
Supplier and partner selection: FSW supplier choice now drives product architecture as much as cost. The report profiles incumbent machine OEMs, robotics integrators and niche head/ spindle suppliers — enabling procurement to run rigorous make-or-buy, co-development and qualification roadmaps.
Friction Stir Welding Equipment Market -
Regulatory and quality readiness: ISO 25239-series requirements are increasingly enforced in aerospace and safety-critical manufacturing. We map procedure qualification and operator certification levers to program timelines so quality teams can avoid late-stage rework and certification bottlenecks.
-
Risk-adjusted scenario planning: Raw material volatility, labor shortages and energy mandates are now core to welding strategy. The study quantifies sensitivity to aluminium price swings and technician availability, and offers hedging and automation scenarios that materially impact TCO.
Report scope — what you will find (and what we deliberately withhold here)
-
End-to-end market sizing and forecasting from 2020 through 2032, with a transparent methodology and stress-tested scenarios for low-, base- and high-growth paths.
-
Detailed segmentation by equipment type, application and geography — presented with supplier maps and adoption curves. (Note: To preserve the commercial utility of the dataset, granular subsegment values and percent shares are available in the full report only.)
-
Operational playbooks: CAPEX calculators, OEE impact templates, robotic cell layout heuristics, and a rapid qualification checklist aligned to ISO 25239.
-
Competitive intelligence: Comparative capability matrices, product roadmaps and acquisition targets derived from primary interviews and recent transaction/partnership tracking.
-
Strategic scenarios: Three prioritized strategic paths — (1) automation-led scale for high-volume automotive/e-mobility, (2) systems-integration for aerospace and pressure-vessel applications, and (3) service- and aftermarket-led monetization for decentralized fabrication networks.
Market dynamics shaping 2026 decisions
-
Technology adoption and product differentiation — Robotic FSW and hybrid CNC-FSW units are becoming the default for manufacturers seeking repeatable high-throughput joints with low post-process finishing. Vendors that offer fully integrated head/spindle packages, robust process control and digital monitoring command commercial leverage during qualification cycles.
-
Raw-material and input-cost sensitivity — Aluminium feedstock price movements materially affect upstream material choice and welding economics. For example, recent trading in aluminium has tightened margin assumptions for high-volume structures and influences make-vs-buy decisions for thick-plate versus sheet joining.
-
Standards and certification — The ISO 25239 series now forms the backbone of FSW procedure qualification in regulated industries. Programs that integrate these requirements early in the design and procurement stage reduce time-to-market and avoid late-stage redesigns.
-
Labor and skills — Advanced FSW cells require multi-disciplinary skills (robot programming, process metallurgy, fixture design). Our fieldwork documents substantial shortages in skilled technicians at smaller OEMs; mitigations include strategic partnerships with integrators, in-house training academies and digital twin-enabled upskilling.
-
Energy and sustainability — FSW delivers material energy advantages versus traditional fusion welding methods; typical process-level gains can be in the low- to mid-teens percentage range for energy consumption. This creates an operational and reputational incentive for sustainability-minded manufacturers pursuing Scope 1/2 reduction targets.
How incumbent vendors and new entrants are positioning — competitive implications
-
MTI Welding (United States): A global machine OEM with STIRTEC know-how focused on industrial-scale systems. Strengths lie in turnkey systems and deep industrial experience; they compete strongly for large programs requiring process certification and onsite support.
-
Mazak Corporation (Japan): Positions FSW as an integrated capability within hybrid multi-tasking CNC platforms. Their strategy targets customers seeking consolidation of machining and joining to reduce footprint and part handling.
-
PAR Systems (United States): Offers large-format I-STIR™ cells tailored to heavy fabrication. Their competitive advantage is in handling complex geometry and large work envelopes.
-
FOOKE GmbH and Quickmill (Germany / United States): Both bring high-performance gantry-style solutions and emphasize precision sheet and plate joining — particularly attractive for OEMs seeking repeatable panel welds at scale.
-
Stirweld (France): Specialist in FSW heads and spindles for robotic integration. Their modular head approach enables retrofit pathways and is attractive to machine shops and integrators seeking to add FSW capability without wholesale system replacement.
-
Bond Technologies and FPT Industrie (United States / Italy): Focus on industrial system solutions and niche OEM partnerships; they compete for aerospace and rail programs where qualification and traceability are critical.
-
KUKA AG (Germany): As a robotics integrator, KUKA is winning orders for FSW robotic cells that support EV battery housing assembly and other high-volume use cases, leveraging its robot portfolio and systems expertise.
Recent industry moves that matter for 2026 strategy
-
Collaboration on advanced heads: Partnerships showcasing retractable-pin FSW heads for hydrogen-storage-grade aluminium tanks signal an emerging aerospace/space opportunity where joint integrity and certification are non-negotiable.
-
High-volume automotive orders: Large robotic FSW cell procurements for electric vehicle housings indicate OEMs are moving from pilots to production. Procurement and industrialization teams must align supplier qualification windows with vehicle program milestones.
-
Trade-show technology evangelism: Public demonstrations and showcases by OEMs and integrators reduce perceived technology risk and accelerate buyer education. Buyers should treat these as indispensable due-diligence inputs but validate performance in customer-specific conditions.
Strategic actions for 2026 planning cycles
-
Short-term (0–12 months): Lock in supplier pilots tied to specific program KPIs (cycle time, rejection rate, energy use), run procurement RFIs that capture qualification support and spare-parts SLAs, and start operator certification programs aligned to ISO 25239.
-
Medium-term (12–36 months): Scale robotic FSW cells in prioritized product lines, build retrofit roadmaps for legacy machining assets using modular heads, and evaluate captive vs outsourced coating/finishing strategies to maximize throughput.
-
Long-term (36+ months): Consider M&A to secure critical head/spindle IP, invest in digital twins for virtual qualification, and develop service-led revenue models that monetize preventive maintenance and process optimization.
Operational levers and KPIs we recommend tracking
-
Qualification lead time to first production: measure from contract signature to first approved part under ISO-aligned procedure qualification.
-
Weld cost per linear meter or per joint: incorporate energy, tooling wear, operator time and rework to compare against alternative joining methods.
-
Upskilling throughput: ratio of certified FSW operators per cell to total operators, tracking training cycle time and retention.
-
Service availability and MTTR for heads and spindles: critical for high-utilization OEM lines.
Final perspective — what PW Consulting recommends now
FSW is no longer experimental; for many high-value structural applications it is becoming the default. The 2025 market baseline and our 2032 projection provide a clear backdrop for sensible, staged investment. PW Consulting advises manufacturers and investors to prioritize supplier qualification, integrate ISO-compliant procedures early, and treat automation as both an operational and strategic lever. For industrial players that move quickly, opportunities exist across product differentiation, aftermarket services and platform consolidation.
For clients seeking executable roadmaps, our study delivers the primary datasets, vendor scorecards, CAPEX/ROI templates and scenario models necessary to convert the macro trend into quarterly milestones. Detailed subsegment tables, regional and application split analytics, and downloadable financial models are available in the full report — a necessary set of instruments for informed boardroom decisions in 2026.
For detailed analysis of this topic, please visit the official page: Friction Stir Welding Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Saw Wire Market 2026: Strategic Primer for Executive Decisions
As PW Consulting’s Chief Industry Analyst, I present a strategic preview of our Saw Wire Market study — a working compass for executives who must make decisive procurement, investment, and M&A choices in 2026. This primer synthesizes the study’s macro trajectory, the critical supply-chain and regulatory inflection points shaping supplier economics, and the competitive dynamics that will determine winners and losers across industrial, semiconductor, and construction end markets.
Saw Wire Market
Why this study matters for 2026 decision cycles
-
Macro momentum and timing: The saw wire market has demonstrated steady recovery and expansion through 2020–2025, rising from USD 163.15 million in 2020 to USD 215.0 million in 2025. Our forecast—anchored to a 2025 base year—projects continued growth into the latter half of the decade, reaching USD 344.8 million by 2032 at a compound annual growth rate (CAGR) of 6.98% for the 2026–2032 period. That growth profile elevates strategic urgency for supplier selection, capacity planning, and technology investment in 2026.
Saw Wire Market -
Risk-transferring inflection: Raw-material cost volatility, trade-policy shifts, and tightened chemical compliance are converging on an industry with thin transactional margins. Decisions made in 2026 on contracting tenor, localization, or vertical integration will materially affect cost of goods sold and lead-times through the forecast window.
Saw Wire Market -
Fragmented competitive landscape: Market concentration remains low relative to many industrial-input markets. This fragmentation creates opportunities for consolidation, premium differentiation, and targeted partnerships — but also raises execution complexity for buyers seeking assurance of supply continuity and consistent quality.
What the full report delivers — practical, decision-ready intelligence
-
Demand and supply trajectories: A granular view of historical consumption (2020–2025) and scenario-based forecasting (2026–2032), including base, upside, and downside scenarios that stress-test demand drivers such as semiconductor wafer slicing, photovoltaic feedstock, and construction/stone applications.
-
Cost-driver modeling: A transparent decomposition of unit economics showing the impact of steel-wire feedstock prices, diamond-abrasive costs, energy inputs, and labor. The model integrates recent raw-material signals and Producer Price Index movements to quantify margin exposure across supplier archetypes.
-
Regulatory and trade impact analysis: Actionable intelligence on emerging compliance requirements and trade controls — from chemical substance restrictions to export license regimes — with practical mitigation paths for procurement and regulatory teams.
-
Competitive playbooks: Company-level positioning, capability matrices, product architecture comparison, and sourcing risk heat maps for the leading saw wire providers. We combine public disclosures with primary interviews to assess manufacturability, R&D focus, after-sales support, and channel strength.
-
Procurement and commercial tools: Negotiation templates, contract clauses to hedge raw-material spikes, supplier-qualification checklists, and an ROI framework for make-versus-buy and CAPEX decisions.
-
M&A and partnership opportunities: A shortlist of acquisition targets and JV archetypes by strategic objective (market access, technology leap, or supply security), supported by valuation sensitivities and integration risk diagnostics.
Key market dynamics to watch in 2026
-
Input-cost inflation is real and measurable. Recent weeks show hot-rolled coil and steel-wire related indices trending higher, and the Producer Price Index for carbon steel wire drawing has been on an uptrend. For manufacturers whose cost base is steel- and energy-intensive, pricing pass-through and contract renegotiation will be front-and-center in 2026.
-
Regulatory tightening alters supplier risk profiles. New export-license regimes and an expanded REACH SVHC list increase compliance overheads for global suppliers. The EU’s energy-supply measures and changing trade controls can lengthen lead times and raise onshore inventory premiums.
-
End-market shifting: Semiconductor wafer slicing and high-precision industrial cutting remain primary demand engines, with specialized wire technology and consumable performance dictating procurement choices. Adjacent markets—natural stone mining and construction—are also being reshaped by portable-saw innovations targeting on-site productivity gains.
Competitive landscape — who to watch and why
The industry blends heritage engineering firms, regional manufacturers, and vertical specialists. Key participants that shape technology, service quality, and channel dynamics include:
-
Well Diamond Wire Saws SA (Switzerland) — long-standing precision focus and an emphasis on high-quality stainless steel wires and machine integration. Their brand strength is centered on durable, high-precision systems for demanding industrial slicing tasks.
-
Asahi Diamond Industrial Co. (Japan) — a major innovator in diamond-wire abrasive formulations, with strong ties to semiconductor and photovoltaic segments where slicing precision and wafer integrity are non-negotiable.
-
Noritake Co. Limited (Japan) — expertise in consumables and coating technologies for industrial sawing, with a reputation for material science depth that benefits high-throughput environments.
-
SOMOS IWT (United States) and MTI (United States) — providers with North American manufacturing footprints, servicing laboratory and industrial customers where delivery responsiveness and customization matter.
-
Husqvarna Construction (Sweden) — global distribution scale and strong presence in construction and stone, often competing on service ecosystems, rentals, and aftermarket consumables.
-
Regional specialists and OEMs (Diamond WireTec, Ensoll Tools, Princeton Scientific, Thermocompact, Wire Saw Solutions Group) — collectively represent a breadth of product forms (coils, loops, electroplated vs. sintered wires) and service models (distribution, full-service saws, aftermarket).
Strategic implications: incumbent technical leaders hold pricing power in high-spec segments (e.g., wafer slicing), while nimble regional players compete on lead time, customization, and bundled service. The low five-firm concentration underscores both acquisition opportunity and procurement complexity for OEMs and large end-users.
Recent developments and their strategic signals
-
Product launches targeted at specific use-cases (e.g., mobile saws for quarry blocks) indicate continued segmentation by application; mobility and on-site productivity are differentiators in construction and stone markets.
-
New entrants expanding into semiconductor-grade wire production suggest intensifying competition where margins and quality thresholds are highest — an area where incumbent suppliers will need to defend intellectual property and supply relationships.
Five strategic plays for 2026
-
Hedge input-cost exposure: Lock multi-year supply agreements with indexed escalators, while building optionality through geographically diversified suppliers and safety-stock corridors aligned with lead-time volatility forecasts.
-
Prioritize quality-linked sourcing for high-value segments: For wafer and precision-slicing applications, adopt supplier scorecards weighted toward material science capability, R&D pipeline, and process-control certifications rather than lowest unit price.
-
Invest selectively in vertical capabilities: Consider targeted backward integration (wire drawing, diamond-impregnation processes) where scale economics and IP control can shift margin curves over a 3–5 year horizon.
-
Mitigate regulatory and trade risk: Implement a compliance roadmap to absorb REACH and export-license changes; map single-source items that could be impacted and preregister alternative qualified suppliers.
-
Pursue bolt-on consolidation and partnerships: The market’s fragmentation creates arbitrage for platform acquirers. Focus on targets that close capability gaps (e.g., electroplating, precision spooling, or aftermarket service networks) and enable rapid scaling into adjacent geographies.
How to use this preview now
Use this primer to align your executive agenda for 2026: set procurement objectives that reflect elevated raw-material risk, initiate supplier qualification projects for high-spec product lines, and evaluate potential M&A targets using the strategic plays outlined above. For commercial teams, prioritize deals that incorporate dynamic pricing clauses and shared-cost mechanisms for inputs with volatile indices.
PW Consulting’s full Saw Wire Market report contains the granular market splits, supplier scorecards, and downloadable financial models that translate the directional insights above into executable plans. In the spirit of this “trailer,” we have deliberately withheld the detailed regional, type, and application-level percentage tables from this preview to preserve the report’s operational value and data integrity.
Next steps
-
Procurement briefing: Run a 90-day supplier risk-mitigation sprint focused on high-exposure SKUs.
-
Investment screen: Shortlist potential acquisitions and run value-capture scenarios with our M&A playbook.
-
Regulatory readiness: Convene a cross-functional task force to operationalize REACH and export-control contingencies.
For teams preparing capital allocation, supply-chain redesign, or strategic partnerships in 2026, the full PW Consulting Saw Wire Market study provides the data, tools, and playbooks to convert insight into measurable outcomes. Contact our industry practice to schedule a deep-dive briefing and obtain the forecast spreadsheets, supplier matrices, and negotiation templates referenced in this preview.
For detailed analysis of this topic, please visit the official page: Saw Wire Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: AGVs market to reach USD 382.51 Million by 2032 at 8.7% CAGR (2026-2032)
By pmarketresearch, 2026-07-08
Automated Guided Vehicles (AGVs) Market: Strategic Imperatives for 2026 Decision‑Makers
Executive snapshot
The Automated Guided Vehicles (AGVs) market is moving from early deployment to mainstream operationalization. Our PW Consulting base-year synthesis (2025) shows the global market at approximately USD 215.0 Million (base year), up from around USD 163.2 Million in 2020. With a compound annual growth rate (CAGR) of roughly 8.7% built into our 2026–2032 forecast period, the market is projected to approach the USD 380–385 Million range by 2032. This trajectory reflects a blend of accelerating AI-enabled navigation, continued warehouse automation spend, and a maturing services market for integration and lifecycle support.
Automated Guided Vehicles (AGVs) Market
Why this research matters for 2026 strategy
- Timing investments: The 8.7% CAGR and the market’s steady historical growth window signal that 2026 is a pivotal year to move from pilots to scale—delaying decisions risks higher labor, integration and retrofit costs as AGV deployments proliferate.
- Capital allocation: Our analysis translates market momentum into concrete capital planning guidance—ranked options for CapEx vs. Opex (lease, managed services), payback sensitivities, and risk buffers for component-price volatility.
- Risk management: Compliance pressure (ISO safety standards) plus tariff and supply‑chain exposures mean procurement strategies in 2026 must balance lead-time resilience with cost efficiency—this report gives board-ready scenarios to operationalize that balance.
- Competitive positioning: For OEMs, integrators and intralogistics users, the research identifies where to co-invest in software, perception stacks and service capability to capture disproportionate value as the market consolidates.
Market dynamics shaping 2026 decisions
- Labor and utilization: Persistent labor shortages in warehousing and manufacturing are the primary commercial driver for AGV adoption—buyers are shifting evaluation criteria from pure hardware cost to uptime, remote management and flexible redeployment costs.
- Safety and regulation: Compliance with ISO 3691‑4 (driverless industrial trucks) and ISO 13849 (safety performance levels) is no longer optional in industrial environments. Procurement teams must embed certification and validation checkpoints into contract milestones.
- Raw-material and component risk: Lithium‑ion batteries and high‑precision sensors dominate AGV bill‑of‑materials risk. Supply disruptions and tariff regimes are increasing the premium for secured sourcing strategies and localized manufacturing footprints.
- Energy and lifecycle efficiency: Advanced battery-management systems and induction charging are driving up to ~96% effective energy efficiency in optimized operations. Buyers should demand lifecycle energy metrics (kWh per tonne-km) as procurement criteria.
- Tariff and localization pressures: Tariffs on key components (sensors, semiconductors, batteries) are directing capital toward regional sourcing and local integration hubs—especially relevant for North America and Europe in 2026 planning.
Strategic implications — where to act in 2026
- Technology investments: Prioritize perception stacks (vision + LiDAR), edge AI for navigation, and modular software APIs. Investments that reduce integration friction with warehouse management systems (WMS) deliver the fastest ROI.
- Operating model redesign: Treat AGVs not only as capital equipment but as distributed cyber-physical systems—create cross-functional deployment squads combining operations, IT, and safety engineering for faster, safer rollouts.
- Procurement playbook: Move from a single-purchase mindset to multi-year outcome contracts that include uptime SLAs, spare parts pools, and standardized retrofit interfaces to future-proof CapEx.
- Supply-chain resilience: Implement dual-sourcing for batteries and critical sensors and evaluate nearshoring options to mitigate tariff and lead-time exposure—contractual flexibility on BOM substitutions will be indispensable.
- Service and monetization: Consider product-as-a-service models or managed automation to unlock new customers; service revenues and spare‑parts margins will be crucial differentiation as hardware margins compress.
Competitive landscape — what the leaders are signaling
The AGV competitive field combines incumbent material‑handling giants, industrial robotics specialists, and emerging AI/vision-first players. Market concentration is meaningful: the top three vendors account for a large share of revenue, with the top five commanding a substantial majority—an important context for partnerships, pricing and channel strategy.
Automated Guided Vehicles (AGVs) Market
- Daifuku Co., Ltd. (Japan) — A leader in integrated sorting and AGV systems, Daifuku is doubling down on AI-enabled navigation for complex warehouse flows. Its March 2025 launch of an enhanced AGV series emphasizes advanced obstacle detection, signaling that major suppliers are moving beyond static-path approaches.
- JBT Corporation (USA) — Known for heavy-duty, high-capacity AGVs for food & beverage and manufacturing, JBT emphasizes ruggedized 24/7 operations. Their customer base highlights the demand for uptime-centric designs in harsh environments.
- KION Group AG (Germany) — KION’s demonstration of a “Physical AI” platform shows how vendors are packaging perception, fleet orchestration and hardware optimization to claim efficiency uplifts in complex settings.
- KUKA AG & Mitsubishi Logisnext — Robotics and material handling stalwarts continue to bridge AGVs with broader automation portfolios, positioning themselves to sell integrated solutions into factory floors and intralogistics hubs.
- Toyota Industries & SSI SCHAEFER & Swisslog — These incumbents compete on proven supply-chain experience and deep WMS/ERP integration capabilities, an advantage for large legacy customers seeking low-risk transitions.
- Seegrid, Vecna, Fetch (Zebra), & Startups — Vision‑guided and AI-first vendors are pushing software-first architectures and cloud orchestration. Their agility accelerates feature innovation—buyers will have to judge trade-offs between rapid feature delivery and enterprise-grade support.
- Hyster‑Yale & Hyster Atlas — The September 2025 Hyster Atlas launch underscores how traditional lift truck OEMs are converting installed bases into automated fleets, offering an attractive pathway for customers with mixed fleets.
Recent vendor moves and what they reveal
- Product launches emphasizing AI-enabled navigation and improved obstacle detection indicate that perception and autonomy software are the primary battlegrounds for the next 24 months.
- Vendor demonstrations of platform-level efficiency gains underscore the shift from component sales to outcome-based solutions—buyers should expect commercial offers to increasingly bundle software, support and analytics.
- Strategic collaborations and modular platforms point to a future where interoperability (open APIs, standardized safety interfaces) will become a procurement requirement rather than a competitive advantage.
What the full PW Consulting report delivers (practical, board-ready tools)
- Market sizing and forecast model (interactive): Base-year harmonization (2025), five-year historical perspective, and scenario-adjustable forecasts for 2026–2032 with sensitivity to tariffs, battery prices and labor variance.
- Investment decision templates: CapEx vs. Opex comparisons, TCO calculators with energy and maintenance variables, and staged rollout cost models for greenfield vs. brownfield sites.
- Vendor evaluation framework: Scorecards for technology maturity, integration risk, service footprint, and regulatory compliance—designed for procurement to run a rapid shortlisting process.
- Deployment playbooks: Step-by-step operational checklists, validation test plans for safety standards (ISO alignment), and change-management roadmaps to minimize disruption during fleet adoption.
- Strategic scenarios and M&A lens: Playbooks for partnership strategies, bolt-on acquisition targets, and licensing opportunities across software, perception and battery management subsystems.
- Regulatory and procurement checklists: Ready-to-use clauses for safety certification milestones, spare-parts availability, and tariff-contingency pricing mechanisms.
How to use this research in 2026 — recommended next moves by stakeholder
- C-suite: Use our scenario models to set a two-year automation pipeline and a three-to-five-year capital budget that aligns with workforce strategy and sustainability targets.
- Supply‑chain leaders: Prioritize BOM risk assessments and negotiate conditional sourcing commitments for batteries and sensors to stabilize pricing.
- Operations & automation teams: Pilot AI-enabled AGVs in constrained zones first, measure kWh per throughput unit and mean time to repair (MTTR), then scale with standardized interfaces.
- Investors and M&A teams: Focus diligence on vendors with recurring service revenues, proven enterprise integrations, and defensible software moats tied to fleet orchestration.
Closing: the strategic value of a focused intelligence play
AGVs are no longer a niche automation option; they are a strategic lever reshaping fulfillment, manufacturing and intralogistics economics. For 2026 decision-makers, the most valuable intelligence is actionable and operational—precise enough to inform CapEx and procurement decisions, but structured to preserve negotiating optionality and protect competitive positioning. Our PW Consulting report supplies that intelligence: validated market sizing, scenario-ready financial tools, procurement templates and a competitive map that explains not only who leads today, but how leadership is likely to shift as software, energy and regulatory forces play out.
Automated Guided Vehicles (AGVs) Market
For the full suite of datasets, vendor scorecards, downloadable models and confidential appendices that unpack segmentation detail and deployment case studies, access the complete report on our source page. The summary above is intentionally selective—designed to give you the strategic context you need to act in 2026 while directing you to the deep intelligence required to execute with confidence.
For detailed analysis of this topic, please visit the official page: Automated Guided Vehicles (AGVs) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: BMS Market Poised to Hit USD 37.51 Billion by 2032 at 15.55% CAGR
By pmarketresearch, 2026-07-08
Battery Management System (BMS) Market — Strategic Briefing for 2026 Decision-Makers
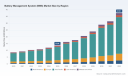
PW Consulting’s latest BMS Market study (base year 2025, historical coverage 2020–2025, forecast 2026–2032) is designed as an operative intelligence product for executives shaping strategy in 2026. The market is in a clear growth phase: total industry revenue has expanded from approximately 8.6 Billion USD in 2020 to about 13.64 Billion USD in 2025, and our forecast projects growth to 37.51 Billion USD by 2032 at a compound annual growth rate (CAGR) of roughly 15.55%. The 2026 inflection point — when sustained deployment of higher-voltage packs and expanded energy storage installations meet intensifying supply-side pressures — makes this study immediately actionable for capital allocation, product planning, and M&A activity.
Battery Management System (BMS) Market
Why this report matters for 2026 decisions
-
Timing and size: The report translates the observed historical momentum into near-term forecast scenarios that distinguish tactical moves (next 12–24 months) from structural shifts (2028+). For 2026 planning cycles, that distinction informs supply contracts, inventory strategies, and R&D prioritization.
Battery Management System (BMS) Market -
Risk-adjusted insights: We overlay commodity volatility, trade and tariff changes, and regional policy shifts onto demand trajectories to quantify downside scenarios and stress-test sourcing and production plans.
Battery Management System (BMS) Market -
Competitive positioning: Rather than merely cataloging vendors, the study maps capability clusters — OEM integrators, module-level specialists, software-first BMS providers, and test/validation toolmakers — enabling you to identify potential partners, acquisition targets, and white-space opportunities.
-
Operational playbooks: The report provides practical, board-ready recommendations for procurement, technology roadmaps, and go-to-market sequencing so that decisions made in 2026 translate to commercial advantage by 2027–2029.
Market dynamics shaping the 2026 horizon
-
Raw material volatility and upstream shocks: In 2025 and early 2026 we saw pronounced swings in lithium raw material pricing and supply constraints that materially affect cell cost and downstream BMS economics. Our analysis demonstrates how spot price moves and export controls can create localized cost inflation pockets, leading OEMs and integrators to re-price warranty assumptions or shift to revised state-of-charge management strategies that extend usable cycle life.
-
Regulatory and policy drivers: A number of fiscal and trade interventions in 2025–2026 have changed the cadence of production and export flows. Policy changes that reduce export incentives or new mineral export restrictions can prompt front-loading of shipments, altering quarterly demand and inventory cycles for BMS suppliers. The study models these effects across plausible policy permutations to inform contingency plans.
-
Technology and product evolution: Higher-current, cell-level active balancing, richer communications stacks (CAN, Ethernet, Wi-Fi/Bluetooth), and integrated thermal management are migrating from early-adopter installations into mainstream designs. This raises the technical bar for BMS suppliers and increases the value of firmware-upgradeable architectures — an area where long-term revenue streams (OTA updates, cybersecurity services) are beginning to emerge.
-
Safety, standards and certification pressure: As industrial and EV deployments scale, compliance requirements and certification regimes become decisive procurement filters. Systems that can demonstrate certified safety cases, fleet-level telemetry, and predictable de-rating behavior reduce insurer and OEM friction — a competitive advantage discussed in depth in the report.
-
System-level integration and lifecycle economics: Buyers are increasingly looking past per-unit hardware cost toward lifecycle metrics — usable cycles, BOS (balance-of-system) impacts, and second-life value. Our scenario work quantifies how modest BMS-enabled improvements in state-of-health monitoring and balancing efficiency translate into meaningful changes in total cost of ownership across different applications.
Competitive landscape — who matters and why
The market structure remains moderately fragmented; our concentration analysis shows that the three largest firms account for roughly 25% of revenue (CR3 ~25%), while the top five account for about 35% (CR5 ~35%). That profile indicates room for consolidation but also continued opportunity for specialized players to capture attractive niches.
-
Daly BMS (China) — Strengths: high-current designs, global distribution footprint, and rapid product iteration. Recent 4th Gen home energy storage platform and new portable charging offerings illustrate a playbook that pairs hardware evolution with connectivity and consumer-facing UX improvements.
-
Kuruibms (China) — Strengths: customized BMS solutions for commercial & industrial storage and EV markets. Their recent market guide and content marketing indicate a push to be perceived as a trusted supplier for bespoke OEM integrations.
-
Victron Energy (Netherlands) — Strengths: strong presence in off-grid and solar-integrated storage with proven system-level protocols (VE.Bus, Lynx). They benefit from deep inverter/system firmware integration skills and a strong installer network.
-
UgoWork (Canada) — Strengths: UL-certified BMS integrations for industrial fleets and material handling, targeting safety-sensitive deployments and fleet-scale rollouts.
-
Novelic (France) — Strengths: vehicle-focused BMS design, with emphasis on cooling integration and pack-level monitoring suitable for e-mobility OEMs.
-
comemso electronics (Germany) — Strengths: test and simulator solutions that accelerate development and validation of balancing algorithms — a critical enabler for faster time-to-market for active BMS designs.
-
Nuvation Engineering (US) & Elithion Inc. (US) — Strengths: custom engineering and embedded BMS expertise for industrial and energy storage OEMs. Their OEM/ODM capabilities make them logical partners for companies pursuing differentiated hardware + software stacks.
Recent vendor activity — product launches, documentation updates, and ecosystem compatibility statements — underscore two themes: (1) suppliers are moving to tie BMS functionality more tightly to system-level partners (inverters, chargers, and storage integrators), and (2) product-led differentiation (connectivity, firmware, and certification) is increasingly decisive. The deep profiles and recent events for these companies are summarized in the report; the decision-useful portion of our competitive analysis includes capability matrices, technology roadmaps, and a prioritized short-list of potential suppliers for different commercialization strategies.
What the report contains — practical deliverables
-
Market sizing and scenario forecasts (2026–2032) with transparent methodology, sensitivity tables and base/optimistic/pessimistic pathways to help with budget and capex planning.
-
Supplier capability maps and vendor heatmaps that score firms across design, certification, software, manufacturing scale, and service readiness.
-
Product and technology benchmarking templates, including validation test protocols, recommended KPIs for BMS performance, and firmware upgrade strategies.
-
Procurement and sourcing playbooks: contract templates, supply risk matrices, hedging strategies against raw-material swings, and suggested inventory buffers by scenario.
-
M&A and partnership screens: a prioritized list of acquisition and JV targets matched to strategic intents (vertical integration, geographic expansion, or capability acquisition) with indicative valuation frameworks.
-
Regulatory and standards tracker: a rolling register of policy changes, certification timelines, and compliance gates that affect time-to-market and cost of entry in major buyer segments.
How to use the research in 2026 — five immediate actions
-
Lock in tiered supplier agreements: Use the scenario outputs to negotiate flexible volume contracts with performance-based SLAs. Prioritize vendors with field-proven firmware-update capabilities to reduce recall risk.
-
Re-evaluate product roadmaps against cell chemistry and cost trajectories: If upstream price or availability signals suggest higher cell costs, accelerate BMS features that preserve usable capacity and extend warranty windows.
-
Invest selectively in validation infrastructure: Shorten integration cycles by adopting standardized test rigs and digital twins; vendors offering validated simulators can materially reduce development risk.
-
Pursue partnerships for system-level differentiation: Tie BMS features (energy optimization, fleet telematics, second-life controls) to value propositions that unlock recurring revenue and aftermarket services.
-
Prepare contingency playbooks for trade and supply shocks: The report’s stress tests provide trigger points to switch sourcing, prioritize regionalized capacity, or defer shipments without eroding customer trust.
Closing — why you should read the full study
The BMS market presents a rare combination of rapid top-line expansion (from mid‑single-digit billions in 2020 to multiple tens of billions by 2032) and nuanced supplier differentiation. Our study provides the quantitative forecasts and the executable guidance that translate those numbers into board-level decisions in 2026. To preserve strategic value for paying clients, this briefing intentionally omits granular segment-level allocations and detailed vendor revenue shares; the full dataset, segment splits, and supplier scorecards are available on the report landing page and include downloadable models and scenario tools that your commercial, engineering, and procurement teams can operationalize immediately.
For executives seeking to convert market growth into defensible market positions in 2026, this report is a decision-enabling toolkit: robust forecasts, supplier playbooks, and risk mitigations calibrated to the current policy and commodity environment. Access the full report to unlock the detailed segmentation, downloadable spreadsheets, and vendor diligence packages required to act with confidence.
For detailed analysis of this topic, please visit the official page: Battery Management System (BMS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Surgical Blades & Scalpels Market to Reach USD 312.3M by 2032 at 5.2% CAGR
By pmarketresearch, 2026-07-08
Surgical Blades & Scalpels Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I prepared this executive field brief to frame the strategic choices medical-device executives, hospital procurement leaders, private equity investors, and policy teams must make in 2026. The Surgical Blades & Scalpels market occupies a paradoxical position: small in absolute dollars compared with complex implants, yet tightly coupled to surgical throughput, patient safety programs, and perioperative economics. This briefing synthesizes our market sizing, growth trajectory, regulatory context, competitive dynamics, and pragmatic go-to-market options — enough to orient high-stakes decisions while preserving the granular tables, model outputs, and segmentation breakdowns that you will find in the full report.
Surgical Blades & Scalpels Market
Market Snapshot: Scale, Growth and Momentum
In our base-year view (2025) the global Surgical Blades & Scalpels market reached approximately USD 219.8 Million, reflecting steady expansion from the early-2020s. Our historical model captures the post‑pandemic rebound in elective surgery volumes and incremental product upgrades across sterile single-use platforms. Looking forward, we forecast the market to grow at a compound annual growth rate (CAGR) of 5.2% across the 2026–2032 planning horizon, reaching a mid‑to‑high three‑hundred million dollar range by the end of the forecast period. This trajectory reflects a mix of steady unit demand driven by procedural volumes and selective value migration toward premium safety and micro‑precision blades.
Surgical Blades & Scalpels Market
Why the Market Matters for 2026 Strategic Choices
- Procurement optimization: With blades accounted for inside bundled surgical fees rather than reimbursed separately, hospital systems must pursue total cost of ownership and sharps‑injury reduction metrics rather than unit price alone.
- Product portfolio prioritization: Manufacturers need to balance low‑margin, high‑volume disposable products with niche, higher‑margin offerings (e.g., micro and ophthalmic blades, safety scalpel systems) and services such as sterilization and kit integration.
- M&A and partnership timing: Modest overall market growth but strong consolidation dynamics make 2026 a window for bolt‑on acquisitions, distribution alliances, and capacity plays that add sterilization or regulatory depth.
- Regulatory and compliance risk: Evolving single‑use validation standards and workplace safety regulations alter procurement drivers and create demand for certified safety scalpel lines.
Key Market Dynamics — What’s Driving Change
- Safety and worker protection: Enforcement of occupational safety legislation and standards is accelerating adoption of single‑use sterile and engineered safety scalpels to reduce sharps injuries. This is a structural tailwind for disposable and safety‑oriented SKUs.
- Regulatory clarity with pragmatic implications: In primary markets, basic scalpel products remain classified in lower device classes with reduced premarket burdens, which keeps barriers to entry relatively modest. However, higher scrutiny on sterilization validation, ISO 13485 facility certification, and EU medical-device regulations means manufacturers exporting to regulated markets must maintain disciplined quality systems and documentation.
- Reimbursement and purchasing behavior: Because blades are integrated into surgical episode payments — not itemized with dedicated codes — buyers focus on net procedural economics and risk mitigation. Devices that demonstrably reduce OR time, reduce reprocessing costs, or lower sharps incidents gain disproportionate commercial leverage.
- Technology and specialization: Advances in micro‑blade metallurgy and laser‑assisted cutting solutions are extending product differentiation beyond commodity steel. At the same time, specialization in dental, ophthalmic, and micro‑surgery niches creates defensible margins for focused players.
- Supply chain and geopolitics: Manufacturing clusters in East Asia and Europe continue to supply global demand. 2026 decisions must account for sterilization capacity, certification timelines, lead‑time exposure, and dual‑sourcing strategies for critical consumables.
Commercial Implications — How to Compete in 2026
Given modest overall growth but meaningful opportunity to extract value via differentiation, companies should align to one of three pragmatic plays:
Surgical Blades & Scalpels Market
- Commodity scale and cost leadership: Invest in high‑efficiency production, verticalized sterilization, and optimized global distribution to serve high‑volume hospital systems and low‑cost markets. Margin resilience depends on operational excellence and predictable supply.
- Premium safety and integrated solutions: Bundle safety scalpels with training, sharps‑disposal solutions, and OR workflow analytics to shift purchasing conversations from price to risk and total cost.
- Niche precision specialization: Focus on ophthalmic, micro‑surgery, or dental subsegments where micro‑blade sharpness, tolerances, and brand reputation command pricing power and clinical preference.
Competitive Landscape — Who Moves Markets
The competitive field comprises established heritage manufacturers, regional scale producers, and specialized niche suppliers. The market demonstrates discernible concentration among the leading vendors, creating both barriers and buyout opportunities for challengers. Key company archetypes and strategic postures we analyze in the full report include:
- Heritage precision leaders: Longstanding specialists with deep blades‑manufacturing expertise and strong global brands that command clinical trust in general surgery and precision applications. Their advantages lie in brand equity, clinician relationships, and long product catalogs.
- North American commercial scale players: Companies focused on hospital and ASC channels that combine domestic manufacturing, regulatory experience, and broad distribution networks — attractive targets for distribution deals and channel expansions (for example, recent strategic distribution moves in 2025 show how manufacturers accelerate footprint via local partners).
- Japanese precision and micro‑blade innovators: High‑quality stainless‑steel and micro‑blade suppliers who win in applications requiring extreme sharpness and consistency, often commanding premium pricing.
- Large diversified medical OEMs: Corporates embedding blades into broader perioperative portfolios to deliver integrated kits and bundled supply contracts, shifting procurement conversations toward system-level value.
- High‑volume Asian manufacturers: Cost‑competitive producers supplying disposable sterile blades at scale to global distribution channels, often thriving where cost and availability are primary selection criteria.
We profile each major competitor in the full briefing, including their product focus, geographic strengths, recent commercial developments, and implied strategic playbooks. Notably, recent distribution agreements and channel realignments in 2025 highlight how manufacturers are accelerating market access without heavy capital expenditure.
Regulatory and Reimbursement Touchpoints — Practical Impacts
- Device classification and market entry: Many scalpel and blade variants remain in lower device classes with exempted premarket pathways in primary markets — simplifying registration but not obviating GMP and quality‑system diligence.
- Occupational safety standards: OSHA and international standards that mandate or incentivize safety scalpel use materially shift demand dynamics inside hospital procurement committees.
- Reimbursement framing: Absence of discrete reimbursement lines means suppliers must quantify value in operational terms (OR efficiency, incident reduction, sterilization avoidance) to capture premium pricing.
- Quality assurance: ISO 13485 certification and strict single‑use validation under advanced regulatory regimes are table stakes for sustained access to high‑value markets.
Supply Chain & Manufacturing Considerations
Surgical blades are not technologically complex, but supply reliability depends on metallurgical sourcing, precision stamping/grinding, and validated sterilization. In 2026, buyers will prioritize vendors with proven multi‑regional capacity, traceable material chains, and rapid scalability for elective surgery rebounds. Investments in regional sterilization hubs, validated single‑use production lines, and serialization for traceability will create competitive differentiation and cost predictability for key customers.
What the Full PW Consulting Report Contains
The complete market study delivers the decision-grade assets leaders need in 2026:
- An audited market size model (2020–2025 historical, 2026–2032 forecast) with scenario analysis driven by procedural volume, product mix shifts, and pricing elasticity.
- Segmented forecasts by product type, application, and geographic region with sensitivity tables and growth-drivers mapping (segmentation granularity is included in the full report).
- Competitive heatmaps and strategic profiles for major firms, with capability assessments, revenue mix indicators, and acquisition targets.
- Commercial playbooks: pricing frameworks, procurement scorecards, tender checklists, and OR value calculators that buyers and sellers can apply immediately.
- Supply chain risk matrix and manufacturing investment checklist — including sterilization capacity, certification timelines, and dual‑sourcing playbooks.
- M&A and partnership advisor tools: target screening criteria, valuation multiples benchmarks in adjacent consumable markets, and integration checklists.
- A regulation and compliance appendix defining certification requirements, workplace safety drivers, and a timeline of recent policy developments that directly influence adoption.
How to Use This Intelligence in 2026 — Practical Next Steps
- For manufacturers: prioritize investments that shift procurement conversations away from unit price (safety, TCO, kit integration); accelerate ISO and MDR readiness where relevant.
- For hospital systems and group purchasing organizations: deploy supplier scorecards that weight sharps‑injury outcomes and sterilization avoidance alongside price; consider multi‑year partnerships tied to OR efficiency KPIs.
- For investors: target bolt‑on acquisitions that add sterilization capacity, niche micro‑blade IP, or regional distribution reach; emphasize targets with quality systems already aligned to regulated-market requirements.
- For regulators and policy teams: use the market’s structural characteristics to calibrate guidance that balances clinician access, workplace safety, and device quality assurance.
Closing — The Strategic Value of the PW Consulting Report
By 2026, decisions in the Surgical Blades & Scalpels market will hinge less on whether unit demand grows and more on who can convert modest market growth into durable margin expansion through differentiation, service, and regulatory excellence. Our report combines a data‑backed macro view, rigorous segmentation, and hands‑on commercial playbooks to translate that modest CAGR and steady market expansion into executable strategies.
This briefing is intentionally directional — offering the context and frameworks you need while preserving the detailed models, segmentation tables, and company scorecards available in the full PW Consulting study. For the complete dataset, downloadable models, and bespoke advisory support tailored to your business questions in 2026, please consult the full report and contact our team.
For detailed analysis of this topic, please visit the official page: Surgical Blades & Scalpels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fire Doors Market Insights — 4.2% CAGR Forecast (2026–2032)
By pmarketresearch, 2026-07-08
Fire Doors Market — Strategic Briefing for 2026 Decision Makers
PW Consulting’s latest Fire Doors Market study (base year 2025; historical window 2020–2025; forecast horizon 2026–2032) translates a complex product-and-compliance ecosystem into a practical playbook for executives, investors, and procurement leaders preparing to act in 2026. The report synthesizes macro demand trajectories, regulatory inflection points, supply-chain constraints and competitive dynamics so you can prioritize investments with conviction. At the highest level: the global market is expanding at a steady compound annual growth rate (CAGR) of 4.2%, moving from a mid‑single‑digit billion USD opportunity in 2025 toward a substantially larger installed base by 2032 (values reported in USD Million). This growth masks uneven pockets of opportunity and risk — exactly the kind of nuance that separates transactional choices from strategic moves.
Fire Doors Market
Why this research matters in 2026
-
Regulatory momentum has created a hard deadline for capabilities. The 2025 edition of NFPA 80 increases inspection cadence and introduces performance‑based options that materially affect aftermarket services, compliance audits, and product documentation demands. Simultaneously, an updated UL 10C revision (effective 2026) tightens hardware requirements for locks and latches — driving both product redesign and upgraded test plans.
Fire Doors Market -
Certification and testing are now system-level constraints. Leading standards bodies and accreditation requirements emphasize full‑assembly testing (door leaf, frame, hardware, seals, glazing) under ISO/IEC 17025‑compatible regimes. Firms that treat certification as a cost center will find themselves outpaced by those that integrate testing into product development and commercial service offers.
Fire Doors Market -
The market’s structural profile favors specialization and service differentiation. Measured concentration is low: top-three and top-five shares are modest, indicating fragmentation and a long tail of regional suppliers. For buyers and investors this creates both sourcing complexity and M&A optionality.
Macro snapshot (strategic takeaways)
-
Steady expansion. The market recorded consistent growth through 2020–2025 and is projected to continue through the 2026–2032 forecast window at a 4.2% CAGR. This trajectory supports capacity investments, but the returns are highly sensitive to product mix, standards compliance and aftermarket penetration.
-
Regulation as a demand-shaper. The new NFPA 80 and UL updates function as quasi-demand drivers for inspection, retrofitting and replacement cycles. Organizations that can bundle compliant hardware with inspection and maintenance services will capture outsized margins.
-
Fragmentation equals opportunity. Low market concentration creates space for consolidation plays, regional scale-ups, and specialist platform strategies (e.g., vertical integration of testing, installation and field services).
Competitive landscape — what the leading players signal
The market features a mix of global platform incumbents, specialist manufacturers, and regional producers. Recent strategic moves reveal three dominant themes:
-
Consolidation to broaden product-and-service scope: Major platform players are actively acquiring adjacent capabilities — from hardware specialists to service networks — to secure end‑to‑end control of compliant door ecosystems.
-
Product innovation focused on operability and compliance: New low‑energy door assistants and hardware designed to meet the 2026 UL requirements are being introduced, signaling competition around usability without compromising fire performance.
-
Service and aftermarket as margin pools: Acquisitions of fire‑safety service providers reflect a bet that inspection, maintenance and certification services will be durable cash flows as regulatory scrutiny rises.
Representative strategic moves include high‑profile acquisitions and product launches that highlight where incumbents are placing their chips. You should view these moves as directional indicators rather than exhaustive company valuations — they clarify where value is migrating (service networks, certification, product systems) and where competition will intensify (hardware and integrated assemblies).
Practical contents of the PW Consulting report
Our research is designed to be operationally actionable for leaders making capital allocation, product development, channel and M&A decisions in 2026. The deliverables include:
-
Market sizing and seven‑year forecasts (2026–2032) at the total market level, with scenario models that allow you to stress-test outcomes against regulatory and raw‑material shocks.
-
Demand-driver analysis including construction starts, retrofit cycles, regulatory enforcement intensity and public‑sector procurement triggers.
-
Supply‑chain mapping that highlights single‑sourcing risks, certification bottlenecks, and logistics exposures for critical inputs and pre‑assembled systems.
-
Commercial playbooks: go‑to‑market strategies for OEMs, distributors and system integrators; tender and pricing templates for large institutional buyers; and customer segmentation models for aftermarket service monetization.
-
Compliance and testing roadmap showing how to convert new regulatory requirements (e.g., NFPA 80 2025, UL 10C 2026) into product roadmaps and service offerings that minimize time‑to‑market risk.
-
Opportunity scanner for M&A and partnerships, highlighting target archetypes (service providers, hardware specialists, certified assembly manufacturers) and high‑leverage integration levers.
Key strategic recommendations for 2026
-
Prioritize certification‑first engineering. Treat full‑assembly testing and ISO/IEC 17025‑aligned labs not as compliance overhead but as growth enablers. Investing in or partnering with accredited test facilities reduces time‑to‑market friction and creates an entry barrier for lower‑quality alternatives.
-
Monetize service intensity. With NFPA 80 mandating post‑installation inspections and minimum periodic checks, build recurring revenue models around inspection, maintenance and digital lifecycle management. Bundled hardware+service contracts will command premium pricing and higher lifetime value.
-
Design for hardware resilience. UL 10C revisions sharpen the focus on locks, latches and security. Re‑engineer product specifications to meet the new thresholds and use compliance as a commercial differentiator in tenders for institutional customers.
-
Adopt a hybrid scale‑and‑specialist M&A strategy. Given low market concentration, there’s room for roll‑ups of regional manufacturers and services. Target acquisitions that provide field capacity or certification capabilities rather than solely product SKUs.
-
Localize critical supply chains. Countries introducing mandatory national certification (for example, tighter enforcement of local standards) increase demand for locally produced, certified assemblies — this favors firms that combine manufacturing scale with local compliance footprints.
-
Digitize inspection and warranty processes. Invest in IoT‑enabled sensors, inspection workflow software and centralized certification repositories to shorten audit cycles, reduce liability and create upsell pathways for predictive maintenance.
Risks and mitigants
-
Regulatory enforcement variability: Differences in enforcement intensity across jurisdictions can create short-term demand volatility. Mitigate by designing modular compliance packages that can be adapted to regional inspection regimes.
-
Certification bottlenecks: Laboratory capacity constraints can delay product launches. De‑risk by pre‑booking test slots, co-investing in accredited labs, or using recognized third‑party certification partners.
-
Price pressure from large local manufacturers: High‑volume producers may undercut on commodity doors. Compete with services, compliance guarantees and higher‑margin system assemblies.
How leaders should use this analysis in 2026
Executives should treat the report as a decision‑support toolkit: use the scenario models to size capital expenditures, apply the compliance roadmap to de‑risk product introductions, and deploy the M&A scanner to prioritize targets that accelerate service capabilities. For investors, the fragmentation offers a clear playbook — back platforms that can execute roll‑up strategies focused on certified assembly, field services, and digital inspection assets.
Next steps — what the full report delivers (and what we intentionally withheld)
To preserve strategic leverage for our clients and to follow the “trailer” principle of this briefing, we have intentionally withheld granular segment‑level figures and certain region/application splits from this introduction. The full PW Consulting Fire Doors Market report contains:
-
Detailed segment-level forecasts by material, application and region (with scenario toggles).
-
Competitive profiles with relative market positioning and private benchmarking data.
-
Transaction comps, valuation ranges for roll‑up targets, and an M&A integration checklist tailored to fire‑door assemblies and services.
-
Practical templates (tender language, OEM‑installer SLAs, inspection checklists) that you can deploy within 90 days of acquisition.
For teams making capital allocation and operational choices in 2026, the choice is straightforward: follow the report’s compliance‑driven, service‑led framework to convert regulatory change into sustainable revenue streams. PW Consulting’s full study provides the granular maps and models required to execute — from product redesign to M&A prioritization and commercial roll‑out.
Contact
Access the full analysis and supporting datasets through the PW Consulting portal to obtain the segmental forecasts, company valuations and deployment templates that will enable decisive action in 2026.
For detailed analysis of this topic, please visit the official page: Fire Doors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cryocoolers Market to Reach USD 344.8M by 2032 at 6.98% CAGR
By pmarketresearch, 2026-07-08
Cryocoolers Market 2026: Strategic Insights for Executive Decision-Making
Executive summary
As organizations across defense, space, medical imaging, quantum technologies, and industrial gas systems plan capital allocation and product roadmaps for 2026, cryocoolers are transitioning from niche enabling components to strategic system-level differentiators. PW Consulting’s latest study (base year 2025, historical 2020–2025, forecast 2026–2032) synthesizes market dynamics, regulatory shifts, supplier positioning, and technology trajectories into an operational playbook for leadership teams. The global cryocoolers market has expanded materially from 2020 to 2025 and—growing at a compound annual growth rate (CAGR) of 6.98%—is forecast to continue through 2032, reflecting accelerating demand from quantum, space, and defense programs.
Cryocoolers Market
Why this report matters to 2026 decision-makers
- Timing: 2026 is a pivotal year for procurement, certification, and supplier consolidation decisions. Several large programs (defense night-vision upgrades, satellite constellations, and quantum commercialization pilots) require procurement commitments or design freezes this year.
- Risk management: New export-controls and testing requirements introduced between 2024–2026 increase compliance complexity and supplier due-diligence burdens for global programs.
- Investment focus: R&D and capex choices made in 2026 will determine who captures the higher-value system integrations emerging by the early 2030s—particularly for long-duration space cryogenic storage and low-vibration quantum cryocoolers.
- Supplier strategy: The market remains fragmented (CR3 ≈ 24.6%; CR5 ≈ 26.2%), which creates opportunities for both large integrators and nimble specialists to scale through targeted partnerships or M&A. Our research maps the commercial levers to exploit this fragmentation.
Market trajectory — a concise data-driven view
PW Consulting’s topline metrics provide a clear frame for strategic planning: the global cryocoolers market increased steadily from 2020 into 2025, and with the base year set at 2025 our forecast extends through 2032 under a mid-cycle scenario (CAGR 6.98%). This trajectory reflects a convergence of drivers—expanded satellite and ISR payloads, quantum-computing deployments, and broader industrial and energy uses—that are reshaping demand profiles and unit economics. While we disclose the aggregate market path in this preview, detailed segment and regional splits are intentionally withheld here to preserve the report’s role as the definitive commercial reference.
Cryocoolers Market
What the full PW Consulting study contains (practical, actionable content)
- Market sizing and forecasting model (base year 2025, historical coverage 2020–2025, forecast 2026–2032) with downloadable scenario files and sensitivity levers for price, adoption, and substitution.
- Demand-driver deep dives: satellite payload schedules, defense procurement cycles, quantum and superconducting use-cases, medical imaging replacement timelines, and industrial gas/liquefaction projects.
- Regulatory & export-control matrix: program-level compliance impacts, national control lists, and practical steps for dual-use supply chains (updated to reflect 2024–2026 rule changes).
- Supplier benchmarking toolkit: capability maps, product-readiness matrices (TRL mapping), and procurement scorecards to accelerate vendor selection and risk mitigation.
- Commercial playbooks: go-to-market options by buyer archetype (prime integrator, OEM, national lab, commercial quantum provider) including pricing and service models that preserve margin while enabling adoption.
- M&A and partnership blueprint: prioritized target lists, valuation comparables, and integration checklists for acquiring complementary cryocooler technologies or manufacturing capacity.
- R&D and product roadmap templates: low-vibration, high-uptime, and low-mass architectures; cooling-power tradeoffs; and quick-win design modifications to shorten qualification cycles.
- Supply-chain resilience planning: critical-buoy component lists, alternate sourcing strategies, inventory sizing guidelines, and nearshoring scenario analysis keyed to regulatory constraints.
- Executive dashboards and decision-support worksheets: cash-flow impacts, TCO calculators, and scenario-based NPV comparisons for strategic investment options.
Competitive landscape — who matters and why
The cryocooler ecosystem mixes long-established industrial players, defense primes, and specialized innovators. Rather than a winner-takes-all market, the current structure rewards technology depth, systems-integration capability, and supply-chain resilience.
Cryocoolers Market
- Sumitomo Heavy Industries (Tokyo) — broad portfolio strength across Gifford-McMahon and pulse-tube families for space, medical imaging, and defense. Their strategy emphasizes high-capacity, lower-maintenance designs that play well into long-duration missions.
- Northrop Grumman (Washington, DC) — leverages systems-integration expertise to embed custom Stirling and pulse-tube units in satellite and sensor payloads. Their competitive edge is integration and mission assurance at prime-contractor scale.
- AMETEK / Sunpower (Waltham) — focuses on Stirling technology optimized for low vibration and maintenance-free operation, attractive for aerospace and sensitive instrumentation.
- Chart Industries (Boulder) — industrial cryogenics specialist; its strength is in scale for gas liquefaction and energy applications where system-level cryogenic management is the differentiator.
- Bluefors (Helsinki) & Cryomech (Syracuse) — pulse-tube leaders targeting quantum and superconducting detector markets with compact, high-performance designs; high-growth adjacency as quantum commercialization matures.
- RICOR, AIM Infrarot-Module, RIX Industries, Stirling Cryogenics — niche specialists in miniature Stirling and premium infrared detector coolers; critical suppliers for defense IR and scientific instrumentation.
- Thales, L3Harris — defense and aerospace primes integrating cryocoolers into night-vision, ISR, and space systems. Their primary moat is system-level certification and secured program flows.
- Air Liquide, Advanced Research Systems, Lake Shore, Superconductor Technologies — combine component-level expertise with downstream system services, especially for research and industrial customers.
Collectively, the market’s low concentration metrics indicate opportunity: large primes can differentiate through integration and service offerings, while specialists can scale by carving application-led niches or partnering with OEM integrators.
Regulatory and technology dynamics to watch in 2026
- Export controls: Recent national controls (e.g., updates in 2024–2026) have added complexity to cross-border supply chains and technology transfers. Buyers and sellers must incorporate export classification and licensing timelines into procurement gates.
- Technology readiness requirements: Programs such as NASA’s CACHE initiative are pushing high-capacity cryocooler TRL thresholds for space cryogenic storage—this raises the bar for vendors seeking inclusion in long-duration mission bids.
- Conference and knowledge flows: Industry forums (notably the June 2026 International Cryocooler Conference) will accelerate transparency on performance benchmarks and integration learnings—attendance and targeted sponsorships are high-ROI activities for market entrants.
- Product innovation: Recent product launches signal performance inflection points—compact two-stage pulse-tube systems for superconducting detectors and whisper-quiet, higher-capacity single-stage units for space and defense. These design advances change system architecture decisions and lifecycle cost profiles.
Strategic moves for executives in 2026 (prioritized)
- Immediate (0–6 months) : Incorporate export-control gating into all procurement and partnership contracts; run a rapid supplier compliance audit to identify potential license needs and contingency suppliers.
- Near-term (6–12 months) : Adopt the PW scenario model to test procurement vs. in-house development trade-offs for high-volume programs; prioritize vendor scorecards that include TRL, spares lead time, and proven integration experience.
- Medium-term (12–24 months) : Form strategic partnerships with pulse-tube and Stirling specialists to co-develop low-vibration and high-life-cycle products tailored to your system requirements—focus on IP-sharing arrangements that preserve optionality.
- Portfolio strategy : For investors and corporate development teams, target tuck-ins that add cryocooler miniaturization or thermal-storage capability; valuation discipline should factor in long qualification cycles and export uncertainty.
- Operational resilience : Rebalance inventories of critical components, invest in dual-sourcing for high-vulnerability subassemblies, and evaluate nearshoring options where regulatory risks are material.
- Talent & R&D : Hire systems engineers with cryogenics integration experience and seed focused R&D on vibration mitigation and mean-time-between-failure (MTBF) improvements—small performance gains translate to outsized system-level advantages.
How PW Consulting’s deliverables support execution
- Customizable financial models and procurement templates to compress vendor selection timelines from months to weeks.
- Operational checklists for export compliance and supplier audits aligned to the latest 2024–2026 regulatory changes.
- M&A diligence packs and integration plans that reflect cryocooler-specific certification and qualification timelines.
- Workshops and executive briefings to cascade findings into program planning and R&D prioritization.
Closing — a trailer, not the full film
This briefing is deliberately selective. It communicates the market’s direction, the regulatory headwinds, the competitive topology, and the practical strategic moves that should be on every executive’s 2026 agenda—while withholding the granular regional, type, and application splits that underpin our proprietary valuation and vendor-ranking models. PW Consulting’s complete Cryocoolers Market report contains those detailed breakdowns, downloadable models, and supplier scorecards essential for transaction-level decisions. For clients preparing procurement specifications, investment memoranda, or program roadmaps in 2026, the full study converts market insight into executable advantage.
To access the full dataset, scenario models, and supplier benchmarking tools, please visit our report page or contact PW Consulting’s team for a tailored executive briefing and model walkthrough.
For detailed analysis of this topic, please visit the official page: Cryocoolers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aerospace Materials Market to Hit USD 55,327M by 2032 at 8.2% CAGR
By pmarketresearch, 2026-07-08
Aerospace Materials Market 2026: Strategic Imperatives from PW Consulting
As the aerospace industry accelerates into its next chapter of fleet modernization, sustainability mandates, and supply-chain recalibration, materials strategy has become a primary axis of competitive differentiation. PW Consulting’s latest Aerospace Materials Market briefing—anchored on a 2025 base year and a 2026–2032 forecast horizon—translates market-scale dynamics into executable choices for executives planning capital allocation, sourcing, product strategy, and M&A in 2026.
Aerospace Materials Market
Executive snapshot: why this report matters for 2026 decision cycles
-
Market trajectory is robust: the global aerospace materials market grew from roughly USD 25.5 billion in 2020 to about USD 32.0 billion in 2025 and is projected to continue expanding at a compound annual growth rate of approximately 8.2% through the 2026–2032 forecast window, approaching the mid‑fifties (USD 55+ billion) by 2032.
Aerospace Materials Market -
Concentration and opportunity coexist: the market shows a moderate level of supplier consolidation, with the top three and top five players accounting for meaningful—but not overwhelming—shares. That structure favors strategic alliances, bolt‑on acquisitions, and targeted capacity investments alongside discipline from established leaders.
Aerospace Materials Market -
Timing matters: 2026 is the inflection year for several interlocking trends—thermoplastic commercialization, certification fast‑tracks, upstream supply disruptions, and tariff/regulatory impacts—making near‑term strategic moves disproportionately impactful over a seven‑year investment horizon.
Understanding the macro picture — what the headline numbers conceal
High‑level growth is necessary but not sufficient for strategy. The headline CAGR and market-size trajectory indicate a materially expanding addressable market for advanced aluminum alloys, carbon and glass fiber composites, titanium and nickel superalloys, and high‑performance thermoplastics. Yet beneath that headline lies divergence in growth drivers (commercial airframe platforms, defense modernization, rotorcraft niche programs, and aftermarket repair & overhaul flows), as well as variability in raw material availability and regulatory treatment across jurisdictions. Our full study preserves the headline figures while deliberately keeping granular segment tables gated—this is by design to ensure critical, actionable segmentation remains a conversion point for leaders seeking the full intelligence package.
Dynamics reshaping supplier economics and risk in 2026
-
Raw material cost volatility: PAN‑based carbon fiber precursor and acrylonitrile feedstock experienced upstream cost pressure in late 2025 and into Q1 2026, producing short‑term price steps and compression on margin for commodity grade suppliers. Procurement teams must assume episodic feedstock shocks and model scenarios for 3–5% price variance to stress test supplier contracts and hedging approaches.
-
Regulatory and trade friction: 2025–2026 brought new trade measures and stricter environmental permitting in several advanced manufacturing geographies, along with targeted tariffs on specific carbon fiber imports. These developments raise compliance costs, accelerate reshoring incentives, and make geographic footprint decisions for capacity expansion much more strategic than purely cost‑driven calculations.
-
Certification and time-to‑market: regulatory bodies moved to streamline certification for established alloys and composite systems, lowering the barrier for scaled adoption of proven materials. At the same time, early‑mover advantage remains critical for novel thermoplastics and PAEK variants that promise manufacturing throughput gains.
-
Manufacturing automation and materials substitution: next‑generation aircraft programs are shifting design and production paradigms toward larger monolithic composite structures, thermoplastic solutions for interiors and some primary components, and integrated automated layup. These trends favor suppliers able to combine material R&D with process innovation and digital twins for performance validation.
Competitive landscape — what to watch among leading players
The market is anchored by a set of established materials houses and specialty chemical firms that combine raw material production with composite system integration. Several themes emerge from our competitive review:
-
Vertical integration and system play. Firms traditionally focused on carbon fiber precursors and reinforcements are expanding into prepregs, resin systems, and even part-level certifications. This broadening of scope reduces OEM dependence on fragmented suppliers and increases barriers to entry for pureplay newcomers.
-
Capacity and geographic strategy. Multiple incumbent producers are executing capacity expansions in key geographies to secure long‑lead feedstock and to mitigate tariff exposure and logistics risk. New capacity announcements should be read alongside permitting timelines and qualification schedules rather than as pure production metrics.
-
Thermoplastics and high‑performance polymers gaining share. Companies investing in PAEK/PEEK platforms and high‑temperature thermoplastics are placing strategic bets on faster cycle times, recyclability, and repairability—attributes increasingly valued by airframers pursuing lifecycle cost reduction and sustainability targets.
-
Certification and qualification as a commercial moat. Achieving type‑approval pathways, FAA recognition, and NCAMP qualifications materially accelerates adoption curves. Suppliers that can bring both material innovation and documented certification pathways will outcompete those offering only raw inputs.
Representative company activity underscores these themes. Market leaders with deep carbon fiber and composite portfolios continue to showcase automated manufacturing systems and lightweight structural solutions at major airshows. Japan‑ and Europe‑based incumbents are expanding production and commercializing advanced braided fabrics and thermoplastic matrices. Certification wins for resin systems and full commercial availability of advanced thermoplastic granules have moved several players from pilot production to mainstream supply. For procurement and strategy teams, the practical implication is clear: partner selection must account for product roadmaps, qualification status, and production footprint, not only unit price.
Strategic implications and recommended actions for 2026
-
For OEMs and Tier‑1s: adopt a dual‑track sourcing strategy. Lock in long‑term agreements with qualified, capacity‑secure suppliers while maintaining small, flexible trials with innovative material providers that can deliver lifecycle cost or weight advantages. Prioritize suppliers with demonstrable certification progress and in‑region production to de‑risk tariffs and logistics.
-
For material suppliers: prioritize qualification programs and scalable manufacturing. Investments that shorten certification timelines and increase throughput—automation, predictive quality, and digital material passports—deliver disproportionate commercial returns. Consider selective vertical moves (e.g., resin systems, prepregs) to capture additional margin and strategic relevance to OEMs.
-
For investors and M&A teams: look for bolt‑on plays that add certification horsepower, regional capacity, or proprietary thermoplastic formulations. The market’s moderate concentration means well‑timed acquisitions can significantly alter competitive positioning, especially when combined with operational excellence programs to address upstream feedstock volatility.
-
For procurement and supply‑chain leaders: build feedstock contingency and tax/regulatory scenario plans into 2026 budgets. Hedging, multi‑sourcing, and collaborative supplier investment (e.g., co‑funded capacity expansions) will be essential to cushion short‑term raw‑material shocks while securing long‑term cost visibility.
-
For R&D and product teams: align material selection to manufacturability and lifecycle metrics. Prioritize materials that reduce total cost of ownership—considering repairability, recyclability, and certification burden—over element-wise BOM cost savings.
What the PW Consulting report delivers (practical, executable content)
Our full study provides an end‑to‑end toolkit for 2026 planning cycles, including:
-
Forward‑looking demand scenarios and sensitivity analyses that translate program decisions (airframe mix, defense budgets, aftermarket recovery rates) into material demand and pricing implications for the 2026–2032 window.
-
A rigorous competitive benchmarking suite that maps product portfolios, certification status, global footprints, and recent strategic moves of the leading suppliers—enabling rapid shortlisting for procurement pilots or M&A screening.
-
Operational playbooks for suppliers and OEMs: qualification roadmaps, sample contract language for capacity commitments, and a checklist for integrating automation and digitalization in composite production lines.
-
Risk matrices and mitigation frameworks covering feedstock shocks, regulatory shifts, and trade measures—plus modeled P&L impacts under multiple raw‑material and tariff scenarios.
-
Actionable implementation calendars that sequence certification milestones, capacity investments, and procurement decisions to align with airframe program timelines and regulatory windows.
To preserve the commercial utility of this intelligence and to honor proprietary supplier data, our public introduction intentionally omits gated segment tables and location‑level demand schedules. These high‑value matrices and model files are included in the full report and client dashboards.
Final takeaway — the strategic question for 2026
As the market grows and diversifies, the single biggest strategic question for leadership teams is not whether materials matter—they do—but how to balance near‑term stability with long‑term advantage. Do you secure capacity and manage price volatility through conservative contracting, or do you invest aggressively in qualifying novel materials and manufacturing processes that could rebase lifecycle cost and environmental performance? The right answer will likely be both: protect core programs while creating optionality through targeted pilots, partnership investments, and qualification pipelines.
PW Consulting’s Aerospace Materials Market study converts that strategic dilemma into a prioritized set of actions keyed to the 2026 decision calendar. For procurement heads, corporate strategists, R&D leaders, and investors preparing for the next wave of airframe programs, the full report provides the granular segmentation, supplier scorecards, and scenario models necessary to move from hypothesis to executable plan.
Next step
Access to the full dataset, supplier models, and implementation checklists is available through our report portal. For a custom briefing tailored to your program timelines, supplier roster, or M&A appetite, contact PW Consulting to schedule a 2026 strategic workshop.
For detailed analysis of this topic, please visit the official page: Aerospace Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com