

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Aerospace Materials Market to Hit USD 55,327M by 2032 at 8.2% CAGR

Aerospace Materials Market 2026: Strategic Imperatives from PW Consulting
As the aerospace industry accelerates into its next chapter of fleet modernization, sustainability mandates, and supply-chain recalibration, materials strategy has become a primary axis of competitive differentiation. PW Consulting’s latest Aerospace Materials Market briefing—anchored on a 2025 base year and a 2026–2032 forecast horizon—translates market-scale dynamics into executable choices for executives planning capital allocation, sourcing, product strategy, and M&A in 2026.
Aerospace Materials Market
Executive snapshot: why this report matters for 2026 decision cycles
-
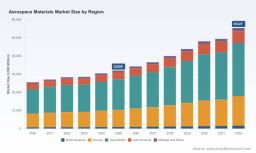
Market trajectory is robust: the global aerospace materials market grew from roughly USD 25.5 billion in 2020 to about USD 32.0 billion in 2025 and is projected to continue expanding at a compound annual growth rate of approximately 8.2% through the 2026–2032 forecast window, approaching the mid‑fifties (USD 55+ billion) by 2032.
Aerospace Materials Market -
Concentration and opportunity coexist: the market shows a moderate level of supplier consolidation, with the top three and top five players accounting for meaningful—but not overwhelming—shares. That structure favors strategic alliances, bolt‑on acquisitions, and targeted capacity investments alongside discipline from established leaders.
Aerospace Materials Market -
Timing matters: 2026 is the inflection year for several interlocking trends—thermoplastic commercialization, certification fast‑tracks, upstream supply disruptions, and tariff/regulatory impacts—making near‑term strategic moves disproportionately impactful over a seven‑year investment horizon.
Understanding the macro picture — what the headline numbers conceal
High‑level growth is necessary but not sufficient for strategy. The headline CAGR and market-size trajectory indicate a materially expanding addressable market for advanced aluminum alloys, carbon and glass fiber composites, titanium and nickel superalloys, and high‑performance thermoplastics. Yet beneath that headline lies divergence in growth drivers (commercial airframe platforms, defense modernization, rotorcraft niche programs, and aftermarket repair & overhaul flows), as well as variability in raw material availability and regulatory treatment across jurisdictions. Our full study preserves the headline figures while deliberately keeping granular segment tables gated—this is by design to ensure critical, actionable segmentation remains a conversion point for leaders seeking the full intelligence package.
Dynamics reshaping supplier economics and risk in 2026
-
Raw material cost volatility: PAN‑based carbon fiber precursor and acrylonitrile feedstock experienced upstream cost pressure in late 2025 and into Q1 2026, producing short‑term price steps and compression on margin for commodity grade suppliers. Procurement teams must assume episodic feedstock shocks and model scenarios for 3–5% price variance to stress test supplier contracts and hedging approaches.
-
Regulatory and trade friction: 2025–2026 brought new trade measures and stricter environmental permitting in several advanced manufacturing geographies, along with targeted tariffs on specific carbon fiber imports. These developments raise compliance costs, accelerate reshoring incentives, and make geographic footprint decisions for capacity expansion much more strategic than purely cost‑driven calculations.
-
Certification and time-to‑market: regulatory bodies moved to streamline certification for established alloys and composite systems, lowering the barrier for scaled adoption of proven materials. At the same time, early‑mover advantage remains critical for novel thermoplastics and PAEK variants that promise manufacturing throughput gains.
-
Manufacturing automation and materials substitution: next‑generation aircraft programs are shifting design and production paradigms toward larger monolithic composite structures, thermoplastic solutions for interiors and some primary components, and integrated automated layup. These trends favor suppliers able to combine material R&D with process innovation and digital twins for performance validation.
Competitive landscape — what to watch among leading players
The market is anchored by a set of established materials houses and specialty chemical firms that combine raw material production with composite system integration. Several themes emerge from our competitive review:
-
Vertical integration and system play. Firms traditionally focused on carbon fiber precursors and reinforcements are expanding into prepregs, resin systems, and even part-level certifications. This broadening of scope reduces OEM dependence on fragmented suppliers and increases barriers to entry for pureplay newcomers.
-
Capacity and geographic strategy. Multiple incumbent producers are executing capacity expansions in key geographies to secure long‑lead feedstock and to mitigate tariff exposure and logistics risk. New capacity announcements should be read alongside permitting timelines and qualification schedules rather than as pure production metrics.
-
Thermoplastics and high‑performance polymers gaining share. Companies investing in PAEK/PEEK platforms and high‑temperature thermoplastics are placing strategic bets on faster cycle times, recyclability, and repairability—attributes increasingly valued by airframers pursuing lifecycle cost reduction and sustainability targets.
-
Certification and qualification as a commercial moat. Achieving type‑approval pathways, FAA recognition, and NCAMP qualifications materially accelerates adoption curves. Suppliers that can bring both material innovation and documented certification pathways will outcompete those offering only raw inputs.
Representative company activity underscores these themes. Market leaders with deep carbon fiber and composite portfolios continue to showcase automated manufacturing systems and lightweight structural solutions at major airshows. Japan‑ and Europe‑based incumbents are expanding production and commercializing advanced braided fabrics and thermoplastic matrices. Certification wins for resin systems and full commercial availability of advanced thermoplastic granules have moved several players from pilot production to mainstream supply. For procurement and strategy teams, the practical implication is clear: partner selection must account for product roadmaps, qualification status, and production footprint, not only unit price.
Strategic implications and recommended actions for 2026
-
For OEMs and Tier‑1s: adopt a dual‑track sourcing strategy. Lock in long‑term agreements with qualified, capacity‑secure suppliers while maintaining small, flexible trials with innovative material providers that can deliver lifecycle cost or weight advantages. Prioritize suppliers with demonstrable certification progress and in‑region production to de‑risk tariffs and logistics.
-
For material suppliers: prioritize qualification programs and scalable manufacturing. Investments that shorten certification timelines and increase throughput—automation, predictive quality, and digital material passports—deliver disproportionate commercial returns. Consider selective vertical moves (e.g., resin systems, prepregs) to capture additional margin and strategic relevance to OEMs.
-
For investors and M&A teams: look for bolt‑on plays that add certification horsepower, regional capacity, or proprietary thermoplastic formulations. The market’s moderate concentration means well‑timed acquisitions can significantly alter competitive positioning, especially when combined with operational excellence programs to address upstream feedstock volatility.
-
For procurement and supply‑chain leaders: build feedstock contingency and tax/regulatory scenario plans into 2026 budgets. Hedging, multi‑sourcing, and collaborative supplier investment (e.g., co‑funded capacity expansions) will be essential to cushion short‑term raw‑material shocks while securing long‑term cost visibility.
-
For R&D and product teams: align material selection to manufacturability and lifecycle metrics. Prioritize materials that reduce total cost of ownership—considering repairability, recyclability, and certification burden—over element-wise BOM cost savings.
What the PW Consulting report delivers (practical, executable content)
Our full study provides an end‑to‑end toolkit for 2026 planning cycles, including:
-
Forward‑looking demand scenarios and sensitivity analyses that translate program decisions (airframe mix, defense budgets, aftermarket recovery rates) into material demand and pricing implications for the 2026–2032 window.
-
A rigorous competitive benchmarking suite that maps product portfolios, certification status, global footprints, and recent strategic moves of the leading suppliers—enabling rapid shortlisting for procurement pilots or M&A screening.
-
Operational playbooks for suppliers and OEMs: qualification roadmaps, sample contract language for capacity commitments, and a checklist for integrating automation and digitalization in composite production lines.
-
Risk matrices and mitigation frameworks covering feedstock shocks, regulatory shifts, and trade measures—plus modeled P&L impacts under multiple raw‑material and tariff scenarios.
-
Actionable implementation calendars that sequence certification milestones, capacity investments, and procurement decisions to align with airframe program timelines and regulatory windows.
To preserve the commercial utility of this intelligence and to honor proprietary supplier data, our public introduction intentionally omits gated segment tables and location‑level demand schedules. These high‑value matrices and model files are included in the full report and client dashboards.
Final takeaway — the strategic question for 2026
As the market grows and diversifies, the single biggest strategic question for leadership teams is not whether materials matter—they do—but how to balance near‑term stability with long‑term advantage. Do you secure capacity and manage price volatility through conservative contracting, or do you invest aggressively in qualifying novel materials and manufacturing processes that could rebase lifecycle cost and environmental performance? The right answer will likely be both: protect core programs while creating optionality through targeted pilots, partnership investments, and qualification pipelines.
PW Consulting’s Aerospace Materials Market study converts that strategic dilemma into a prioritized set of actions keyed to the 2026 decision calendar. For procurement heads, corporate strategists, R&D leaders, and investors preparing for the next wave of airframe programs, the full report provides the granular segmentation, supplier scorecards, and scenario models necessary to move from hypothesis to executable plan.
Next step
Access to the full dataset, supplier models, and implementation checklists is available through our report portal. For a custom briefing tailored to your program timelines, supplier roster, or M&A appetite, contact PW Consulting to schedule a 2026 strategic workshop.
For detailed analysis of this topic, please visit the official page: Aerospace Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com