

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
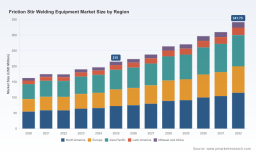
PW Consulting: Friction Stir Welding Equipment Market to Reach USD 341.75M by 2032 (6.7% CAGR)

Friction Stir Welding Equipment Market: Strategic Imperatives for 2026
Executive synopsis
As manufacturers accelerate electrification, lightweighting and high-integrity joining in aerospace, automotive, rail and shipbuilding, Friction Stir Welding (FSW) has moved from niche innovation to mainstream production technology. Our latest PW Consulting market study — anchored on a 2025 base year and projecting through 2032 — shows the global FSW equipment market expanding at a steady compound annual growth rate of approximately 6.7%. Market value growth between 2025 and 2032 underscores material demand for scalable, robot-enabled and hybrid FSW systems across multiple heavy-industry value chains.
Friction Stir Welding Equipment Market
Why this research matters to corporate decision-makers in 2026
-
Strategic capital allocation: With predictable mid-single-digit CAGR and visible upside from EV and aerospace programs, executive teams can time CAPEX for FSW automation with greater confidence. Our study translates macro growth into phased investment horizons, payback scenarios and technology-risk overlays that align with fiscal planning cycles.
Friction Stir Welding Equipment Market -
Supplier and partner selection: FSW supplier choice now drives product architecture as much as cost. The report profiles incumbent machine OEMs, robotics integrators and niche head/ spindle suppliers — enabling procurement to run rigorous make-or-buy, co-development and qualification roadmaps.
Friction Stir Welding Equipment Market -
Regulatory and quality readiness: ISO 25239-series requirements are increasingly enforced in aerospace and safety-critical manufacturing. We map procedure qualification and operator certification levers to program timelines so quality teams can avoid late-stage rework and certification bottlenecks.
-
Risk-adjusted scenario planning: Raw material volatility, labor shortages and energy mandates are now core to welding strategy. The study quantifies sensitivity to aluminium price swings and technician availability, and offers hedging and automation scenarios that materially impact TCO.
Report scope — what you will find (and what we deliberately withhold here)
-
End-to-end market sizing and forecasting from 2020 through 2032, with a transparent methodology and stress-tested scenarios for low-, base- and high-growth paths.
-
Detailed segmentation by equipment type, application and geography — presented with supplier maps and adoption curves. (Note: To preserve the commercial utility of the dataset, granular subsegment values and percent shares are available in the full report only.)
-
Operational playbooks: CAPEX calculators, OEE impact templates, robotic cell layout heuristics, and a rapid qualification checklist aligned to ISO 25239.
-
Competitive intelligence: Comparative capability matrices, product roadmaps and acquisition targets derived from primary interviews and recent transaction/partnership tracking.
-
Strategic scenarios: Three prioritized strategic paths — (1) automation-led scale for high-volume automotive/e-mobility, (2) systems-integration for aerospace and pressure-vessel applications, and (3) service- and aftermarket-led monetization for decentralized fabrication networks.
Market dynamics shaping 2026 decisions
-
Technology adoption and product differentiation — Robotic FSW and hybrid CNC-FSW units are becoming the default for manufacturers seeking repeatable high-throughput joints with low post-process finishing. Vendors that offer fully integrated head/spindle packages, robust process control and digital monitoring command commercial leverage during qualification cycles.
-
Raw-material and input-cost sensitivity — Aluminium feedstock price movements materially affect upstream material choice and welding economics. For example, recent trading in aluminium has tightened margin assumptions for high-volume structures and influences make-vs-buy decisions for thick-plate versus sheet joining.
-
Standards and certification — The ISO 25239 series now forms the backbone of FSW procedure qualification in regulated industries. Programs that integrate these requirements early in the design and procurement stage reduce time-to-market and avoid late-stage redesigns.
-
Labor and skills — Advanced FSW cells require multi-disciplinary skills (robot programming, process metallurgy, fixture design). Our fieldwork documents substantial shortages in skilled technicians at smaller OEMs; mitigations include strategic partnerships with integrators, in-house training academies and digital twin-enabled upskilling.
-
Energy and sustainability — FSW delivers material energy advantages versus traditional fusion welding methods; typical process-level gains can be in the low- to mid-teens percentage range for energy consumption. This creates an operational and reputational incentive for sustainability-minded manufacturers pursuing Scope 1/2 reduction targets.
How incumbent vendors and new entrants are positioning — competitive implications
-
MTI Welding (United States): A global machine OEM with STIRTEC know-how focused on industrial-scale systems. Strengths lie in turnkey systems and deep industrial experience; they compete strongly for large programs requiring process certification and onsite support.
-
Mazak Corporation (Japan): Positions FSW as an integrated capability within hybrid multi-tasking CNC platforms. Their strategy targets customers seeking consolidation of machining and joining to reduce footprint and part handling.
-
PAR Systems (United States): Offers large-format I-STIR™ cells tailored to heavy fabrication. Their competitive advantage is in handling complex geometry and large work envelopes.
-
FOOKE GmbH and Quickmill (Germany / United States): Both bring high-performance gantry-style solutions and emphasize precision sheet and plate joining — particularly attractive for OEMs seeking repeatable panel welds at scale.
-
Stirweld (France): Specialist in FSW heads and spindles for robotic integration. Their modular head approach enables retrofit pathways and is attractive to machine shops and integrators seeking to add FSW capability without wholesale system replacement.
-
Bond Technologies and FPT Industrie (United States / Italy): Focus on industrial system solutions and niche OEM partnerships; they compete for aerospace and rail programs where qualification and traceability are critical.
-
KUKA AG (Germany): As a robotics integrator, KUKA is winning orders for FSW robotic cells that support EV battery housing assembly and other high-volume use cases, leveraging its robot portfolio and systems expertise.
Recent industry moves that matter for 2026 strategy
-
Collaboration on advanced heads: Partnerships showcasing retractable-pin FSW heads for hydrogen-storage-grade aluminium tanks signal an emerging aerospace/space opportunity where joint integrity and certification are non-negotiable.
-
High-volume automotive orders: Large robotic FSW cell procurements for electric vehicle housings indicate OEMs are moving from pilots to production. Procurement and industrialization teams must align supplier qualification windows with vehicle program milestones.
-
Trade-show technology evangelism: Public demonstrations and showcases by OEMs and integrators reduce perceived technology risk and accelerate buyer education. Buyers should treat these as indispensable due-diligence inputs but validate performance in customer-specific conditions.
Strategic actions for 2026 planning cycles
-
Short-term (0–12 months): Lock in supplier pilots tied to specific program KPIs (cycle time, rejection rate, energy use), run procurement RFIs that capture qualification support and spare-parts SLAs, and start operator certification programs aligned to ISO 25239.
-
Medium-term (12–36 months): Scale robotic FSW cells in prioritized product lines, build retrofit roadmaps for legacy machining assets using modular heads, and evaluate captive vs outsourced coating/finishing strategies to maximize throughput.
-
Long-term (36+ months): Consider M&A to secure critical head/spindle IP, invest in digital twins for virtual qualification, and develop service-led revenue models that monetize preventive maintenance and process optimization.
Operational levers and KPIs we recommend tracking
-
Qualification lead time to first production: measure from contract signature to first approved part under ISO-aligned procedure qualification.
-
Weld cost per linear meter or per joint: incorporate energy, tooling wear, operator time and rework to compare against alternative joining methods.
-
Upskilling throughput: ratio of certified FSW operators per cell to total operators, tracking training cycle time and retention.
-
Service availability and MTTR for heads and spindles: critical for high-utilization OEM lines.
Final perspective — what PW Consulting recommends now
FSW is no longer experimental; for many high-value structural applications it is becoming the default. The 2025 market baseline and our 2032 projection provide a clear backdrop for sensible, staged investment. PW Consulting advises manufacturers and investors to prioritize supplier qualification, integrate ISO-compliant procedures early, and treat automation as both an operational and strategic lever. For industrial players that move quickly, opportunities exist across product differentiation, aftermarket services and platform consolidation.
For clients seeking executable roadmaps, our study delivers the primary datasets, vendor scorecards, CAPEX/ROI templates and scenario models necessary to convert the macro trend into quarterly milestones. Detailed subsegment tables, regional and application split analytics, and downloadable financial models are available in the full report — a necessary set of instruments for informed boardroom decisions in 2026.
For detailed analysis of this topic, please visit the official page: Friction Stir Welding Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com