

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Surgical Blades & Scalpels Market to Reach USD 312.3M by 2032 at 5.2% CAGR

Surgical Blades & Scalpels Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I prepared this executive field brief to frame the strategic choices medical-device executives, hospital procurement leaders, private equity investors, and policy teams must make in 2026. The Surgical Blades & Scalpels market occupies a paradoxical position: small in absolute dollars compared with complex implants, yet tightly coupled to surgical throughput, patient safety programs, and perioperative economics. This briefing synthesizes our market sizing, growth trajectory, regulatory context, competitive dynamics, and pragmatic go-to-market options — enough to orient high-stakes decisions while preserving the granular tables, model outputs, and segmentation breakdowns that you will find in the full report.
Surgical Blades & Scalpels Market
Market Snapshot: Scale, Growth and Momentum
In our base-year view (2025) the global Surgical Blades & Scalpels market reached approximately USD 219.8 Million, reflecting steady expansion from the early-2020s. Our historical model captures the post‑pandemic rebound in elective surgery volumes and incremental product upgrades across sterile single-use platforms. Looking forward, we forecast the market to grow at a compound annual growth rate (CAGR) of 5.2% across the 2026–2032 planning horizon, reaching a mid‑to‑high three‑hundred million dollar range by the end of the forecast period. This trajectory reflects a mix of steady unit demand driven by procedural volumes and selective value migration toward premium safety and micro‑precision blades.
Surgical Blades & Scalpels Market
Why the Market Matters for 2026 Strategic Choices
- Procurement optimization: With blades accounted for inside bundled surgical fees rather than reimbursed separately, hospital systems must pursue total cost of ownership and sharps‑injury reduction metrics rather than unit price alone.
- Product portfolio prioritization: Manufacturers need to balance low‑margin, high‑volume disposable products with niche, higher‑margin offerings (e.g., micro and ophthalmic blades, safety scalpel systems) and services such as sterilization and kit integration.
- M&A and partnership timing: Modest overall market growth but strong consolidation dynamics make 2026 a window for bolt‑on acquisitions, distribution alliances, and capacity plays that add sterilization or regulatory depth.
- Regulatory and compliance risk: Evolving single‑use validation standards and workplace safety regulations alter procurement drivers and create demand for certified safety scalpel lines.
Key Market Dynamics — What’s Driving Change
- Safety and worker protection: Enforcement of occupational safety legislation and standards is accelerating adoption of single‑use sterile and engineered safety scalpels to reduce sharps injuries. This is a structural tailwind for disposable and safety‑oriented SKUs.
- Regulatory clarity with pragmatic implications: In primary markets, basic scalpel products remain classified in lower device classes with reduced premarket burdens, which keeps barriers to entry relatively modest. However, higher scrutiny on sterilization validation, ISO 13485 facility certification, and EU medical-device regulations means manufacturers exporting to regulated markets must maintain disciplined quality systems and documentation.
- Reimbursement and purchasing behavior: Because blades are integrated into surgical episode payments — not itemized with dedicated codes — buyers focus on net procedural economics and risk mitigation. Devices that demonstrably reduce OR time, reduce reprocessing costs, or lower sharps incidents gain disproportionate commercial leverage.
- Technology and specialization: Advances in micro‑blade metallurgy and laser‑assisted cutting solutions are extending product differentiation beyond commodity steel. At the same time, specialization in dental, ophthalmic, and micro‑surgery niches creates defensible margins for focused players.
- Supply chain and geopolitics: Manufacturing clusters in East Asia and Europe continue to supply global demand. 2026 decisions must account for sterilization capacity, certification timelines, lead‑time exposure, and dual‑sourcing strategies for critical consumables.
Commercial Implications — How to Compete in 2026
Given modest overall growth but meaningful opportunity to extract value via differentiation, companies should align to one of three pragmatic plays:
Surgical Blades & Scalpels Market
- Commodity scale and cost leadership: Invest in high‑efficiency production, verticalized sterilization, and optimized global distribution to serve high‑volume hospital systems and low‑cost markets. Margin resilience depends on operational excellence and predictable supply.
- Premium safety and integrated solutions: Bundle safety scalpels with training, sharps‑disposal solutions, and OR workflow analytics to shift purchasing conversations from price to risk and total cost.
- Niche precision specialization: Focus on ophthalmic, micro‑surgery, or dental subsegments where micro‑blade sharpness, tolerances, and brand reputation command pricing power and clinical preference.
Competitive Landscape — Who Moves Markets
The competitive field comprises established heritage manufacturers, regional scale producers, and specialized niche suppliers. The market demonstrates discernible concentration among the leading vendors, creating both barriers and buyout opportunities for challengers. Key company archetypes and strategic postures we analyze in the full report include:
- Heritage precision leaders: Longstanding specialists with deep blades‑manufacturing expertise and strong global brands that command clinical trust in general surgery and precision applications. Their advantages lie in brand equity, clinician relationships, and long product catalogs.
- North American commercial scale players: Companies focused on hospital and ASC channels that combine domestic manufacturing, regulatory experience, and broad distribution networks — attractive targets for distribution deals and channel expansions (for example, recent strategic distribution moves in 2025 show how manufacturers accelerate footprint via local partners).
- Japanese precision and micro‑blade innovators: High‑quality stainless‑steel and micro‑blade suppliers who win in applications requiring extreme sharpness and consistency, often commanding premium pricing.
- Large diversified medical OEMs: Corporates embedding blades into broader perioperative portfolios to deliver integrated kits and bundled supply contracts, shifting procurement conversations toward system-level value.
- High‑volume Asian manufacturers: Cost‑competitive producers supplying disposable sterile blades at scale to global distribution channels, often thriving where cost and availability are primary selection criteria.
We profile each major competitor in the full briefing, including their product focus, geographic strengths, recent commercial developments, and implied strategic playbooks. Notably, recent distribution agreements and channel realignments in 2025 highlight how manufacturers are accelerating market access without heavy capital expenditure.
Regulatory and Reimbursement Touchpoints — Practical Impacts
- Device classification and market entry: Many scalpel and blade variants remain in lower device classes with exempted premarket pathways in primary markets — simplifying registration but not obviating GMP and quality‑system diligence.
- Occupational safety standards: OSHA and international standards that mandate or incentivize safety scalpel use materially shift demand dynamics inside hospital procurement committees.
- Reimbursement framing: Absence of discrete reimbursement lines means suppliers must quantify value in operational terms (OR efficiency, incident reduction, sterilization avoidance) to capture premium pricing.
- Quality assurance: ISO 13485 certification and strict single‑use validation under advanced regulatory regimes are table stakes for sustained access to high‑value markets.
Supply Chain & Manufacturing Considerations
Surgical blades are not technologically complex, but supply reliability depends on metallurgical sourcing, precision stamping/grinding, and validated sterilization. In 2026, buyers will prioritize vendors with proven multi‑regional capacity, traceable material chains, and rapid scalability for elective surgery rebounds. Investments in regional sterilization hubs, validated single‑use production lines, and serialization for traceability will create competitive differentiation and cost predictability for key customers.
What the Full PW Consulting Report Contains
The complete market study delivers the decision-grade assets leaders need in 2026:
- An audited market size model (2020–2025 historical, 2026–2032 forecast) with scenario analysis driven by procedural volume, product mix shifts, and pricing elasticity.
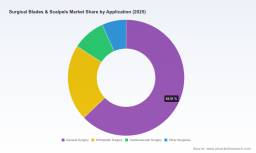
- Segmented forecasts by product type, application, and geographic region with sensitivity tables and growth-drivers mapping (segmentation granularity is included in the full report).
- Competitive heatmaps and strategic profiles for major firms, with capability assessments, revenue mix indicators, and acquisition targets.
- Commercial playbooks: pricing frameworks, procurement scorecards, tender checklists, and OR value calculators that buyers and sellers can apply immediately.
- Supply chain risk matrix and manufacturing investment checklist — including sterilization capacity, certification timelines, and dual‑sourcing playbooks.
- M&A and partnership advisor tools: target screening criteria, valuation multiples benchmarks in adjacent consumable markets, and integration checklists.
- A regulation and compliance appendix defining certification requirements, workplace safety drivers, and a timeline of recent policy developments that directly influence adoption.
How to Use This Intelligence in 2026 — Practical Next Steps
- For manufacturers: prioritize investments that shift procurement conversations away from unit price (safety, TCO, kit integration); accelerate ISO and MDR readiness where relevant.
- For hospital systems and group purchasing organizations: deploy supplier scorecards that weight sharps‑injury outcomes and sterilization avoidance alongside price; consider multi‑year partnerships tied to OR efficiency KPIs.
- For investors: target bolt‑on acquisitions that add sterilization capacity, niche micro‑blade IP, or regional distribution reach; emphasize targets with quality systems already aligned to regulated-market requirements.
- For regulators and policy teams: use the market’s structural characteristics to calibrate guidance that balances clinician access, workplace safety, and device quality assurance.
Closing — The Strategic Value of the PW Consulting Report
By 2026, decisions in the Surgical Blades & Scalpels market will hinge less on whether unit demand grows and more on who can convert modest market growth into durable margin expansion through differentiation, service, and regulatory excellence. Our report combines a data‑backed macro view, rigorous segmentation, and hands‑on commercial playbooks to translate that modest CAGR and steady market expansion into executable strategies.
This briefing is intentionally directional — offering the context and frameworks you need while preserving the detailed models, segmentation tables, and company scorecards available in the full PW Consulting study. For the complete dataset, downloadable models, and bespoke advisory support tailored to your business questions in 2026, please consult the full report and contact our team.
For detailed analysis of this topic, please visit the official page: Surgical Blades & Scalpels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com