

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Saw Wire Market Poised for 6.98% CAGR Through 2032 - PW Consulting

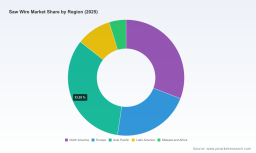
Saw Wire Market 2026: Strategic Primer for Executive Decisions
As PW Consulting’s Chief Industry Analyst, I present a strategic preview of our Saw Wire Market study — a working compass for executives who must make decisive procurement, investment, and M&A choices in 2026. This primer synthesizes the study’s macro trajectory, the critical supply-chain and regulatory inflection points shaping supplier economics, and the competitive dynamics that will determine winners and losers across industrial, semiconductor, and construction end markets.
Saw Wire Market
Why this study matters for 2026 decision cycles
-
Macro momentum and timing: The saw wire market has demonstrated steady recovery and expansion through 2020–2025, rising from USD 163.15 million in 2020 to USD 215.0 million in 2025. Our forecast—anchored to a 2025 base year—projects continued growth into the latter half of the decade, reaching USD 344.8 million by 2032 at a compound annual growth rate (CAGR) of 6.98% for the 2026–2032 period. That growth profile elevates strategic urgency for supplier selection, capacity planning, and technology investment in 2026.
Saw Wire Market -
Risk-transferring inflection: Raw-material cost volatility, trade-policy shifts, and tightened chemical compliance are converging on an industry with thin transactional margins. Decisions made in 2026 on contracting tenor, localization, or vertical integration will materially affect cost of goods sold and lead-times through the forecast window.
Saw Wire Market -
Fragmented competitive landscape: Market concentration remains low relative to many industrial-input markets. This fragmentation creates opportunities for consolidation, premium differentiation, and targeted partnerships — but also raises execution complexity for buyers seeking assurance of supply continuity and consistent quality.
What the full report delivers — practical, decision-ready intelligence
-
Demand and supply trajectories: A granular view of historical consumption (2020–2025) and scenario-based forecasting (2026–2032), including base, upside, and downside scenarios that stress-test demand drivers such as semiconductor wafer slicing, photovoltaic feedstock, and construction/stone applications.
-
Cost-driver modeling: A transparent decomposition of unit economics showing the impact of steel-wire feedstock prices, diamond-abrasive costs, energy inputs, and labor. The model integrates recent raw-material signals and Producer Price Index movements to quantify margin exposure across supplier archetypes.
-
Regulatory and trade impact analysis: Actionable intelligence on emerging compliance requirements and trade controls — from chemical substance restrictions to export license regimes — with practical mitigation paths for procurement and regulatory teams.
-
Competitive playbooks: Company-level positioning, capability matrices, product architecture comparison, and sourcing risk heat maps for the leading saw wire providers. We combine public disclosures with primary interviews to assess manufacturability, R&D focus, after-sales support, and channel strength.
-
Procurement and commercial tools: Negotiation templates, contract clauses to hedge raw-material spikes, supplier-qualification checklists, and an ROI framework for make-versus-buy and CAPEX decisions.
-
M&A and partnership opportunities: A shortlist of acquisition targets and JV archetypes by strategic objective (market access, technology leap, or supply security), supported by valuation sensitivities and integration risk diagnostics.
Key market dynamics to watch in 2026
-
Input-cost inflation is real and measurable. Recent weeks show hot-rolled coil and steel-wire related indices trending higher, and the Producer Price Index for carbon steel wire drawing has been on an uptrend. For manufacturers whose cost base is steel- and energy-intensive, pricing pass-through and contract renegotiation will be front-and-center in 2026.
-
Regulatory tightening alters supplier risk profiles. New export-license regimes and an expanded REACH SVHC list increase compliance overheads for global suppliers. The EU’s energy-supply measures and changing trade controls can lengthen lead times and raise onshore inventory premiums.
-
End-market shifting: Semiconductor wafer slicing and high-precision industrial cutting remain primary demand engines, with specialized wire technology and consumable performance dictating procurement choices. Adjacent markets—natural stone mining and construction—are also being reshaped by portable-saw innovations targeting on-site productivity gains.
Competitive landscape — who to watch and why
The industry blends heritage engineering firms, regional manufacturers, and vertical specialists. Key participants that shape technology, service quality, and channel dynamics include:
-
Well Diamond Wire Saws SA (Switzerland) — long-standing precision focus and an emphasis on high-quality stainless steel wires and machine integration. Their brand strength is centered on durable, high-precision systems for demanding industrial slicing tasks.
-
Asahi Diamond Industrial Co. (Japan) — a major innovator in diamond-wire abrasive formulations, with strong ties to semiconductor and photovoltaic segments where slicing precision and wafer integrity are non-negotiable.
-
Noritake Co. Limited (Japan) — expertise in consumables and coating technologies for industrial sawing, with a reputation for material science depth that benefits high-throughput environments.
-
SOMOS IWT (United States) and MTI (United States) — providers with North American manufacturing footprints, servicing laboratory and industrial customers where delivery responsiveness and customization matter.
-
Husqvarna Construction (Sweden) — global distribution scale and strong presence in construction and stone, often competing on service ecosystems, rentals, and aftermarket consumables.
-
Regional specialists and OEMs (Diamond WireTec, Ensoll Tools, Princeton Scientific, Thermocompact, Wire Saw Solutions Group) — collectively represent a breadth of product forms (coils, loops, electroplated vs. sintered wires) and service models (distribution, full-service saws, aftermarket).
Strategic implications: incumbent technical leaders hold pricing power in high-spec segments (e.g., wafer slicing), while nimble regional players compete on lead time, customization, and bundled service. The low five-firm concentration underscores both acquisition opportunity and procurement complexity for OEMs and large end-users.
Recent developments and their strategic signals
-
Product launches targeted at specific use-cases (e.g., mobile saws for quarry blocks) indicate continued segmentation by application; mobility and on-site productivity are differentiators in construction and stone markets.
-
New entrants expanding into semiconductor-grade wire production suggest intensifying competition where margins and quality thresholds are highest — an area where incumbent suppliers will need to defend intellectual property and supply relationships.
Five strategic plays for 2026
-
Hedge input-cost exposure: Lock multi-year supply agreements with indexed escalators, while building optionality through geographically diversified suppliers and safety-stock corridors aligned with lead-time volatility forecasts.
-
Prioritize quality-linked sourcing for high-value segments: For wafer and precision-slicing applications, adopt supplier scorecards weighted toward material science capability, R&D pipeline, and process-control certifications rather than lowest unit price.
-
Invest selectively in vertical capabilities: Consider targeted backward integration (wire drawing, diamond-impregnation processes) where scale economics and IP control can shift margin curves over a 3–5 year horizon.
-
Mitigate regulatory and trade risk: Implement a compliance roadmap to absorb REACH and export-license changes; map single-source items that could be impacted and preregister alternative qualified suppliers.
-
Pursue bolt-on consolidation and partnerships: The market’s fragmentation creates arbitrage for platform acquirers. Focus on targets that close capability gaps (e.g., electroplating, precision spooling, or aftermarket service networks) and enable rapid scaling into adjacent geographies.
How to use this preview now
Use this primer to align your executive agenda for 2026: set procurement objectives that reflect elevated raw-material risk, initiate supplier qualification projects for high-spec product lines, and evaluate potential M&A targets using the strategic plays outlined above. For commercial teams, prioritize deals that incorporate dynamic pricing clauses and shared-cost mechanisms for inputs with volatile indices.
PW Consulting’s full Saw Wire Market report contains the granular market splits, supplier scorecards, and downloadable financial models that translate the directional insights above into executable plans. In the spirit of this “trailer,” we have deliberately withheld the detailed regional, type, and application-level percentage tables from this preview to preserve the report’s operational value and data integrity.
Next steps
-
Procurement briefing: Run a 90-day supplier risk-mitigation sprint focused on high-exposure SKUs.
-
Investment screen: Shortlist potential acquisitions and run value-capture scenarios with our M&A playbook.
-
Regulatory readiness: Convene a cross-functional task force to operationalize REACH and export-control contingencies.
For teams preparing capital allocation, supply-chain redesign, or strategic partnerships in 2026, the full PW Consulting Saw Wire Market study provides the data, tools, and playbooks to convert insight into measurable outcomes. Contact our industry practice to schedule a deep-dive briefing and obtain the forecast spreadsheets, supplier matrices, and negotiation templates referenced in this preview.
For detailed analysis of this topic, please visit the official page: Saw Wire Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com