

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: BMS Market Poised to Hit USD 37.51 Billion by 2032 at 15.55% CAGR

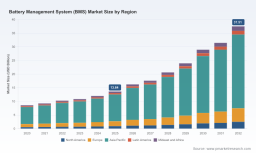
Battery Management System (BMS) Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest BMS Market study (base year 2025, historical coverage 2020–2025, forecast 2026–2032) is designed as an operative intelligence product for executives shaping strategy in 2026. The market is in a clear growth phase: total industry revenue has expanded from approximately 8.6 Billion USD in 2020 to about 13.64 Billion USD in 2025, and our forecast projects growth to 37.51 Billion USD by 2032 at a compound annual growth rate (CAGR) of roughly 15.55%. The 2026 inflection point — when sustained deployment of higher-voltage packs and expanded energy storage installations meet intensifying supply-side pressures — makes this study immediately actionable for capital allocation, product planning, and M&A activity.
Battery Management System (BMS) Market
Why this report matters for 2026 decisions
-
Timing and size: The report translates the observed historical momentum into near-term forecast scenarios that distinguish tactical moves (next 12–24 months) from structural shifts (2028+). For 2026 planning cycles, that distinction informs supply contracts, inventory strategies, and R&D prioritization.
Battery Management System (BMS) Market -
Risk-adjusted insights: We overlay commodity volatility, trade and tariff changes, and regional policy shifts onto demand trajectories to quantify downside scenarios and stress-test sourcing and production plans.
Battery Management System (BMS) Market -
Competitive positioning: Rather than merely cataloging vendors, the study maps capability clusters — OEM integrators, module-level specialists, software-first BMS providers, and test/validation toolmakers — enabling you to identify potential partners, acquisition targets, and white-space opportunities.
-
Operational playbooks: The report provides practical, board-ready recommendations for procurement, technology roadmaps, and go-to-market sequencing so that decisions made in 2026 translate to commercial advantage by 2027–2029.
Market dynamics shaping the 2026 horizon
-
Raw material volatility and upstream shocks: In 2025 and early 2026 we saw pronounced swings in lithium raw material pricing and supply constraints that materially affect cell cost and downstream BMS economics. Our analysis demonstrates how spot price moves and export controls can create localized cost inflation pockets, leading OEMs and integrators to re-price warranty assumptions or shift to revised state-of-charge management strategies that extend usable cycle life.
-
Regulatory and policy drivers: A number of fiscal and trade interventions in 2025–2026 have changed the cadence of production and export flows. Policy changes that reduce export incentives or new mineral export restrictions can prompt front-loading of shipments, altering quarterly demand and inventory cycles for BMS suppliers. The study models these effects across plausible policy permutations to inform contingency plans.
-
Technology and product evolution: Higher-current, cell-level active balancing, richer communications stacks (CAN, Ethernet, Wi-Fi/Bluetooth), and integrated thermal management are migrating from early-adopter installations into mainstream designs. This raises the technical bar for BMS suppliers and increases the value of firmware-upgradeable architectures — an area where long-term revenue streams (OTA updates, cybersecurity services) are beginning to emerge.
-
Safety, standards and certification pressure: As industrial and EV deployments scale, compliance requirements and certification regimes become decisive procurement filters. Systems that can demonstrate certified safety cases, fleet-level telemetry, and predictable de-rating behavior reduce insurer and OEM friction — a competitive advantage discussed in depth in the report.
-
System-level integration and lifecycle economics: Buyers are increasingly looking past per-unit hardware cost toward lifecycle metrics — usable cycles, BOS (balance-of-system) impacts, and second-life value. Our scenario work quantifies how modest BMS-enabled improvements in state-of-health monitoring and balancing efficiency translate into meaningful changes in total cost of ownership across different applications.
Competitive landscape — who matters and why
The market structure remains moderately fragmented; our concentration analysis shows that the three largest firms account for roughly 25% of revenue (CR3 ~25%), while the top five account for about 35% (CR5 ~35%). That profile indicates room for consolidation but also continued opportunity for specialized players to capture attractive niches.
-
Daly BMS (China) — Strengths: high-current designs, global distribution footprint, and rapid product iteration. Recent 4th Gen home energy storage platform and new portable charging offerings illustrate a playbook that pairs hardware evolution with connectivity and consumer-facing UX improvements.
-
Kuruibms (China) — Strengths: customized BMS solutions for commercial & industrial storage and EV markets. Their recent market guide and content marketing indicate a push to be perceived as a trusted supplier for bespoke OEM integrations.
-
Victron Energy (Netherlands) — Strengths: strong presence in off-grid and solar-integrated storage with proven system-level protocols (VE.Bus, Lynx). They benefit from deep inverter/system firmware integration skills and a strong installer network.
-
UgoWork (Canada) — Strengths: UL-certified BMS integrations for industrial fleets and material handling, targeting safety-sensitive deployments and fleet-scale rollouts.
-
Novelic (France) — Strengths: vehicle-focused BMS design, with emphasis on cooling integration and pack-level monitoring suitable for e-mobility OEMs.
-
comemso electronics (Germany) — Strengths: test and simulator solutions that accelerate development and validation of balancing algorithms — a critical enabler for faster time-to-market for active BMS designs.
-
Nuvation Engineering (US) & Elithion Inc. (US) — Strengths: custom engineering and embedded BMS expertise for industrial and energy storage OEMs. Their OEM/ODM capabilities make them logical partners for companies pursuing differentiated hardware + software stacks.
Recent vendor activity — product launches, documentation updates, and ecosystem compatibility statements — underscore two themes: (1) suppliers are moving to tie BMS functionality more tightly to system-level partners (inverters, chargers, and storage integrators), and (2) product-led differentiation (connectivity, firmware, and certification) is increasingly decisive. The deep profiles and recent events for these companies are summarized in the report; the decision-useful portion of our competitive analysis includes capability matrices, technology roadmaps, and a prioritized short-list of potential suppliers for different commercialization strategies.
What the report contains — practical deliverables
-
Market sizing and scenario forecasts (2026–2032) with transparent methodology, sensitivity tables and base/optimistic/pessimistic pathways to help with budget and capex planning.
-
Supplier capability maps and vendor heatmaps that score firms across design, certification, software, manufacturing scale, and service readiness.
-
Product and technology benchmarking templates, including validation test protocols, recommended KPIs for BMS performance, and firmware upgrade strategies.
-
Procurement and sourcing playbooks: contract templates, supply risk matrices, hedging strategies against raw-material swings, and suggested inventory buffers by scenario.
-
M&A and partnership screens: a prioritized list of acquisition and JV targets matched to strategic intents (vertical integration, geographic expansion, or capability acquisition) with indicative valuation frameworks.
-
Regulatory and standards tracker: a rolling register of policy changes, certification timelines, and compliance gates that affect time-to-market and cost of entry in major buyer segments.
How to use the research in 2026 — five immediate actions
-
Lock in tiered supplier agreements: Use the scenario outputs to negotiate flexible volume contracts with performance-based SLAs. Prioritize vendors with field-proven firmware-update capabilities to reduce recall risk.
-
Re-evaluate product roadmaps against cell chemistry and cost trajectories: If upstream price or availability signals suggest higher cell costs, accelerate BMS features that preserve usable capacity and extend warranty windows.
-
Invest selectively in validation infrastructure: Shorten integration cycles by adopting standardized test rigs and digital twins; vendors offering validated simulators can materially reduce development risk.
-
Pursue partnerships for system-level differentiation: Tie BMS features (energy optimization, fleet telematics, second-life controls) to value propositions that unlock recurring revenue and aftermarket services.
-
Prepare contingency playbooks for trade and supply shocks: The report’s stress tests provide trigger points to switch sourcing, prioritize regionalized capacity, or defer shipments without eroding customer trust.
Closing — why you should read the full study
The BMS market presents a rare combination of rapid top-line expansion (from mid‑single-digit billions in 2020 to multiple tens of billions by 2032) and nuanced supplier differentiation. Our study provides the quantitative forecasts and the executable guidance that translate those numbers into board-level decisions in 2026. To preserve strategic value for paying clients, this briefing intentionally omits granular segment-level allocations and detailed vendor revenue shares; the full dataset, segment splits, and supplier scorecards are available on the report landing page and include downloadable models and scenario tools that your commercial, engineering, and procurement teams can operationalize immediately.
For executives seeking to convert market growth into defensible market positions in 2026, this report is a decision-enabling toolkit: robust forecasts, supplier playbooks, and risk mitigations calibrated to the current policy and commodity environment. Access the full report to unlock the detailed segmentation, downloadable spreadsheets, and vendor diligence packages required to act with confidence.
For detailed analysis of this topic, please visit the official page: Battery Management System (BMS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com