

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
Bagged Salt Market — 2026 Strategic Primer
Executive summary
As companies finalize budgets and strategic plans for 2026, a calibrated understanding of the bagged salt market is essential. PW Consulting’s latest market intelligence positions the industry on a steady-growth trajectory: using 2025 as the base year, the global bagged salt market reached a multi‑million USD scale and exhibits a baseline compound annual growth rate (CAGR) of roughly 4.0% over the 2026–2032 forecast horizon. Our historical view (2020–2025) shows a resilient recovery from cyclical pressures with demand drivers that differ materially by end‑use and channel.
Bagged Salt Market
This briefing is designed as a high‑signal trailer: it synthesizes the implications of the full study — markets, players, regulatory dynamics, and actionable playbooks — while intentionally withholding the report’s granular segment numbers so you will consult the source for detailed breakdowns and downloadable models.
Bagged Salt Market
Market trajectory and key inflection points to watch in 2026
-
Continuing growth with structural nuance — The market is expected to expand from its 2025 base into the forecast period, reflecting steady demand across de‑icing, industrial feedstock, and specialty commercial uses. Aggregate growth is moderate (CAGR ~4.0%), but the underlying drivers vary by seasonality, geography and application.
Bagged Salt Market -
Seasonal volatility remains a strategic factor — Weather variability and winter severity drive short‑term procurement cycles and working capital swings for manufacturers and resellers. Inventory management and flexible logistics are high‑return levers.
-
Input and price signals — Broad industry reporting shows salt production and distribution remain substantial in scale, with stable average unit values for bulk and packaged products in recent public data. Expect pricing sensitivity in tight winter seasons and in regions with concentrated supply points.
-
Regulatory and ESG inflection — Environmental requirements for salt handling, runoff, and packaging are intensifying. Compliance and demonstrable mitigation measures will shift procurement preferences toward suppliers that can document lower environmental impact and reliable end‑to‑end stewardship.
Why this matters for 2026 decision‑makers
-
Procurement and supply‑chain resilience: With the market's moderate growth profile, incremental supply‑side shocks (plant maintenance, logistic constraints, labor issues) can create outsized price and availability impacts during peak demand windows. Short‑term tactical steps — longer lead contracts for key seasons, inventory hedging strategies, and multi‑supplier sourcing — must be balanced against working capital objectives.
-
Portfolio and channel strategy: Companies with exposure to multiple end‑uses should reassess portfolio mix given differing margins and growth outlooks. Specialty products and value‑added blends are increasingly important to capture premium channels (commercial snow‑management, specialty industrial customers), and investment here can outpace growth in commoditized segments.
-
Capital allocation and M&A: The industry’s structure favors players with scale in production, packaging and distribution. For 2026, inorganic growth remains a pragmatic pathway to secure geographic fill‑ins, gain packaging capacity, or acquire specialty formulations. Firms should prioritize targets that offer immediate synergies in distribution or seasonal storage.
-
Pricing architecture and customer contracts: Dynamic pricing clauses tied to seasonal indices, index floors for critical raw inputs, and capacity reservation fees are effective: they preserve margin during peak demand while keeping customers committed. Revisit contracting language to reflect volatility observed in recent seasons and to de‑risk both suppliers and buyers.
-
ESG and stakeholder value: Visibility into sourcing footprints, handling of brine and runoff, and packaging recyclability are no longer table stakes — they are commercial differentiators. Buyers increasingly incorporate supplier ESG performance into vendor selection; producers must operationalize traceability and compliance to protect market access.
Competitive landscape — strategic profiles and implications
The bagged salt market is characterized by a small set of well‑established producers and regional specialists that together determine supply flexibility and price dynamics. Below we profile core players and pragmatic strategic implications for competitors, procurement teams and potential investors.
-
American Rock Salt Company (Mt. Morris, NY) — Strength: high underground‑mine throughput and established logistics for de‑icing. Strategic implication: its capacity and operational scale make it a natural partner for large municipal and highway contracts. For buyers, lock‑in options or multi‑year agreements can secure access during peak seasons. For competitors, incremental efficiency improvements in packaging or last‑mile logistics are required to counter its scale advantage.
-
Compass Minerals (Overland Park, KS) — Strength: diversified feedstock (rock and evaporated salts) and integrated distribution networks from major mines. Strategic implication: Compass’s recent fiscal disclosures underscore disciplined capacity utilization. Firms evaluating partnership or supplier rationalization should consider the benefits of stable year‑round supply versus localized cost advantages from smaller suppliers.
-
Morton Salt (Chicago, IL) — Strength: brand strength across consumer and industrial channels, broad product slate including specialty and food‑grade salts. Strategic implication: Morton's channel reach offers premium pricing opportunities in retail and specialty segments. Competitors should consider channel specialization or private‑label strategies to protect margin erosion in retail corridors.
-
Gunther Salt (St. Louis, MO) — Strength: regional distribution and product variety serving commercial, institutional and municipal customers. Strategic implication: regional players retain renewal advantages through local relationships and rapid replenishment capabilities; national players should evaluate bolt‑on acquisitions to close regional service gaps.
-
K+S Aktiengesellschaft (Hannover, Germany) — Strength: global portfolio and cross‑border supply capabilities to serve industrial and food markets. Strategic implication: multinational firms and industrial buyers value K+S for supply security and compliance pedigree; domestic players should pursue operational differentiation or niche product lines to defend against imports in regions with cross‑border exposure.
Recent public developments reinforce these strategic imperatives: American Rock Salt’s 2026 operational communications emphasize strong production continuity, and Compass Minerals’ latest fiscal update highlights capacity utilization trends that are shaping supply availability for the 2026 planning cycle.
Risks, regulation and industry “noise” to monitor
-
Regulatory environment: Recent industry data confirm the chemical sector captures a large share of salt demand and that production and usage volumes remain significant nationally. Regulators are sharpening focus on brine management, stormwater controls and road salt impacts on freshwater — anticipate stricter local ordinances and procurement specifications in the near term.
-
Supply concentration and geographic exposure: A limited number of mines and plants supply substantial portions of the market. This concentration creates vulnerability to regional outages and maintenance cycles; scenario planning should quantify the impacts of short‑term production disruptions on procurement costs and service levels.
-
Market noise vs. signal: Not every weather event or short‑term price spike signals a structural shift; our scenario suite differentiates transient shocks from persistent trend changes. Use those scenarios to stress‑test contract language and inventory strategies.
-
Stable unit values reporting: Publicly available industry analyses indicate relative stability in average unit values across bulk and packaged salt in recent reporting — a useful baseline when modeling price exposure.
What PW Consulting’s full report delivers — practical contents
The full PW Consulting Bagged Salt Market study is designed for immediate operational use by procurement teams, commercial leaders, strategic planners and M&A professionals. Highlights include:
- Proprietary forecast model (2026–2032) with scenario toggles and downloadable datasets (USD, Million).
- Demand driver decomposition by end‑use and channel (methodology and elasticities included).
- Supply‑side mapping and a risk heatmap of production nodes, logistics corridors and seasonal bottlenecks (interactive GIS layer included in the report package).
- Supplier scorecards and playbooks for procurement (performance, capacity, ESG readiness — anonymized benchmarking included).
- Commercial strategy toolkits: pricing clauses templates, channel segmentation playbooks, and packaging/brand premiuming strategies.
- M&A and investment screening framework: target prioritization and quick‑win integration checklists tailored to bagged salt economics.
- Regulatory compliance checklist and mitigation playbook for brine/runoff, storage and transport.
Note: to preserve the strategic value of the report and align with client confidentiality, this primer omits the granular regional and application splits and the full numeric segmentation tables included in the paid study. Those details, along with the interactive model, are available on the report page.
Immediate actions for Q1 2026
- Update 2026 procurement strategy using a 4.0% CAGR baseline and run upside/downside scenarios for winter severity.
- Negotiate capacity reservation or indexed pricing for peak seasons; include force majeure and allocation clauses informed by our scenario outputs.
- Inventory optimization: blend safety stock with seasonal forward buys to balance cash and availability risks.
- ESG and compliance: initiate supplier audits for runoff and storage controls; prioritize partners with demonstrable mitigation programs.
- Shortlist M&A or partnering targets using our supplier scorecard to close geographic or channel gaps.
Conclusion & next step
The bagged salt market for 2026 is not a single homogeneous opportunity — it is a portfolio of interrelated plays across seasonality, geography and end‑use. PW Consulting’s full report equips leaders with data, scenarios and executable playbooks to convert the market’s moderate growth and stability into predictable commercial advantage. For access to the complete dataset, interactive forecast model, and the detailed segment intelligence omitted here, please visit the full report page or contact PW Consulting for a briefing and model walkthrough.
For detailed analysis of this topic, please visit the official page: Bagged Salt Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Carpet tiles market to reach USD 20.53M by 2032 at 6.4% CAGR
By pmarketresearch, 2026-07-13
Carpet Tiles Market 2026: Strategic Preview for Decision-Makers
As the global built environment navigates economic recalibration, sustainability mandates and evolving specification preferences, carpet tiles have re-emerged as a strategic material choice for owners, designers and manufacturers alike. PW Consulting’s new Carpet Tiles Market study (base year 2025, forecast 2026–2032) synthesizes five years of market movement and a seven-year outlook to give executives the actionable intelligence they need for decisive 2026 planning.
Carpet Tiles Market
Market snapshot — pacing and scale
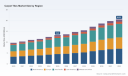
The carpet tiles market has demonstrated steady expansion through the early 2020s, growing from approximately USD 9.8 million in 2020 to USD 13.3 million in 2025. Our forecast, built on demand drivers, cost trajectories and adoption curves, anticipates growth at a compound annual growth rate of roughly 6.4% across 2026–2032, reaching an estimated USD 20.5 million by 2032. Market concentration is meaningful: the three largest players control a majority share (CR3 ~55%), and the top five account for roughly 70% of global value — a structure that shapes competitive dynamics, margin pools and channel negotiation power.
Carpet Tiles Market
Why this matters for 2026 strategic decisions
For corporate leaders planning capital allocation, product roadmaps, or go-to-market moves in 2026, three truths emerge from our analysis:
Carpet Tiles Market
- Sustainability is table stakes, but execution divides winners from laggards. Clients and procurement policies increasingly specify environmental performance as a primary criterion. Companies that translate sustainability commitments into verifiable product attributes, lifecycle transparency and circular service models gain price resilience and specification leadership.
- Modularity and installation economics drive commercial demand. The advantages of modular carpet tiles for flexibility, repairability and phased fit-outs mean that product design and service propositions (replacements, take-back, refurbishment) can become primary differentiators.
- Consolidation and channel control create strategic openings for niche innovators. With a concentrated supplier base, selective M&A and focused partnerships — especially in sustainability-certified, design-forward niches — offer routes to rapid scale or to defensible premium positioning.
From insight to action: where to focus in 2026
- Product strategy — design, materials, and service bundles. Prioritize carpet tile collections that balance design differentiation with modularity and reparability. Invest in validated recycled content and low-emission systems, and design commercial-grade warranty/service bundles that monetize long-term maintenance and refurbishment.
- Supply chain — localization and duty engineering. Reassess sourcing strategies in light of tariff shifts and trade agreements. The CUSMA/USMCA rules of origin create a cost advantage for qualifying North American manufactured tiles intended for intra-regional trade; consider nearshoring or regional platform strategies to secure margin and delivery velocity.
- Pricing and commercial policy. With manufacturers passing through input costs and tariffs selectively, 2026 will be a year where smart price architecture (value-based pricing for sustainability and lifecycle services) beats uniform cost-plus approaches.
- M&A and partnerships. Pursue tuck-ins that add circular capabilities (recycling, take-back), or creative brands with strong design credentials to access new specification channels without undermining incumbent relationships.
- Specification & channel influence. Strengthen relationships with specifiers, national contractors and workplace consultants. A small number of decisions (large commercial projects, hospitality roll-outs) can move volumes disproportionately given the market’s concentration profile.
Competitive landscape — what the leaders are doing (and why it matters)
The competitive map is populated by established global flooring groups and focused specialists. What binds the leaders is a dual emphasis on product breadth and sustainability credibility; distinctions appear in route-to-market, R&D depth, and service-oriented business models.
- Interface, Inc. (Atlanta) continues to position itself at the intersection of design and sustainability. Recent launches underscore a strategy of marrying design narratives with low-carbon credentials — a play that supports premium positioning in commercial interiors and corporate procurement lists. Interface’s long-standing PFAS-free policy and carbon-focused commitments give them specification traction with sustainability-driven buyers.
- Mohawk Industries, Inc. (Dalton) leverages scale and a multi-brand approach to serve diverse channels. Mohawk’s engagement in design showcases signals efforts to drive emotional and tactile differentiation — an effective route to defend commercial projects where aesthetics and occupant experience influence supplier selection.
- Shaw Industries Group (Dalton) deploys product refresh cycles and sustainability messaging to remain competitive. Their portfolio refresh and event-led product launches indicate continued investment in design-led specification activity.
- Milliken & Company (LaGrange) focuses on performance and design-led modular solutions for institutional and commercial segments. Their recent collection launches reflect a strategy of targeted creativity to capture projects where brand-driven selection matters.
- Tarkett, Forbo, and European specialists (e.g., Fletco, BLOQ). These companies increasingly compete on regenerative materials and production transparency. Fletco’s 100% CO2-neutral production and use of regenerated yarns exemplify an industrial model that appeals to project teams targeting ambitious sustainability targets.
- Regional manufacturers and integrated players (e.g., Al Abdullatif). Fully integrated platforms in certain regions combine price control with tailored local go-to-market reach — a powerful combination where specification preferences include local content and rapid delivery.
Recent product activity — from Interface’s design-led launches to Milliken and Shaw’s refreshed lines and Fletco’s regenerated-yarn collections — reveals an industry where innovation is incremental but decisive. Expect successful products to combine tactile appeal, installation efficiencies and verifiable sustainability metrics.
Regulatory and cost tailwinds — practical implications
- Chemical and product regulation: The industry-wide removal of PFAS from U.S. carpet production since 2019 is now a baseline expectation for many specifiers. Suppliers without credible product chemistry transparency risk exclusion from public and corporate bids.
- Tariffs and trade policy: Tariff adjustments on imported hard-surface and decorative products have introduced price inflation in certain channels; some manufacturers implemented price increases in 2025. Product sourcing strategies must therefore be stress-tested against further tariff volatility.
- Trade advantages: Duty rules under CUSMA/USMCA can be a competitive lever for North American manufacturers exporting regionally — a structural edge for those who can certify origin and manage compliance efficiently.
- Energy and production footprint: Claims of CO2-neutral production, as demonstrated by some European manufacturers, are increasingly material in public and large corporate procurement. Investing in verifiable renewable-energy sourcing or procurement partnerships can unlock specification wins and allow premium pricing.
Risk matrix for 2026 decision-makers
- Execution risk: Failure to operationalize sustainability claims (traceability, take-back, recycled content verification) will erode credibility rapidly.
- Channel concentration: Heavy dependence on a small number of commercial specification channels increases exposure to project cyclicality and competitive displacement.
- Commodity & labor cost volatility: Raw material swings and regional labor cost inflation can compress margins unless offset by price discipline or local manufacturing adjustments.
- Regulatory surprises: Unanticipated chemical or trade policy changes could accelerate product reformulation costs or reconfigure supply chains.
What PW Consulting’s Carpet Tiles report delivers (practical, usable outputs)
We designed this study to be directly operational for 2026 planning cycles. Highlights include:
- Market-sizing and forward scenarios (base year 2025; forecast 2026–2032) with sensitivity runs for demand, price and tariff permutations.
- Competitive playbooks that translate public moves (product launches, sustainability claims, showroom strategies) into tactical responses for manufacturers and distributors.
- Supply-chain heatmap and sourcing decision framework that integrates duty engineering, freight/delivery risk and regional labor considerations.
- Sustainability commercialization toolkit: how to validate claims, design circular services, and structure warranty and take-back economics.
- Go-to-market architectures for incumbents and entrants: segmentation of channels by specification influence, procurement behavior and lifecycle expectations (note: detailed subsegment market shares and unit economics are reserved for subscribers).
- Deal and partnership checklist for M&A, joint ventures and licensing arrangements that accelerate capability acquisition while preserving margin discipline.
How to use this research in 90 days
- Week 1–3: Align executive priorities using our scenario outputs — set price guardrails, sustainability targets and channel investment limits.
- Week 4–8: Stress-test your supply chain and sourcing plan against tariff and origin scenarios using our supply-chain heatmap.
- Week 9–12: Deploy the sustainability commercialization toolkit to validate product claims and design an initial take-back pilot for a single product line or market.
Closing perspective
Carpet tiles sit at an intersection of design, operational flexibility and environmental ambition. The coming 12–18 months will reward organizations that convert sustainability commitments into verifiable product systems, that retool supply chains to neutralize tariff and freight exposure, and that lean into modular service economics that project owners now prize. PW Consulting’s Carpet Tiles Market study gives leaders a pragmatic roadmap — from scenario planning to market-winning product and channel plays — to make 2026 a year of strategic clarity rather than tactical reaction.
For companies preparing capital budgets, product roadmaps or acquisition strategies in 2026, the study provides the quantified scenarios and executable tools required to prioritize investment and to defend or expand specification share. For full subsegment detail, supplier-by-supplier share analysis, and the proprietary worksheets that underlie our scenario modelling, please refer to the full PW Consulting report.
For detailed analysis of this topic, please visit the official page: Carpet Tiles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Online Gambling Game Software Market to Hit USD 15,729.8M by 2032 (CAGR 10.29%)
By pmarketresearch, 2026-07-13
Online Gambling Game Software Market — Strategic Briefing for 2026 Decisions
Executive snapshot
As organizations plan capital allocation, licensing, and product roadmaps for 2026, the Online Gambling Game Software market presents a high-growth yet nuanced opportunity. PW Consulting’s latest market model (base year 2025) estimates the global market at approximately 7,891.72 (USD Million) and projects compound annual growth of 10.29% through our forecast horizon (2026–2032). Under central assumptions the market nearly doubles across the forecast window, underscoring expanding operator demand for platform-level capabilities, live and RNG content, sportsbook integrations, and regulated-market compliance solutions.
Online Gambling Game Software Market
Why this matters for 2026 strategic decisions
-
Investment timing: A sustained double-digit CAGR signals attractive returns for platform and content investments, but speed-to-market and regulatory readiness are primary determinants of early mover advantages.
Online Gambling Game Software Market -
M&A and partnerships: The market’s moderate concentration (CR3 ~28.5%, CR5 ~42.3%) suggests meaningful opportunity for consolidation and value creation via bolt-on acquisitions or exclusive content/licensing deals.
Online Gambling Game Software Market -
Regulatory positioning: Certification and region-specific licensing are gating factors — which influences whether to scale organically or enter via local partners or turn-key offerings.
-
Technology bets: Providers, operators and investors must balance investments across aggregation APIs, live-studio infrastructure, prediction markets, and AI-driven compliance to secure differentiated, compliant propositions.
Market dynamics — what is driving change
-
Content aggregation and single-API economics: Aggregators and platform vendors that expose large game libraries and multi-vertical capabilities via a single API reduce operator integration friction and accelerate customer acquisition.
-
Live and immersive experiences: Live dealer technology remains a core growth vector — it drives engagement and retention for higher-value customers and raises vendor switching costs when paired with proprietary studios and branded tables.
-
New verticals — prediction markets and sweepstakes: Providers are launching fixed-odds prediction platforms and sweepstakes solutions to create adjacent revenue lines and to navigate market-access constraints in select jurisdictions.
-
Regulatory and certification burden: GLI-19/GLI-33 and similar accreditations, plus ISO and payments compliance, are prerequisites for regulated-market entry. Successful vendors embed these certifications into product roadmaps to reduce operator friction.
-
Rising operational costs: Labor requirements for AI-driven compliance automation, cybersecurity, and data-center operations are increasing total cost of ownership for platform vendors and operators alike, driving an emphasis on cost-efficient, cloud-native architectures.
-
Responsible gaming and reimbursement frameworks: Embedded RG tools (self-exclusion, spend limits, identity verification) are now recast as both compliance hygiene and brand risk mitigation — their absence is a material business risk in regulated markets.
Competitive landscape — strategic profiles and implications
The market balances a mix of content specialists, full-stack platform vendors, and niche innovators. Key players exemplify the strategic archetypes operators will face when selecting partners or targets:
-
SOFTSWISS (Belarus) — Platform & aggregation specialist: SOFTSWISS offers a broad iGaming stack including a casino platform, game aggregation (300+ studios and a vast mobile-friendly catalog via single API), sportsbook and prediction market capabilities. Their dual focus on turnkey deployments and compliance certifications (GLI, ISO) positions them as a rapid-deployment partner for operators pursuing both fiat and crypto payment strategies.
-
EveryMatrix (Cyprus) — API-first, omnichannel integrator: With a product suite designed around CasinoEngine and unified sports/casino APIs, EveryMatrix emphasizes regulated-market readiness, responsible gaming tooling, and omnichannel operator integration. Recent licensing approvals in jurisdictions such as Alberta demonstrate a pragmatic approach to provincial regulatory complexity — a model worth emulating for vendors seeking global scale.
-
Evolution Gaming (Malta) — Live casino dominator: Evolution’s core competency is immersive live dealer experiences and proprietary studios. Their vertical integration strategy (studio ownership, branded content) creates high engagement and strong operator retention dynamics — a useful playbook for vendors aiming to monetize high-LTV player cohorts.
-
Pragmatic Play (Gibraltar) — Content-first, API-enabled supplier: A leader in cross-vertical content (slots, live casino, virtual sports and sportsbook via single API), Pragmatic’s approach demonstrates the value of content breadth combined with regulatory-compliant deployment across multiple jurisdictions.
Strategic implication: operators and investors must choose their counterparty archetype based on whether they prioritize speed-to-market, content exclusivity, regulatory depth, or infrastructure control. The mid-market concentration metrics point toward a landscape where well-executed partnerships and targeted acquisitions create scalable differentiation.
Notable recent moves (signposts for 2026)
-
New product launches in prediction markets and sweepstakes highlight vendor attempts to capture alternative demand streams and to navigate licensing constraints in specific regions.
-
Extended content licensing and partnership renewals (table games, live content) show that exclusive or semi-exclusive content deals remain a key retention instrument for operators.
-
Targeted licensing approvals in Canadian provinces and similar jurisdictions demonstrate the commercial value of localized regulatory strategies.
-
Industry showcases and trade events continue to be effective channels for vendors to communicate product breadth beyond their core platforms — useful for both client acquisition and talent recruitment.
Operational playbook for 2026 — five priorities
-
Certification-first product roadmaps: Integrate GLI-19/GLI-33 and relevant ISO standards into product development lifecycles to minimize time-to-revenue in regulated markets.
-
API & aggregation strategy: Decide whether to build, buy, or partner for aggregation and single-API exposure — the correct choice depends on target customer segments and willingness to bear integration costs.
-
Compliance automation and cybersecurity: Invest in AI-enabled monitoring, identity verification, and secure hosting — rising labor and data-center costs make efficiency a competitive advantage.
-
Licensing and market-entry sequencing: Use a jurisdictional scorecard to prioritize licensing investments (based on market size potential, entry complexity, and partner availability) and to design roll-out phasing.
-
Monetization & retention engineering: Combine live/dealer experiences, loyalty mechanics, and CRM integration to lift ARPU and extend customer lifetime value.
What PW Consulting’s full report delivers — practical, actionable elements
PW Consulting’s comprehensive market study is structured to support board-level decisions and execution plans. Highlights of the deliverables include:
-
Time-series market sizing (historical 2020–2025 and modeled 2026–2032 forecasts) expressed in USD Million and aligned to multiple scenarios.
-
Regulatory and certification matrix mapped to major jurisdictions, clarifying go-to-market constraints and time-to-license implications.
-
Vendor scorecards and an M&A playbook that assess strategic fit, tech stack compatibility, and integration risk for potential targets or partners.
-
Commercial templates: go-to-market checklists, commercial model benchmarks, and pricing sensitivity analyses to accelerate operator and vendor negotiations.
-
Operational guidance on technology architecture choices — cloud vs. dedicated hosting, live-studio scale planning, and AI-driven compliance tooling.
-
Scenario-based revenue and cost models that allow CFOs to stress-test investment cases under regulatory delays, accelerated uptake, or competitive price pressure.
Note: this briefing intentionally omits granular subsegment and regional breakdowns. Those precise tables and interactive datasets are presented in the full report to preserve commercial sensitivity while enabling executable decisions.
How to use these insights in the next 90 days
-
Immediate actions for operators: finalize a prioritized licensing roadmap, pilot a single-API aggregator integration, and begin RG tool audits against local regulatory checklists.
-
Immediate actions for vendors: validate certification timelines for target markets, run a cost-to-serve assessment for live studio scale-up, and pilot predictive compliance models to reduce labor intensity.
-
For investors and M&A teams: deploy the PW Consulting vendor scorecard on shortlisted targets and run fast technical and regulatory due diligence prior to term-sheet execution.
Closing — positioning for upside while managing regulatory and operational risk
2026 is a year where execution quality will separate winners from the pack. The market’s growth trajectory (10.29% CAGR; base year 2025 sizing at ~7,891.72 USD Million with a materially larger market by 2032) creates a compelling backdrop, but regulatory rigor, certification discipline and operational efficiency will define sustainable value. PW Consulting’s report provides the playbook to convert market opportunity into repeatable revenue while managing the unique risks of the online gambling software ecosystem.
For access to the full datasets, granular segmentation, and vendor scorecards referenced here, please consult the PW Consulting source page or contact our advisory team to schedule a tailored briefing.
For detailed analysis of this topic, please visit the official page: Online Gambling Game Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Visitor Management Systems to Reach USD 263.6M by 2032 at 6.5% CAGR
By pmarketresearch, 2026-07-13
Visitor Management System Market — Strategic Brief for 2026 Decision-Makers
As organizations prioritize secure, compliant, and frictionless access in an era of hybrid work and heightened regulatory scrutiny, Visitor Management Systems (VMS) have moved from a niche facility function to a core component of enterprise security and operational efficiency. PW Consulting’s latest market study — covering historical performance from 2020 to 2025 (base year 2025) and forward-looking projections through 2032 — quantifies that transition and translates it into actionable choices for enterprise leaders, security architects, and procurement teams planning 2026 investments.
Visitor Management System Market
Market snapshot (what the numbers tell you)
-
Momentum: The VMS market expanded from roughly USD 120.5 million in 2020 to USD 170.0 million in 2025, reflecting accelerated adoption across commercial, regulated, and high-volume public venues.
Visitor Management System Market -
Outlook: Under current technology and regulatory trajectories, our forecast anticipates continued growth through the 2026–2032 period at a mid-single-digit compound annual growth rate (CAGR) of approximately 6.5%, reaching a materially larger market by 2032.
Visitor Management System Market -
Structure: Despite headline growth, market concentration remains low compared with many adjacent security segments — the leading vendors together account for a relatively modest share of total sales, indicating ample room for new entrants, vertical specialists, and niche consolidators.
Why this report matters to 2026 strategy
-
Investment prioritization: Security and workplace teams face competing capital and operating priorities. The report converts macro trends and vendor capabilities into an investment scorecard that helps you decide whether to prioritize cloud-native VMS upgrades, replace legacy on-premise systems, or pursue a phased hybrid approach tied to access control modernization.
-
Procurement clarity: With subscription and service models now the norm, procurement must evaluate total cost of ownership beyond sticker price — including compliance, integration, data retention, and labor offsets. Our analysis includes an operational breakeven framework designed for 2026 contracting cycles.
-
Regulatory alignment: New and evolving data protection requirements are an immediate factor. The study synthesizes GDPR, HIPAA, and common information security frameworks (e.g., ISO 27001) into compliance checklists and contractual language to reduce implementation risk.
Key growth vectors and what they imply for enterprise buyers
-
Cloud migration as the default: Buyers are shifting to cloud-first VMS offerings for scalability and rapid feature delivery. Cloud models eliminate the capex and maintenance burdens of server-based deployments and embed encryption, role-based access, and audit logs into standard packages — a strong advantage for organizations with dispersed sites or fluctuating visitor volumes.
-
Integration-driven value: The most compelling VMS deployments are those integrated tightly with access control, SSO, identity providers, and building automation. Integration reduces manual intervention, shortens visitor throughput, and unlocks advanced use cases such as conditional access based on credentials or watchlist hits.
-
Regulatory tailwinds: Data minimization, retention controls, and breach liability considerations are increasing demand for VMS platforms that provide robust data governance and auditable trails. For healthcare and other regulated verticals, HIPAA-grade controls and watchlist screening are often mandatory features, not optional add-ons.
-
Operational ROI: Labor cost pressures continue to make automated check-in and self-service kiosks attractive in high-volume environments. Our field models show that, depending on visitor density and staffing models, VMS automation can deliver measurable personnel savings within months to a few years, accelerating ROI for enterprise deployments.
Risk map: what keeps us up at night
-
Data exposure risk: Paper logs and unmanaged spreadsheets remain a vulnerability in many organizations. GDPR-style rules on data minimization and retention mean fines and reputational damage are real outcomes if personal data is mishandled.
-
Fragmentation & integration complexity: The market’s low concentration means many buyers must evaluate a disparate set of vendors with varying API maturity and integration footprints. Without a clear integration plan, projects commonly overrun timelines and budget.
-
Vendor lock and portability: Proprietary data formats or limited export capabilities create lock-in. Procurement teams in 2026 must insist on standardized export and interoperability clauses, especially when contracts span multiple sites or geographies.
Competitive landscape — how to read vendor strengths
The VMS vendor ecosystem is diverse, ranging from cloud-native specialists to incumbent security platform providers. Our competitive benchmarking in the full report evaluates vendors across five dimensions: product depth, integration breadth, compliance posture, enterprise scalability, and service delivery. Highlights from core players we track:
-
Envoy — A cloud-first platform emphasizing streamlined visitor registration, access-control integrations, and workplace security features aimed at modern enterprises. Envoy’s product strategy focuses on user experience, rapid integrations, and ecosystem partnerships that support hybrid workplaces.
-
FacilityOS — Positioned as an AI-enabled entrant with a module-centric approach for high-volume, regulated sites. Its pre-screening and automation capabilities are tailored for environments such as pharmaceutical manufacturing where throughput and compliance are tightly coupled.
-
MRI Software (OnLocation) — An established enterprise vendor offering screening, contractor tracking, and analytics designed for corporate and manufacturing footprints where IP protection and complex contractor flows are priorities.
-
Avigilon — A security-suite vendor integrating visitor capabilities into a broader access and video ecosystem. Avigilon’s strategy favors organizations seeking unified security operations and centralized credentialing across cameras and access points.
-
Acre Security — Focused on enterprise visitor profiles, digital badging, and compliance controls in regulated verticals. Acre’s value proposition is strong where physical security and regulatory evidence are mission-critical.
-
HybridHero, Sign In App, Lobbytrack — These vendors illustrate the breadth of the market, from desk-booking and occupancy-aware platforms to combined on-prem and cloud offerings. They typically appeal to customers prioritizing specific workplace workflows or localized deployment models.
Recent market movements underscore consolidation and platform convergence. Notable examples include Brivo’s integration efforts with leading cloud vendors and strategic acquisitions that fold visitor capabilities into broader security portfolios. These moves increase the strategic importance of integration compatibility when selecting a partner in 2026.
What the full report contains (practical deliverables)
-
Detailed market sizing and forecast models covering historical (2020–2025) and forecast (2026–2032) horizons, with scenario analysis for baseline, accelerated adoption, and disruption cases.
-
Vendor scorecards and use-case fit matrices to match platform capabilities to buyer requirements by vertical and site profile (scaled to enterprise complexity and compliance needs).
-
Procurement playbook: RFP templates, critical compliance clauses (GDPR/HIPAA/ISO alignment), integration checklists, and standard SLAs to negotiate from a position of knowledge.
-
Implementation playbook: phased rollout roadmaps, change management templates, KPIs for verifying labor and security ROI, and integration wiring diagrams for common access control and identity platforms.
-
Risk register and mitigation framework focused on data governance, supply chain (hardware kiosks), and escalation protocols for watchlist and access incidents.
-
Operational cost models and sensitivity analysis incorporating per-location subscription ranges, expected labor offsets, and maintenance differentials to support capital planning.
How to use this intelligence in 2026
-
Security leaders: Use the vendor scorecards to build vendor shortlists that align to your integration roadmap and compliance profile. Prioritize pilots that validate API maturity and data export capabilities.
-
Finance and procurement: Apply the TCO models to subscription negotiations, and insist on contractual provisions for data portability and post-contract transition support to protect against vendor lock-in.
-
Facilities and workplace ops: Leverage the implementation playbook for phased rollouts that prioritize high-density and regulated sites first, where ROI and compliance uplift are most immediate.
-
Board and risk committees: Incorporate the compliance checklists and breach-risk quantification into enterprise risk assessments to frame investment decisions in the context of potential regulatory penalties and reputational exposure.
Final note — the trailer principle
This overview provides the strategic contours and operational levers that matter in 2026, but it intentionally omits the granular region-by-region and application-by-application splits and the full vendor scoring matrix that enterprise teams require to execute procurement and rollout. PW Consulting’s complete report contains those controlled, actionable details — including scorecards, contractual language, and downloadable financial models — that translate insight into purchase decisions and implementation plans.
For decision-makers preparing budgets, negotiating contracts, or designing pilot programs in 2026, the right balance of competitive benchmarking, compliance guardrails, and integration clarity will determine whether VMS deployments are strategic enablers or costly, underused systems. Our study equips you to make that distinction with confidence.
For detailed analysis of this topic, please visit the official page: Visitor Management System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: XRF Spectrometer Market Set for 6.98% CAGR (2026–2032)
By pmarketresearch, 2026-07-13
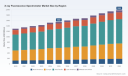
X-ray Fluorescence Spectrometer Market: Strategic Imperatives for 2026 Decision-Makers
Executive preview
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a focused preview of our new X-ray Fluorescence (XRF) Spectrometer Market study. This briefing is written for corporate strategy teams, procurement leaders, product managers, and M&A executives who must make high-stakes decisions in 2026 informed by robust commercial and technical insight. The aim here is to surface the study’s strategic value and practical takeaways while preserving the detailed, segment-level intelligence that drives competitive advantage — that material is reserved for the full report.
X-ray Fluorescence Spectrometer Market
Why this research matters in 2026
The XRF spectrometer market is in an established growth phase driven by ongoing industrial quality control demands, environmental regulation enforcement, and expanding field-testing use cases. PW Consulting’s market model — grounded on a 2025 base year with historical analysis from 2020–2025 and a forward-looking forecast covering 2026–2032 — quantifies this trajectory. The market expanded from roughly USD 1.3 billion in 2020 to about USD 1.55 billion in 2025, and our projections place it at approximately USD 1.98 billion by 2032, implying a compound annual growth rate (CAGR) of roughly 6.98% over the forecast window.
X-ray Fluorescence Spectrometer Market
Those headline numbers matter because they: (1) validate continued vendor investment and product refresh cycles; (2) underpin capex planning for industrial and laboratory buyers; and (3) signal an expanding aftermarket opportunity for services, consumables, and software-enabled analytics.
X-ray Fluorescence Spectrometer Market
What the full report delivers — operationally useful content
- Comprehensive market sizing and a transparent forecasting model (base year 2025; historical 2020–2025; forecast 2026–2032) with sensitivity analysis for macroeconomic and technology adoption scenarios.
- Segment-level demand drivers and end-user adoption pathways (by instrument type, application vertical, and geography) — note: segment breakdowns are included in the full report to support procurement and GTM decisions.
- Vendor landscaping with strategic profiles, product positioning maps, technology differentiation matrices, and a pragmatic vendor selection checklist for bench vs. handheld deployments.
- CapEx and total cost of ownership (TCO) frameworks that incorporate purchase cost ranges, service contracts, consumables, and lifecycle replacement timing.
- Use-case playbooks for environmental testing, mining & metals, pharmaceutical quality control, and industrial manufacturing, including measurement uncertainty considerations and sample-preparation trade-offs.
- M&A and partnership screening criteria, including a prioritized target list and a short due-diligence template for technology, go-to-market, and aftermarket synergies.
- An actionable supplier negotiation toolkit (including warranty and calibration service clauses) and a procurement scorecard for enterprise rollouts.
Key strategic implications for 2026 decisions
The following implications synthesize the report’s primary findings into immediate actions and decision frameworks:
- CapEx and procurement timing: With instrument prices spanning a broad range, buyers should align procurement with a 24–36 month roadmap that balances new product introductions and internal depreciation cycles. Our TCO framework models show that service and consumable economics materially affect lifecycle costs; decisions should therefore be vendor-agnostic at the purchase stage but service-aware in contracting.
- Fleet rationalization: Organizations operating mixed fleets of benchtop and portable XRF devices can often reduce cost-per-test by standardizing on fewer platforms while leveraging handhelds for field triage. The qualitative benefits of portability (reduced sampling time, field decisioning) must be balanced against laboratory precision needs.
- Aftermarket monetization: The projected market growth creates room for differentiated service models — subscription-based calibration, predictive maintenance tied to instrument telemetry, and consumable bundles. Vendors and service providers that convert installed bases into recurring revenue will capture disproportionate value.
- Regulatory and compliance risk: XRF instruments are subject to radiation-protection requirements and national regulations. Buyers must factor compliance costs (training, shielding, certifications) into procurement and site planning budgets.
- Product roadmap sensitivity: New model introductions and incremental improvements in detector technology or software analytics can influence replacement cycles. Procurement should include clauses to mitigate obsolescence risk when multiyear rollouts are planned.
Competitive landscape — how incumbents are positioning
The market remains moderately fragmented with leading vendors focusing on differentiated product stacks, service models, and niche verticals. Our review highlights several strategic archetypes and the practical implications for buyers and partners:
- SPECTRO (Germany): Strong in high-precision benchtop systems and established pharma use cases. SPECTRO emphasizes instrument accuracy and application-specific attachments — a good supplier where laboratory-grade repeatability is prioritized.
- Malvern Panalytical (UK): Offers a mix of benchtop and handheld solutions with a notable portfolio for powder and material analysis. Their strength is in integrated workflows from sample presentation to analytics — attractive for pharma and advanced materials labs.
- HORIBA (Japan): Competes on analytical robustness with solutions targeting both pharmaceutical and clinical materials testing. Their strategy blends instrumentation with ancillary measurement services.
- Thermo Fisher Scientific (USA): A prominent player in the handheld segment with the Niton series and a strong global service network — suited for enterprises prioritizing field analytics and rapid deployment.
- Rigaku (Japan): Positioning centers on benchtop systems for industrial QC and pharma labs; they emphasize ruggedness and integration into manufacturing lines.
- Hitachi High‑Tech (Japan): Bridges handheld and benchtop categories with a focus on QA workflows for regulated industries.
Market concentration metrics in the study indicate modest aggregation among the top vendors — a competitive environment that favours specialization and strong service ecosystems over sheer scale. Recent product moves underscore continuing innovation and renewal: Shimadzu’s portfolio addition in late 2025, Thermo Fisher’s handheld launch in January 2026, and Rigaku’s NEX QC II benchtop series introduced in March 2026 all speak to active R&D cycles and an urgent cadence of product refreshes.
Operational realities and hidden costs
- Consumables and operating expense: Several analyzers require consumables and periodic component replacement (e.g., X-ray tubes, calibration standards, sample cups), which can materially increase operating costs over a device’s lifetime — buyers must model these costs rather than rely solely on headline purchase prices.
- CapEx variability: Instruments can range from modestly priced handhelds to high-end benchtops costing significantly more; this range requires tailored financing and depreciation strategies for enterprises with broad testing needs.
- Service and calibration: Contract scope (on-site vs. depot, preventive maintenance frequency) materially impacts uptime and measurement traceability — a critical factor for regulated industries like pharmaceuticals.
90 / 180 / 360‑day playbook for executive teams
- 90 days: Run a rapid inventory of existing XRF assets, capture warranty and service-contract end dates, and initiate a TCO assessment across candidate vendors using our report’s templates.
- 180 days: Pilot one or two newer handheld and benchtop platforms in representative sites, negotiate multi‑site service agreements with clear performance SLAs, and finalize standard operating procedures that address radiation safety and calibration cadence.
- 360 days: Decide on scale investments vs. incremental refresh based on pilot outcomes, lock in long-term consumable pricing where possible, and consider strategic partnerships or tuck‑in acquisitions to close capability gaps in analytics or aftermarket services.
What we intentionally withhold in this preview (and why)
To preserve the commercial value of the full study and to support proprietary decision-making, this preview does not disclose the detailed splits by region, instrument type, or end application; nor does it include the full vendor scoring matrix, contract templates, or market-by-country tables. These elements are included in the full PW Consulting report because they are the actionable intelligence buyers and investors use to negotiate contracts, size opportunity windows, and prioritize M&A targets.
- Detailed regional and application-level demand profiles (available in the full report).
- Vendor-by-product performance scores and scoring methodology.
- Granular price curves per model and manufacturer.
- Primary interview transcripts and confidential supplier feedback.
Methodology and evidence base
The study combines a bottom-up market-model calibrated with primary interviews across OEMs, channel partners, and end users, together with a top-down validation using historical shipment and revenue series. Key modeling features include scenario analysis for adoption curves, sensitivity to commodity cycles (relevant to mining & metals demand), and regulatory shock scenarios affecting deployment lead times. The base year is 2025, historical coverage spans 2020–2025, and forecasts extend from 2026 through 2032; all monetary figures are presented in USD (Million).
Conclusion — the strategic value of the full report
For decision-makers in 2026, the PW Consulting XRF market study is designed to convert market data into executable choices: when to buy, what to buy, which vendor to partner with, and how to monetize installed bases. The market’s healthy near- and mid-term growth (with a roughly 6.98% CAGR in our forecast) creates both opportunity and urgency for companies seeking to defend or expand market positions. If your 2026 plans include capital allocation to testing instrumentation, a GTM pivot for analytical services, or M&A in adjacent instrumentation and analytics, the full report delivers the calibrated intelligence and operational tools you will need to act with confidence.
To access the complete report, vendor matrices, and downloadable TCO models, please visit the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: X-ray Fluorescence Spectrometer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Emergency Transport Ventilators Market to Top USD 1,046.95M in 2025 (5.36% CAGR)
By pmarketresearch, 2026-07-13
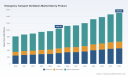
Emergency Transport Ventilators Market — Strategic Briefing for 2026 Decision-Makers
As health systems, emergency medical services (EMS), and life‑science suppliers move from pandemic crisis response to durable readiness, emergency transport ventilators have shifted from episodic procurement items to strategic assets. PW Consulting’s latest market study — anchored on a 2025 base year and projecting through 2032 — synthesizes a seven‑year forecast, competitive positioning, regulatory dynamics, and actionable commercialization playbooks designed to inform board‑level and business unit decisions in 2026.
Emergency Transport Ventilators Market
Why this study matters in 2026
-
Market momentum is measurable and persistent. Our modeling shows the global emergency transport ventilator market expanded steadily through 2020–2025 and is forecast to continue growing in the 2026–2032 horizon at a compound annual growth rate (CAGR) of 5.36% (USD, revenue in Millions). This trajectory reflects durable demand from hospital networks, organized EMS, military and aeromedical operators, and an expanding remit for pre‑hospital critical care.
Emergency Transport Ventilators Market -
Strategic inflection points are clustered in 2026. Buyers will rethink capex allocation, suppliers will operationalize product roadmaps initiated during crisis years, and regulators and payers will increasingly shape procurement through standards, reimbursement structures, and clinical outcome requirements.
Emergency Transport Ventilators Market -
Decision relevance: for product leaders, the study translates market growth into prioritized feature roadmaps and certification timing; for commercial leaders, it identifies where to invest sales coverage and where to pursue partnerships; and for corporate development teams, it highlights consolidation vectors consistent with current market concentration.
Macro picture: trajectory, concentration, and tail risks
Using 2025 as the analytical baseline, the market registers meaningful scale and resiliency. After multi‑year recovery and modernization of EMS fleets, our 2026 forecast continues expansion toward the 2032 horizon. Market concentration is moderate and actionable: the top three suppliers capture a plurality of share while the top five control a clear majority — a structure that creates both competitive barriers and selective acquisition opportunities for challengers and incumbents alike.
These structural characteristics produce two practical effects for 2026 planning. First, established manufacturers retain advantage through installed base, service networks, and certifications that matter to air and ground transport operators. Second, there is still room for focused entrants that can pair differentiated technology with targeted distribution in underpenetrated segments or geographies.
Key industry dynamics shaping choices in 2026
-
Standards and regulatory gating. International standards that define safety and performance for EMS ventilators are now a baseline buyer requirement; compliance timelines and submission strategies (including 510(k) pathways where relevant) must be mapped into product roadmaps early to avoid launch delays.
-
Reimbursement and procurement economics. Reimbursement frameworks and hospital capital allocation continue to influence buyer willingness to invest in higher‑capability, higher‑priced transport ventilators. Buyers increasingly evaluate total cost of ownership, clinical outcomes, and interoperability with ICU workflows.
-
Supply‑chain and cost pressure. Medical device manufacturing has experienced step‑change cost pressures in recent years; procurement teams are tightening supplier qualification criteria and favoring partners that demonstrate resilient sourcing, predictable lead times, and cost containment strategies.
-
Certifications and operational approvals matter. Aviation and ambulance certifications, as well as proven performance in extreme‑environment and aeromedical contexts, materially affect competitive positioning for devices targeting air and military transport use cases.
Competitive landscape — what executives need to know
The market is served by a mix of global OEMs with broad acute‑care portfolios and specialist vendors focused on portable, mission‑critical devices. Leading players differentiate along a few predictable dimensions: clinical capability (ICU‑grade modes), mobility and robustness (battery, weight, environmental certifications), service and lifecycle support, and regulatory footprint. PW Consulting’s report profiles the full competitive set and provides strategic implications for each competitive archetype.
-
ZOLL Medical Corporation: recognized for robust portable platforms designed for EMS and aeromedical transport. Strengths include strong brand recognition among first responders and deep integration with emergency care ecosystems.
-
Hamilton Medical AG: positions its flagship transport ventilator with ICU‑level functionality for ground, air and water transport — a preferred choice where clinical parity with hospital ventilators is a procurement requirement.
-
WEINMANN and Dräger: European incumbents that combine reliability with extensive service networks; competitive advantages revolve around local approvals and after‑sales support for EMS providers.
-
Mindray, Comen, Amoul and other China‑based manufacturers: offer competitive value propositions and have advanced into certification for aviation and ambulance markets — creating options for cost‑sensitive buyers and emerging market tenders.
-
Specialist innovators (O‑Two, Impact Instrumentation, Inbentus): leverage turbine technology, compact form‑factors, and ruggedization to win narrowly defined mission profiles (e.g., battlefield, aeromedical, urban EMS).
Notably, several vendors continue to invest in multi‑mode capability (invasive and non‑invasive), battery endurance, and connectivity — capabilities that materially influence buying decisions in 2026 as systems aim for continuity of care from field to ICU.
Recent developments that recalibrate 2026 strategy
-
New product entries with aviation and ambulance certifications reinforce segmentation of demand by operational use case: innovations that shorten certification timelines or deliver dual‑certified devices can unlock premium contracts in aeromedical and defense sectors.
-
Regulatory approvals and 510(k) clearances for new models continue to set launch gates; product teams should factor in regulatory lead times and evidence generation into 2026 launch calendars.
-
Rising equipment costs and capital scrutiny are prompting procurement bodies to shift toward outcome‑based purchasing and service‑inclusive contracts — commercial teams must adapt pricing and warranty propositions accordingly.
What PW Consulting’s full report delivers (practical, executable content)
-
A calibrated market model with historical data (2020–2025) and granular forecasts through 2032, enabling scenario analysis across demand, price, and regulatory outcomes.
-
Segmentation logic and demand drivers by product, interface, and end‑use — with actionable implications for product roadmaps and sales prioritization. (Detailed segment numbers and region splits are reserved for the full report.)
-
Competitive dossiers on the leading suppliers with capability matrices, go‑to‑market strengths, and service coverage maps — including acquisition‑ready targets and integration playbooks for corporate development teams.
-
Regulatory and reimbursement navigator: maps of global approval pathways, compliance checklists for EMS standards, and payer levers that affect hospital and EMS purchasing.
-
Commercial and procurement playbooks: recommended contracting structures (e.g., capex replacement programs, managed service agreements), pricing levers, and case examples of successful procurement pilots.
-
Supply‑chain stress tests and sourcing strategies to mitigate raw‑material cost inflation and component shortages, with a focus on verticals that matter most to transport ventilator production.
Actionable recommendations for 2026 — three priorities
-
Embed regulatory and clinical evidence into product planning. Ensure new model timelines account for certification and clinical validation. Winning proposals to large EMS buyers and aeromedical integrators increasingly require documented compliance with EMS‑specific standards and clinical transition studies.
-
Reframe commercial offers around lifecycle economics. Pricing strategies that emphasize uptime guarantees, integrated consumable supply, and buyback/upgrade options will resonate in an era of constrained hospital capex and rising scrutiny on procurement ROI.
-
Targeted inorganic growth and partnerships. Given the market’s moderate concentration, bolt‑on acquisitions that deliver certifications, distribution reach, or unique operational features (e.g., aviation approvals, turbine technology) can accelerate scale and shorten time to market.
Risks and mitigation for 2026 planning
-
Regulatory bottlenecks: build contingency for longer than expected approval cycles and prioritize early dialogue with regulators and notified bodies.
-
Price and input cost volatility: negotiate multi‑year supply agreements and explore design adjustments that reduce exposure to scarce components without compromising performance.
-
Competitive margin pressure: differentiate on service, certification, and interoperability rather than competing solely on device price.
Conclusion — the strategic delta for 2026
For leaders deciding where to allocate R&D spend, how to structure sales coverage, or whether to pursue M&A in 2026, the essential insight is this: the emergency transport ventilator market is maturing into a strategic subsector of acute care equipment — one defined as much by certification, service economics and operational robustness as by unit price. Successful players in 2026 will combine timely regulatory execution, resilient manufacturing, and commercial propositions that reduce buyer risk across the device lifecycle.
PW Consulting’s full Emergency Transport Ventilators Market report provides the quantitative models, competitor playbooks, and procurement templates required to convert this strategic view into executable plans. For access to the detailed segmentation, regional analyses, and vendor scorecards that we intentionally withhold here, visit our report page or contact our industry practice to schedule a briefing tailored to your 2026 objectives.
For detailed analysis of this topic, please visit the official page: Emergency Transport Ventilators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vital Signs Monitor Market to Hit USD 9,735M by 2032 at 7.35% CAGR
By pmarketresearch, 2026-07-13
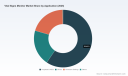
Vital Signs Monitor Market — Strategic Imperatives for 2026
Executive snapshot
The Vital Signs Monitor market is returning to the strategic agenda for healthcare OEMs, hospital systems, and private equity investors entering 2026. After steady expansion through the first half of the decade, the market sits on a trajectory that accelerates across the 2026–2032 forecast window at a compound annual growth rate of 7.35%. In absolute terms this research traces the market from roughly USD 4.3 billion in 2020 to about USD 5.9 billion in 2025, with a professional forecast that projects the opportunity approaching the USD 10 billion mark by 2032. Those headline numbers matter — but the real strategic value of this study is in translating macro growth into concrete choices for product roadmaps, commercial models, and M&A prioritization in 2026.
Vital Signs Monitor Market
Why this report matters for 2026 decision-making
-
Timing of regulatory and reimbursement inflection points: New CPT codes and regulatory communications that take effect during or immediately prior to 2026 materially change the commercial calculus for remote and short-duration monitoring products. Market participants that adapt their go-to-market and coding strategies early will capture disproportionate share of newly reimbursed workflows.
Vital Signs Monitor Market -
Consolidation and concentration dynamics: The market exhibits a mid-to-high concentration profile among incumbents, which creates a strategic paradox — large suppliers retain channel control and scale benefits, while mid-sized and niche innovators can outmaneuver on differentiated, connectivity-first propositions. The report decodes how concentration shapes pricing elasticity, procurement tender behavior, and partnership opportunities.
Vital Signs Monitor Market -
Technology and workflow convergence: Advancements in wearable sensors, edge analytics, and EMR-integrated workflows are shifting procurement criteria from standalone device specs to ecosystem fit. Firms that think in terms of integrated monitoring pathways (device + software + clinical decision support) win procurement discussions and create stickier revenue streams.
-
Risk management and supply-chain sensitivity: High-profile safety events and recalls in the prior 24 months are reshaping clinical procurement policies and third-party battery/device sourcing rules. Risk-averse buyers will prioritize suppliers with transparent quality systems and documented post-market surveillance programs.
What this report delivers (practical, transaction-ready content)
PW Consulting’s Vital Signs Monitor Market study is built to be executable. It goes beyond descriptive narrative to provide the tools and outputs executives need in 2026:
-
Robust base-year market sizing and a detailed forecast model covering 2026–2032, including scenario runs tailored to alternative regulatory and reimbursement assumptions.
-
Commercial playbooks for five buyer archetypes (large health systems, ambulatory surgery centers, clinics, home-health operators, and private label/contract manufacturers) that outline procurement triggers, TCO levers, and negotiation playbooks.
-
Product roadmap guidance linking clinical use-cases to prioritized feature investments (connectivity modalities, battery/portability trade-offs, and algorithmic decision support) informed by supplier capability mapping.
-
M&A and partnership heatmaps highlighting high-value targets by capability, with an assessment of integration complexity and a short-list of candidates for bolt-on acquisitions versus strategic alliances.
-
Regulatory and reimbursement tracker with actionable checklists to operationalize new CPT codes and mitigate liability exposure relating to device safety advisories and recalls.
-
Commercial benchmark dashboards that let leadership calibrate pricing, distributor margins, and service model economics against market norms.
To preserve competitive sensitivity, the public executive summary omits the granular regional and application splits — these are available in the licensed dataset and interactive model.
Competitive landscape — how incumbent strategies are evolving
The competitive field is organized around a few strategic vectors: integrated hospital systems and enterprise EMR connectivity, portable/wearable continuous monitoring, home- and consumer-facing simplicity, and component/sensor specialization. Our analysis focuses on how leading firms are positioning along these vectors and the likely battlegrounds for 2026:
-
GE HealthCare emphasizes multi-parameter, portable systems with clinical-grade clearances and hospital workflows. Their investments prioritize ease of deployment in critical care and perioperative environments.
-
Koninklijke Philips N.V. continues to embed monitoring into broader patient surveillance platforms, with strengths in hospital-wide deployment and clinical decision support integration.
-
Medtronic is executing a strategy that blends hospital-grade modules with wearable, integrated monitoring — targeting chronic-care pathways and seamless transitions between ambulatory and inpatient settings.
-
Masimo targets continuous, multi-parameter platforms with a focus on ambulatory and transport use-cases, competing on sensor fidelity and low-motion performance.
-
Nihon Kohden and other established hospital-focused vendors defend critical care gold-standard features; their advantage is deep clinical validation and longstanding acceptance in high-acuity workflows.
-
Specialists such as Nonin and OMRON occupy the precision sensor and mass-market/homecare end of the spectrum, respectively; their models trade breadth for sensor accuracy, cost efficiency, and channel reach into consumer and home-health segments.
-
Baxter (via Welch Allyn) and SunTech represent combinations of strong field sales coverage and integrated workflow solutions, particularly where EMR and early warning score automation matter.
Market concentration metrics indicate a meaningful advantage for the largest suppliers in negotiating with enterprise buyers, but they also underscore opportunities for focused start-ups and medtechs that deliver differentiated clinical evidence or address gaps in the incumbent technology stack.
Regulatory and reimbursement shocks to plan for in 2026
-
Reimbursement: CMS finalized new CPT codes (effective January 1, 2026) that expand reimbursement eligibility for specific short-duration remote patient monitoring use-cases. This change materially improves the ROI case for devices and software stacks that can demonstrate compliance with the coding criteria.
-
Safety and market access: A 2025 safety communication from the FDA about unauthorized OTC infant monitoring devices raised buyer scrutiny and created new documentation requirements for consumer-adjacent products. Coupled with recent device-specific recalls, buyers now place elevated emphasis on supply-chain governance, post-market surveillance, and use-of-third-party accessory policies.
-
Operational impact: Procurement teams are revising RFPs to include supplier attestations around battery sourcing, software maintenance guarantees, and upgrade pathways. These RFP dynamics favor vendors with certified quality systems and a clear aftermarket service roadmap.
Implications for five archetypal 2026 strategies
-
For OEMs focused on enterprise hospitals: Prioritize EMR integration, validated clinical decision support, and multi-parameter platforms that demonstrate ICU-grade performance. Negotiate bundled service agreements that lock in upgrade and maintenance revenue.
-
For firms targeting ambulatory and ASC workflows: Emphasize portability, rapid onboarding, and seamless data transfer into outpatient EHRs. Leverage the new CPT codes by creating simple submission workflows and reimbursement support services.
-
For home-health and consumer-facing brands: Differentiate through simplified user experience, battery reliability, and clear regulatory positioning; prepare for heightened regulatory scrutiny and the need for consumer safety evidence.
-
For private equity and M&A teams: Focus diligence on companies with defensible clinical evidence and recurring service revenues; be wary of targets exposed to third-party accessory-related liabilities unless remedied in warranties and contract terms.
-
For distributors and value-added resellers: Develop bundled service propositions that combine device supply, connectivity integration, and reimbursement navigation to capture more of the downstream value pool.
How to use this research in 90 days
-
Week 1–4: Run the report’s scenario module against your product roadmap and identify three “must-change” product features or commercial terms required to capture newly reimbursed workflows.
-
Month 2: Use the M&A heatmap and supplier risk assessments to produce a prioritized shortlist for bolt-on acquisitions or strategic partnerships; validate assumptions with targeted reference checks.
-
Month 3: Re-design a pilot program that leverages the CPT code changes and the report’s buyer-playbook to secure a reference customer, then iterate for scale.
Next steps — where to find the granular intelligence
This introduction highlights the strategic contours you must consider as 2026 unfolds: a larger, faster-growing market; reimbursement and regulatory pivots that reward readiness; and a competitive map that favors integrated, evidence-backed propositions. To protect the commercial sensitivity of segmentation tables, supplier-level financials, and our full interactive forecast, we provide the detailed datasets and modelling workbook through PW Consulting’s licensed report package. The licensed deliverable includes downloadable models, configurable scenario tools, and the complete list of granular regional and application splits that informed the analysis summarized here.
Contact PW Consulting for a preview workshop and a tailored briefing. In the next 60 minutes we can align the findings to your strategic priorities and outline a 90-day execution plan to capture the most immediate value from the 2026 market inflection.
For detailed analysis of this topic, please visit the official page: Vital Signs Monitor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Beta Carotene Market to Hit USD 922.8M by 2032 at 5.45% CAGR
By pmarketresearch, 2026-07-13
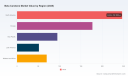
Beta Carotene Market: Strategic Preview for 2026 Decision-Makers
As companies reset strategy for the 2026 planning cycle, understanding the competitive dynamics, regulatory inflection points, and supply-side drivers in the beta carotene market is no longer optional — it is table stakes. This briefing, prepared by PW Consulting’s industry practice, distills the strategic implications of our latest market model and signals the decisions executives must prioritize this year. It intentionally highlights the analytic depth and decision-ready frameworks included in our full Beta Carotene Market study while withholding granular sub‑segment data to direct readers to the source for complete, transaction‑grade intelligence.
Beta Carotene Market
Market trajectory and what it means for 2026
Our comprehensive market model (base year 2025) puts the global beta carotene market at approximately 640 Million USD in 2025. The model shows a steady recovery and expansion over the forecast horizon through 2032, which reaches roughly 923 Million USD under the central case — an implied compound annual growth rate of about 5.45% for the forecast period. Importantly, the market expanded materially from the early 2020s into 2025, reflecting a mix of demand recovery, renewed fortification and supplementation programs, and offsetting price dynamics driven by raw material availability.
Beta Carotene Market
For 2026 corporate planning, three high‑level takeaways emerge from this trajectory:
Beta Carotene Market
- Volume growth is healthy but not hyper‑accelerating. Strategy should favor margin expansion and portfolio differentiation over pure volume scale at all costs.
- Price and cost dynamics will be decisive. Procurement, process innovation, and product formulation choices can materially shift margin profiles.
- Regulatory stability in key jurisdictions is unlocking near‑term commercial opportunities — and will shape where to deploy commercial resources in 2026 and beyond.
Regulatory and raw material dynamics — managing tail risks
A major non‑market risk variable for 2026 is regulatory clarity. In July 2025, the European Food Safety Authority issued a scientific opinion renewing authorisation for beta‑carotene as a feed additive across animal species, explicitly confirming safety and efficacy without requiring new data. That decision materially reduces regulatory downside in Europe for feed applications — a fact that should factor into portfolio and go‑to‑market sequencing.
On the supply side, natural versus synthetic economics remain pivotal. Industry sources note that natural beta‑carotene continues to command a premium over synthetic alternatives due to more complex extraction and processing. Technological improvements in cultivation, extraction and downstream processing are narrowing that gap, but the cost delta persists and will influence procurement, pricing, and product positioning decisions in 2026. Notably, disparate reporting conventions produce divergent market estimates for “natural” beta‑carotene under broader definitional bases; some industry datasets estimate the broader natural market at different scales. Our full study reconciles these differences through a reproducible methodology — a critical aid for buyers or M&A teams assessing target valuations.
Competitive landscape: concentration, capabilities and strategic postures
The market structure is moderately concentrated. The top three suppliers account for a majority stake, and the top five widen that concentration further. This structure creates both bottlenecks and opportunities: suppliers with scale can command sourcing advantages and long‑term agreements with feed and nutrition customers, yet mid‑tier and specialized players can win by owning unique IP, sustainable sourcing claims, or differentiated formulations.
Key players we profile in depth include established ingredient multinationals and focused carotenoid specialists. Each presents different strategic lessons for 2026:
- BASF SE: A global chemical leader selling synthetic and nature‑identical beta‑carotene under established brands and across various product forms. For incumbents, BASF’s model highlights the strategic value of portfolio breadth (powders, dispersions, feed grades) and channel coverage — especially the ability to serve both food/beverage and animal nutrition customers from shared manufacturing platforms.
- dsm‑firmenich (DSM Nutritional Products): A leader in natural‑source beta‑carotene with branded product lines positioned at the premium end of nutrition and fortification. DSM’s approach underscores how brand, certified natural claims, and co‑development with formulators can sustain pricing power even as extraction technologies evolve.
- Kemin Industries: A privately held specialist emphasizing sustainable sourcing and safety in human nutrition carotenoids. Kemin is instructive for companies considering a sustainability‑first differentiation strategy and for investors seeking niche, defensible assets in natural ingredient supply chains.
- Lycored Ltd.: A focused natural carotenoid developer with roots in tomato‑based extraction technologies. Lycored’s positioning demonstrates the advantages of science‑led marketing and partnerships targeted at food and supplement OEMs seeking clean‑label solutions.
Across these profiles, several strategic patterns emerge: brand and trust matter in premium channels; scale and product form capabilities matter in high‑volume industrial channels; and traceability/sustainability claims are increasingly non‑negotiable for customer conversations in 2026.
Where companies should focus in 2026 — strategic playbook
Based on our analysis, PW Consulting recommends that executives align 2026 initiatives against five priorities that convert market growth into durable value:
- Secure supply with flexible sourcing strategies. Lock in tiered agreements that balance spot purchases with medium‑term contracts; consider forward purchasing, tolling partnerships, and minority investments in upstream producers to mitigate raw material volatility.
- Invest in cost‑to‑serve reduction and processing efficiency. Even modest gains in extraction yield or formulation efficiency have outsized margin implications given the persistent premium for natural inputs.
- Differentiate through verified sustainability and traceability. Expect commercial RFIs in 2026 to demand chain‑of‑custody data and measurable sustainability KPIs; early adopters of verified claims will capture premium channels.
- Use regulatory clarity as a lever for market entry and expansion. The EFSA renewal reduces European feed regulatory risk; companies should recalibrate market access plans to prioritize segments where regulatory friction has diminished.
- Adopt a selective M&A and partnership stance. Given moderate market concentration, bolt‑on acquisitions or strategic partnerships can accelerate access to local production, niche IP or specialty formulations — but targets should be vetted against a rigorous post‑deal integration and margin improvement plan.
What the full PW Consulting study delivers (practical contents)
Our full Beta Carotene Market report is designed to be executionable for 2026 leaders. It includes:
- Detailed, auditable market sizing (historical 2020–2025; base year 2025) and a transparent forecasting model through 2032, including alternate scenarios and sensitivity to raw material price, regulatory changes, and end‑market demand shocks.
- A regulatory matrix covering major jurisdictions, recent opinions (including EFSA July 2025), and a quantified regulatory risk scoring to prioritize market entry sequencing.
- Supply chain heatmaps and a supplier‑risk dashboard that identify single‑source exposures, logistics chokepoints, and sourcing arbitrage opportunities.
- Commercial playbooks for positioning natural vs synthetic products across nutrition, food, feed, pharmaceuticals and cosmetics channels — with pricing levers, bundling opportunities, and go‑to‑market templates.
- Due diligence templates and an M&A target short‑list methodology, aligned to CR3/CR5 concentration dynamics and valuation sensitivities observed in recent transactions.
- Customizable scenario tools for procurement and finance teams to stress‑test margins under varying raw material, regulatory and demand conditions.
How to use this preview in your 2026 planning cycle
This briefing is intended as a strategic lens for two uses in 2026 planning cycles. First, it should inform portfolio prioritization: decide where to invest scarce R&D and commercial resources between premium natural propositions and cost‑optimized synthetic offers. Second, it should feed procurement and M&A decision funnels: reassess supplier concentration, consider upstream partnerships, and run valuation scenarios for potential acquisitions using the methods summarized above.
We deliberately omitted core sub‑segment figures in this preview to protect the transactional value of the underlying dataset. The full study contains transaction‑grade segmental splits, regional demand matrices, detailed supplier profiles and a downloadable forecasting model that procurement, strategy, and M&A teams can put to immediate use.
Concluding strategic observations
Beta carotene presents a classic mid‑cycle industrial play: steady top‑line growth, concentrated supply, evolving cost economics between natural and synthetic sources, and regulatory inflection points that can reallocate commercial focus quickly. Executives who treat 2026 as a year of capability‑building — securing flexible supply, investing in processing efficiency, and shoring up sustainability credentials — will convert the market’s structural growth into persistent margin advantage.
For a practical, decision‑ready guide that includes the exact segment outcomes, regional demand curves, supplier scorecards, and a calibrated M&A target list optimized for 2026 execution, access the full PW Consulting Beta Carotene Market report.
For detailed analysis of this topic, please visit the official page: Beta Carotene Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com