

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
Quantum Computing Market — Strategic Imperatives for 2026 Decision‑Making
Executive snapshot
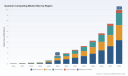
Quantum computing is transitioning from laboratory breakthrough to enterprise agenda item. Our latest PW Consulting market study, anchored on a 2025 base year and covering historical performance (2020–2025) with forecasts to 2032, places the industry on a sustained high‑growth trajectory. The market expanded rapidly over the first half of the decade—moving from single‑digit millions to a multi‑hundred‑million to low‑billion USD environment—and reached approximately USD 1.5 Billion in 2025. Under a central scenario, we model a robust compound annual growth rate of 29% through 2032, bringing the global market close to USD 10 Billion by the end of the forecast period.
Quantum Computing Market
That pace of expansion is not uniform: technology pathways (superconducting, trapped‑ion, photonic, annealing and others), infrastructure maturity (cloud access, colocated devices, dedicated on‑prem systems), and regulatory regimes all create pockets of rapid adoption alongside areas where integration remains nascent. This asymmetry is precisely why 2026 is a critical pivot year for corporate and public sector decision‑makers.
Quantum Computing Market
Why this report matters for 2026 strategy
Many organizations will face a classic build‑versus‑buy decision in 2026. Early adopters that delay architecture choices risk higher conversion costs and longer runways to production; those that commit too aggressively risk vendor lock‑in or stranded investments if competing modalities leapfrog expectations. Our study is designed to inform those tradeoffs with scenario‑driven, actionable guidance.
Quantum Computing Market
- Timing: Identify the commercial inflection points that matter for procurement windows, pilot budgeting, and multi‑year roadmaps.
- Risk management: Quantify operational and supply‑chain risks (device reproducibility, cryogenics, interconnects, component sourcing) and map mitigation levers you can implement today.
- Vendor strategy: Build a defensible partner portfolio—when to partner with hyperscalers, when to co‑invest with specialist vendors, and when to favor multi‑vendor/cloud neutrality to preserve optionality.
- Regulatory & geopolitical readiness: Translate export controls, domestic incentives, and regional industrial strategies into practical compliance and sourcing playbooks.
What’s inside the report — practical, transaction‑grade tools
The PW Consulting study is deliberately operational. Beyond high‑level forecasts and trend analysis, the report includes: scenario models (fast technical progress vs. conservative adoption), vendor due‑diligence templates, total cost of ownership models for cloud vs. on‑prem deployments, capex phasing roadmaps keyed to technical milestones, and an M&A playbook for acquiring quantum‑era IP and talent. We also provide implementation blueprints for use cases where quantum advantage is plausible in the near to mid term—covering optimization, simulation of complex materials/chemistry, and early hybrid classical‑quantum machine learning experiments.
- Interactive financial models you can parameterize with your own cost and revenue assumptions.
- Vendor scorecards and integration checklists for procurement teams.
- Regulatory compliance checklists aligned to recent export control and regional industrial policy changes.
- Workforce and skills transition plans to bridge classical HPC, AI, and quantum engineering teams.
Competitive landscape — capabilities, positioning, and tactical takeaways
The market is consolidating around a set of capability clusters rather than a single winner‑takes‑all outcome. Leading technology suppliers fall into distinct strategic typologies: hyperscale integrators offering cloud access and cross‑platform marketplaces; specialist device companies advancing particular qubit modalities; and vertically integrated vendors selling systems to research and national infrastructure customers.
- Hyperscale platforms: Established cloud providers are moving beyond access to build proprietary device capability and hybrid orchestration. Expect differentiated value from combined cloud, tooling, and data services that lower customer integration costs.
- Device specialists: Companies focused on one modality (superconducting, trapped‑ion, photonic, neutral‑atom, annealing, silicon spin, etc.) are executing on performance roadmaps—many are now offering cloud access and targeted commercial systems for application pilots.
- Systems integrators and regional champions: A cohort of firms is commercializing full‑stack solutions and selling into supercomputing centers, national labs, and industrial incumbents requiring on‑prem or dedicated installations.
Key examples from our competitive matrix (profiles included in full report): IBM’s superconducting roadmap and System One architecture; Google Quantum AI’s emphasis on error correction and logical qubits; Microsoft’s multi‑modal Azure Quantum strategy; Amazon Braket’s marketplace approach coupled with its proprietary cat‑qubit development; D‑Wave’s annealing platforms optimized for combinatorial optimization; IonQ and Quantinuum’s trapped‑ion advancements; photonics entrants targeting fault‑tolerant roadmaps; and regional players pursuing national infrastructure deployments. The leading vendors collectively produce a market that is moderately concentrated—top players hold substantial, but not overwhelming, shares—creating room for strategic partnerships and niche leadership.
Recent market catalysts and structural drivers
Several developments converging in 2024–2026 materially reshape strategic choices for 2026:
- Policy and incentives: Significant public programs and incentive agreements are accelerating domestic manufacturing and systems engineering priorities, with funds targeted at reproducibility, cryogenics, and interconnects—areas that materially affect supply‑chain risk and timing.
- Standardization and benchmarking: Regional standards initiatives and benchmarking coordination are beginning to create interoperable performance baselines—this will reduce buyer due diligence burden but also raise the bar for vendors that cannot demonstrate measurable benchmarks.
- Technological bottlenecks: Cryogenics, in‑vacuum control electronics, and error‑correction overhead remain primary engineering constraints. Advances in these areas materially shorten the time to commercially useful quantum workloads.
- Private capital and distributed systems: New funding rounds and commercial system launches—especially in distributed quantum networking and logical qubit demonstrations—signal that we are moving into a capital‑intensive commercialization phase where deployments will be differentiated by systems engineering and integration rather than raw qubit counts alone.
Strategic implications by decision area
- Procurement & architecture: Favor modular architectures that allow swap‑out of device providers and prioritize hybrid orchestration. Shortlist vendors based on integration overhead, not just headline qubit metrics.
- R&D and IP strategy: Participate in consortia and standards bodies to influence benchmarks and secure early access to interoperability frameworks; consider minority equity stakes or co‑development to secure priority roadmaps.
- Regulatory & supply chain: Reassess sourcing strategies in light of export control regimes and national industrial strategies—plan for segmented supply chains and localized redundancy for mission‑critical projects.
- Workforce & partnerships: Invest in cross‑training classical HPC and quantum engineers; prioritize partnerships with cloud providers for rapid pilot execution while building in‑house capability for differentiated production workloads.
What PW Consulting recommends today (high level)
- Adopt a two‑track strategy: run near‑term pilots to validate primitive advantage in tightly scoped use cases, while establishing architectural guardrails and supplier optionality to capture medium‑term production opportunities.
- Prioritize investments in integration: spend on systems engineering, cryogenic interfaces, and software toolchains now to reduce future migration costs.
- Engage in standards and policy dialogues: active participation shortens compliance timelines and can influence the shape of benchmarking that will determine procurement decisions.
- Use incentives strategically: align proposals to public funding that targets shared bottlenecks—this can materially accelerate timelines and lower capex.
Next steps — where to find the detailed intelligence
This article is a strategic preview. The full PW Consulting Quantum Computing Market report contains the granular segmentation, vendor scorecards, downloadable financial models, scenario dashboards, and step‑by‑step implementation guides that procurement, R&D and C‑suite teams will use to make defensible 2026 decisions. We have intentionally withheld detailed regional and application share tables in this preview to preserve the value of the complete dataset and analytic tools included in the full deliverable.
For organizations preparing to make procurement, partnership, or investment decisions in 2026, the complete report provides the transaction‑grade analysis required to move from pilot to production with confidence: side‑by‑side technology comparisons, detailed integration timelines, regulatory checklists, and bespoke advisory options from PW Consulting to tailor roadmaps to your strategic objectives.
Contact PW Consulting to access the full report, interactive models, and advisory engagement options to convert the quantum market’s projected growth into measurable business outcomes for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Quantum Computing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Paint Filters Market to Hit USD 301.5M by 2032, Growing at 6.5% CAGR — PW Consulting
By pmarketresearch, 2026-07-13
Paint Filters Market: Strategic Imperatives for Corporate Decision‑Making in 2026
Executive summary
As companies plan capital allocation and operational shifts for 2026, the paint filters market offers a concrete, measurable signal of adjacent industrial health and regulatory demand. Our PW Consulting analysis shows the market has expanded steadily from the early 2020s and reached a clear inflection point by the report base year (2025). With a compound annual growth rate (CAGR) of 6.5% embedded in our forecast, the total market is projected to progress through the 2026–2032 horizon to materially larger volumes by 2032. These macro dynamics—rooted in regulatory reinforcement, materials cost structure, and product innovation—create both tactical choices and strategic inflection points for manufacturers, processors, and their procurement and compliance teams.
Paint Filters Market
Why 2026 matters: regulatory tightening meets operational optimization
Two converging forces make 2026 a watershed planning year for executives with stakes in paint filtration and adjacent value chains. First, the regulatory baseline was reaffirmed in mid‑2025 when the U.S. Environmental Protection Agency updated its official guidance for the Paint Filter Liquids Test (SW‑846 Method 9095B). The update reinforced that test outcomes continue to determine hazardous waste classification and landfill eligibility under the relevant CFR sections—an outcome that can directly alter disposal cost structures and downstream handling requirements for generators.
Paint Filters Market
Second, suppliers and end users are responding to long‑term cost pressures (materials and labor) through product design and automation. The sector remains dominated by low‑unit‑cost consumables—paper or nylon mesh cut to fit—and by capital products that shift replacement labor out of the critical path. Self‑cleaning filter systems and higher‑efficiency cartridge designs reduce throughput interruptions and limit the labor intensity of routine maintenance. For firms that manage large paint volumes or hazardous waste streams, these changes convert compliance obligations into a lever for operational savings.
Paint Filters Market
What PW Consulting’s Paint Filters Market study delivers
- Robust, auditable market sizing for 2020–2025 (historical) and a transparent forecast model for 2026–2032 built on a 6.5% CAGR baseline.
- Driver maps that separate regulation‑driven demand from industrial cycle effects (e.g., semiconductor and IC packaging manufacturing dynamics), enabling scenario stress‑testing for demand shocks.
- Supply‑side decomposition—including raw material inputs, typical BOMs for consumable and capital filter families, labor drivers for replacement and servicing, and the cost levers suppliers can exploit.
- Competitive intelligence dossiers on incumbent and challenger suppliers, including product portfolios, go‑to‑market approaches, and likely consolidation vectors.
- Actionable playbooks by function: procurement sourcing levers, operations redesign to reduce filter change downtime, R&D roadmaps for filter media and cleaning innovations, and compliance frameworks that convert regulatory requirements into minimal‑cost protocols.
- Investment and M&A appraisal tools: valuation sensitivities for targets, synergy checklists, and an integration scorecard tailored to filtration equipment and consumable businesses.
We designed the report to be operational: models, templates, and executable recommendations are included alongside narrative insight so teams can move from insight to implementation without re‑inventing core analyses.
Competitive landscape — who matters and why
Market structure is moderately fragmented; the three‑ and five‑firm concentration ratios indicate a market where regional specialists and technology niches coexist with a smaller set of global suppliers. This structure creates persistent opportunities for differentiation through product innovation, cost position, and channel control.
- M² Polymer Technologies (United Kingdom) — Supplier of superabsorbent polymers and the specialized equipment used in the Paint Filter Test (EPA SW‑846 9095B). Their strength is lab‑grade test apparatus and consumables that are critical for facilities performing hazardous waste determinations.
- K2TEC (France) — Maker of self‑cleaning filters and filtration systems tailored to viscous paints and industrial applications. K2TEC exemplifies the operational efficiency angle: systems that reduce manual handling and improve uptime.
- Filterworkshop (China) — Producer of electrophoresis paint filter bags and liquid filter media. Their cost position and scale in consumables make them a common supplier in high‑volume industrial settings.
- Brother Filtration (United States) — Focused on melt‑blown cartridge filters and filtration solutions for paint manufacturing processes, serving customers seeking higher filtration efficiencies and cartridge‑based replacement strategies.
Collectively, market participants range from regulatory‑test specialists to high‑throughput consumables manufacturers. Competitive differentiation today is less about raw materials (many inputs are commodity‑like) and more about system integration, service models, and the ability to demonstrate lifecycle cost reductions to customers under tightening regulatory scrutiny.
Key market dynamics and operational implications
- Regulatory enforcement as demand driver: The continued emphasis on the Paint Filter Liquids Test and related CFR requirements means that many customers treat test‑capable consumables and associated documentation as risk mitigation purchases rather than discretionary buys. This changes procurement behavior toward certified suppliers and documented test chains.
- Low unit cost, high aggregate impact: Although many filter products are individually inexpensive, their recurring nature and the administrative burden around hazardous waste testing create substantial total cost of ownership opportunities for suppliers that can offer service contracts, training, or automated sampling solutions.
- Labor and automation: Self‑cleaning and cartridge systems substantially lower per‑incident labor costs, shifting buyer preference toward higher upfront capital investment when total lifecycle economics are compelling.
- Material and supply chain resilience: Standardization (for example, conical filters with specific mesh tolerances) reduces technical variance but increases exposure to supply disruptions for primary raw inputs—an important consideration for procurement and risk teams.
Strategic recommendations by corporate function
- Procurement: Move from unit‑price negotiation to outcome‑based contracting. Prioritize suppliers that can certify test compliance and provide lifecycle cost transparency. Consider multi‑year agreements that align incentives on downtime reduction and waste minimization.
- Operations: Pilot self‑cleaning or cartridge systems in the highest downtime processes first. Quantify labor savings with a simple before‑and‑after time‑motion study and use those findings to build the capital approval case.
- R&D and product management: Invest selectively in filter media that lower change frequency or enable reuse without violating regulatory test protocols. For manufacturers, embedding test certification into product specs will win trust among hazardous waste managers.
- Compliance and EHS: Treat test methodology requirements as business rules. Incorporate test outcomes into disposal cost models and scenario planning so that compliance becomes a deterministic input to budgeting rather than an afterthought.
- M&A and corporate development: Target acquisitions that fill gaps in certified testing, after‑sales services, or automation capabilities rather than pure volume plays. Smaller technology specialists can unlock disproportionate operational value when integrated into a broader consumables + service platform.
Forecast view and scenario framing through 2032
Our baseline forecast—anchored to historical performance through 2025—assumes continuity in demand drivers and the 6.5% CAGR noted earlier. Under this baseline, the market exhibits steady expansion over the forecast period, reflecting combination of regulatory persistence, increasing industrial throughput in adjacent end markets, and incremental upgrades toward automated filtration systems.
PW Consulting’s scenarios explore three divergent trajectories: a conservative regulatory drift scenario, a baseline growth scenario tied to current macro assumptions, and an accelerated adoption scenario driven by rapid automation and tightening global waste policies. Each scenario alters the timing and scale of capital replacement cycles, inventory stocking strategies, and service opportunities. Executives should use these scenario outputs to stress‑test capital budgets and procurement commitments planned for 2026 and beyond.
Why this research matters for decisions you’ll make in 2026
Decision cycles for procurement contracts, CAPEX approvals, and M&A activity commonly use two‑to‑five‑year horizons. The interplay of renewed regulatory clarity (post‑2025) and improving product economics makes 2026 the first full planning year where companies can convert mid‑term guidance into executable contracts and pilots. This report equips leaders with the cost levers, supplier maps, and scenario tools needed to:
- Decide whether to trade a lower unit price for higher service guarantees;
- Justify automation investments through empirically derived labor and downtime reductions;
- Identify acquisition targets that accelerate certification capabilities or service footprints; and
- Quantify risk exposure from raw material or supplier concentration and design mitigations.
How to use the full PW Consulting report
The article above is intentionally selective: it provides the strategic logic and directionally accurate macro statistics to inform initial planning conversations, while preserving the granular segmentation, supplier financials, and downloadable models for subscribers. If you are preparing procurement RFPs, CAPEX proposals, or an integration plan for potential targets, the full report includes the data tables, supplier scorecards, and modeling templates necessary to move from strategy to execution.
Contact PW Consulting to obtain the complete study and the Excel modeling pack that underpins the forecasts and scenario outputs. Our advisory team can also run a tailored workshop to map these insights directly onto your 2026 planning cycle and produce a prioritized action plan for procurement, operations, and compliance teams.
For detailed analysis of this topic, please visit the official page: Paint Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Artificial Meat Market Set for 14.6% CAGR Through 2032
By pmarketresearch, 2026-07-13
Artificial Meat Products Market — Strategic Imperatives for 2026
Executive preview
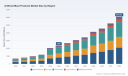
As the artificial meat sector transitions from laboratory novelty to commercial scale, corporate leaders face a compressed decision window in 2026. PW Consulting’s latest market study synthesizes seven years of historical dynamics (2020–2025), establishes 2025 as the base year, and extends a forward-looking forecast through 2032. The headline numbers underline an industry undergoing rapid expansion: the global market grew from roughly USD 700 Million in 2020 to USD 2,360 Million in 2025 and is forecast to reach about USD 6,076.7 Million by 2032, implying a compound annual growth rate (CAGR) of 14.6% over the forecast period (figures expressed in USD Million). These macro trends create discrete strategic inflection points for incumbent protein companies, ingredient suppliers, equipment OEMs, retailers, and financial sponsors.
Artificial Meat Products Market
Why this research matters for 2026 decision-making
-
Timing and scale: 2026 is where regulatory clarity, scalable manufacturing, and early commercial pathways converge. The market is no longer theoretical; the 2025 base year shows material commercial traction and the near-term 2026 estimate demonstrates continued growth. Executives must decide now whether to accelerate capex, enter via partnerships, or adopt a wait-and-see posture.
Artificial Meat Products Market -
Capital allocation and valuation discipline: With a clear medium-term growth trajectory to 2032, investors need justified unit-economics scenarios. Our study provides scenario-driven valuation frameworks built on the reported CAGR and top-line market trajectory, enabling robust IRR and payback analyses for greenfield facilities, joint ventures, or bolt-on M&A.
Artificial Meat Products Market -
Regulatory arbitrage and market access strategy: 2025–2026 saw notable regulatory milestones and also emergent jurisdictional restrictions. The report maps regulatory approvals and prohibitions across key markets and models their impact on prioritizing market entry, product mix, and compliance spend.
-
Channel and route-to-market choices: Early commercial approvals in select markets are creating differentiated retail and foodservice paths. The study dissects pilot-to-retail use cases and outlines the commercial plays that best match differing cost structures and brand propositions.
Market snapshot (select macro datapoints)
Key anchors you can act on today: observed market size rose from approximately USD 700 Million in 2020 to USD 2,360 Million in 2025 (base year). The 2026 outlook begins the next acceleration phase (projected at ~USD 2,686.4 Million), and by 2032 the market is expected to exceed USD 6,000 Million. These figures reflect an industry-level CAGR of 14.6% across the forecast window of 2026–2032. Market concentration metrics show a still-fragmented industry: the top three firms account for roughly 25% of identifiable market share and the top five for about 30%, signalling both consolidation potential and sustained room for challengers.
What the PW Consulting report delivers — practical, transaction-ready outputs
-
Granular market architecture: an actionable segmentation framework (by source, application, and region) that supports portfolio prioritization without presupposing a single path to market.
-
Transparent forecasting models: base-case, upside, and downside scenarios tied to sensitivity levers (capex per kg, bioreactor scale-up curves, feedstock costs, and regulatory time-to-market). Models are provided in editable financial templates (USD Million).
-
Unit-economics and breakpoint analysis: step-by-step build-ups from R&D and cell-line yields through to finished-product COGS and suggested price points for different channels (retail versus foodservice).
-
Manufacturing and scale playbook: techno-economic assessment of bioreactor architectures, single-use vs. stainless strategies, downstream processing challenges, and capital planning for 1–10 kTpa facilities.
-
Regulatory and policy tracker: a live register of approvals, pre-market reviews, labeling rules, and state-level restrictions—paired with a risk-heatmap and mitigation strategies for market entry sequencing.
-
Commercialization templates: go-to-market roadmaps, channel partnership models, pricing and promotion playbooks, and early adopter consumer segmentation.
-
M&A and partnership targets: screening criteria, shortlist of compatible technology licensors and manufacturing partners, and pro forma acquisition models for value accreting deals.
Competitive landscape — who matters and why
The sector’s competitive set includes purpose-built cultivated-protein pioneers, hybrid innovators, and ingredient specialists. Some headline players driving market norms and regulatory precedent include:
-
Aleph Farms (Israel) — notable for whole-cut cultivated beef steaks using 3D-bioprinting approaches. Their technology and IP around structure generation position them as a reference for premium cuts and higher-margin product strategies.
-
UPSIDE Foods (US) — focused on cultivated chicken with regulatory wins that enable USDA-reviewed retail and restaurant channels in the United States. UPSIDE exemplifies the path from cell-line optimization to regulatory-compliant commercial rollouts.
-
GOOD Meat (US) — early mover with approvals facilitating market entries in Singapore and the US. Their cross-border commercialization experience is instructive for companies planning staggered rollouts across differentiated regulatory regimes.
-
Wildtype (US) — concentrates on cultivated seafood and has secured approvals for raw consumption applications in the US, demonstrating that seafood presents distinct regulatory and sensory routes compared with terrestrial proteins.
-
Believer Meats (US) — emerging as a scale-focused manufacturer with recent FDA approvals instrumental to US market entry and larger production footprints.
-
Mosa Meat (Netherlands) — a pioneer in cultivated beef burgers and a bellwether for cost-down strategies in mainstream burger formats.
-
Mission Barns (US) — notable for cultivated fat and hybrid pork applications; regulatory approvals for fat components open differentiated product economics.
-
Vow (Australia), Meatly (UK), Finless Foods (US) — represent regional commercialization strategies and niche applications (quail, pet food, seafood) that diversify the competitive map.
Recent regulatory and market developments to factor into 2026 plans
-
Multiple cultivated products successfully completed FDA pre-market review under the joint FDA–USDA framework by 2025—this is a pivotal enabler of scaled retail and foodservice access in the US.
-
Selective regulatory approvals in Singapore, Hong Kong, and Australia are creating viable export and test-market hubs for product iterations and consumer insights.
-
Simultaneously, several U.S. states have introduced restrictive legislation or outright bans on cell-cultured meat sales; layered state-level constraints will require tailored market access strategies and legal contingency planning.
-
Notable 2025 approvals and launches (e.g., FDA clearance for raw-consumption salmon cell material; USDA/FDA approvals of selected cultivated chicken and pork components) serve as practical precedent for dossier preparation and post-market surveillance commitments.
Practical strategic plays for 2026
-
Prioritize platform bets: if your core competence is scale-up engineering or fermentation, align investment toward manufacturing enablement (facility design, process control) rather than front-of-pack branding in year one.
-
Establish regulatory-first go-to-market teams: build or partner with legal/regulatory specialists to manage multi-jurisdiction filings and labeling strategies; this reduces time-to-shelf risk materially.
-
Focus on hybrid products as de-risked commercial entries: blended formulations (cultivated cell material + conventional ingredients) lower immediate COGS hurdles while opening larger retail doors.
-
Lock supply chain levers early: long-lead items (bioreactors, DSP equipment, ingredient sources) require procurement lead times that must be reconciled with projected 2026–2028 capacity needs.
-
Design flexible manufacturing footprints: modular, decoupled facilities enable regulatory partitioning, shorten commissioning timelines, and preserve optionality across products and markets.
How to use this report in boardrooms and investment committees
Use the study as the single-source, scenario-driven reference for capex approval, partnership evaluations, and M&A screening. The report’s editable models allow your financial team to stress-test assumptions against internal cost data, while the regulatory tracker provides the compliance checklist required for market entry. For investment committees, the CR3/CR5 concentration context supports arguments around consolidation opportunities and defensibility of IP or scale advantages.
Conclusion — the signal amid the noise
The artificial meat market is evolving from early commercial proofs into a structurally investable category. The macro trajectory—anchored by a CAGR of 14.6% and a projected expansion from a 2025 base of USD 2,360 Million—creates clear windows for value creation, provided companies align product, regulatory, and scale strategies in 2026. PW Consulting’s report supplies the operational models, regulatory roadmaps, and competitive diagnostics necessary to move from hypothesis to execution.
Next step
To preserve strategic advantage, the report intentionally omits publicly accessible granular subsegment figures in this preview. For full access to the detailed segmentation tables, editable financial models (USD Million), geographies, application-level economics, and a prioritized list of M&A/partner targets, visit our report page or contact PW Consulting to request the complete dataset and a tailored briefing.
For detailed analysis of this topic, please visit the official page: Artificial Meat Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Rosehip Oil Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise yet strategic preview of our latest Rosehip Oil Market study. This briefing synthesizes the forces that will shape investment, sourcing and product strategy through the 2026 planning cycle and beyond. It signals where executive attention and capital allocation will matter most, without disclosing the granular segmentation that gives competitive advantage — those datasets are held for the full report.
Rosehip Oil Market
Why this market matters for 2026
-
Rapid scale-up: The rosehip oil market has demonstrated sustained expansion across the historical 2020–2025 window and is forecast to continue at a robust compound annual growth rate (CAGR) of 10.5% throughout the 2026–2032 projection period. This trajectory converts a niche botanical commodity into a strategic ingredient class for personal care, nutraceutical and select food applications.
Rosehip Oil Market -
Material size and upside: Using 2025 as the base year (reporting in Million USD), the market has moved into a range that sustains meaningful supplier economics and justifies dedicated sourcing programs, manufacturing investment, and targeted product innovation pipelines.
Rosehip Oil Market -
Fragmented supplier base: Market concentration metrics confirm a fragmented structure — the top three firms account for a minority share and the top five likewise do not dominate the industry — creating both procurement leverage and supplier risk for large buyers.
What this means for 2026 enterprise decisions
-
Procurement strategy must evolve from transaction to partnership. Buyers who continue to treat rosehip oil as an interchangeable commodity will face supply shocks and margin squeeze as demand increases. Prioritise supplier diversification, backward-integration options, and multi-year offtake frameworks tied to quality and certification commitments.
-
Product roadmaps should explicitly embed rosehip oil’s value proposition across premium and functional tiers. Given the ingredient’s reputational pull in clean beauty and restorative skincare, formulators who lock in stable, certified supplies will gain both development speed and marketing authenticity.
-
Risk-adjusted sourcing economics are non-negotiable. Volatility in raw rosehip prices is a documented driver of input cost swings; scenario planning — including hedged contracts, fixed-price tranches, and local processing investments — must be part of 2026 budgets.
Market trajectory — calibration for strategy
Between 2020 and 2025 the market expanded notably, establishing a base that supports larger-scale commercial moves. With a forecast CAGR of 10.5% across 2026–2032, management teams should plan for a market that roughly doubles over the medium term. That pace of growth elevates rosehip oil from niche botanical to strategic commodity for firms that require reliable ingredient sourcing, traceability, and compliance documentation at scale.
Demand drivers and supply-side constraints
-
Consumer trends: The twin tailwinds of “clean/organic” personal care and ingredient storytelling are primary demand engines. Consumers — and therefore marketers — prize botanically derived actives with traceable provenance and certified organic credentials.
-
Regulatory context: Practical regulatory realities reduce friction for market expansion: rosehip oil is considered a non-chemically modified vegetable oil and is exempt from REACH registration irrespective of quantity; it is also not listed with specific concentration limits under the EU Cosmetics Regulation. These characteristics simplify cross-border sales relative to some other botanical actives, shortening time-to-market for international launches.
-
Quality and certification gatekeepers: European and other institutional buyers increasingly mandate organic certification, HACCP, GMP and ISO 9001:2015. Suppliers who cannot demonstrate consistent quality systems and certification will be excluded from high-value contracts, regardless of price.
-
Sourcing sustainability and legality: While rosehips themselves are not broadly restricted, wild-harvest practices can trigger CITES-related compliance considerations in some sourcing geographies; traceability and socially responsible procurement practices are therefore both regulatory and reputational imperatives.
-
Input price volatility: Fluctuating rosehip harvests and yield variability create cost risk that compresses margins for processors and traders — a dynamic buyers can mitigate through longer-term agreements, vertical integration, or blended sourcing strategies.
Competitive landscape — how to think about suppliers
Our industry mapping highlights a diverse mix of specialist producers, regional exporters and global distributors. Key firms include established European processors, Chilean and Southern Hemisphere producers with crop advantages, and international distributors that bridge producers to formulators. The landscape can be summarised into three archetypes relevant to 2026 planning:
-
Quality-focused processors: European and New Zealand players have strong technical capabilities in cold-pressing and refining, with organic product lines and global delivery. These suppliers are attractive partners for premium brands seeking certified, traceable inputs and are often preferred for higher-margin SKUs.
-
Origin specialists: South American and Southern African producers offer scale and cost advantages due to favourable growing conditions and established export infrastructures. These firms are central to supply continuity but require careful due diligence on sustainability and certification pathways.
-
Global distributors and wholesalers: Companies headquartered in major purchasing markets provide logistical reach, product breadth, and private label capabilities. They are efficient for firms seeking flexible purchase sizes and faster time-to-market; however, buyers seeking full traceability and quality control may need to layer supplier audits or request mill-level guarantees.
Strategic implications for partner selection: - Align supplier archetype with product strategy: premium brands should prioritise processors with certifications; scale players should secure origin specialists with long-term supply contracts. - Use concentration dynamics to negotiate: the fragmented market offers bargaining power but also demands rigorous supplier performance management. - Integrate sustainability and compliance into contracts: mandatory certifications and traceability clauses will be commercial differentiators and risk mitigants in 2026 negotiations.
Risk matrix and regulatory notes to act on immediately
-
Regulatory clarity is a near-term advantage: exemptions from REACH and the absence of specific restrictions under EU cosmetics rules materially reduce regulatory barriers to expansion. Take advantage of this to accelerate cross-border product launches while maintaining full compliance on labelling and claims.
-
Sourcing and reputational risk: Wild-harvest and labour practices can become headline risks. Implement supplier audits, community engagement requirements and CITES screening wherever applicable to pre-empt supply chain disruption and reputational damage.
-
Price shock preparedness: Build cost scenarios into 2026 P&Ls that account for step changes in raw material costs. Consider blended procurement and local processing investments to dampen price exposure.
What the full PW Consulting report delivers (practical toolkit)
Our full report is structured to convert the strategic insights above into executable initiatives. Highlights include:
-
Proprietary market sizing and 2020–2032 forecasts (base year 2025, values reported in Million USD), with scenario modelling and sensitivity runs that translate growth assumptions into procurement and capacity planning inputs.
-
Supplier scorecards and due-diligence templates tailored to rosehip oil production methods (cold-pressed vs. refined), certification profiles, and country-specific compliance checklists.
-
Commercial negotiation playbook: recommended contract clauses for price escalation, quality holdbacks, traceability requirements, and sustainability commitments plus sample term-sheet language for multi-year offtakes.
-
Go-to-market and product development roadmaps aligned to consumer segments, margin modelling, and channel strategies that bridge ingredient economics to finished-goods commercial feasibility.
-
Risk register and contingency playbooks, including supplier redundancy plans, alternative sourcing matrices, and localized processing options to mitigate raw-material and regulatory shocks.
Recommended actions for executive teams in 2026
-
Initiate supplier diversification pilots Q1–Q2 2026: blend origin, processor and distributor partners with tiered contract terms to balance cost and security.
-
Fast-track certification investments: if your supply relies on EU or premium-brand channels, require ISO/HACCP/GMP and organic credentials as a baseline for qualifying suppliers.
-
Embed scenario planning: incorporate the 10.5% CAGR baseline and upside/downside scenarios into capital expenditure and R&D roadmaps; align inventory policies to anticipated demand volatility.
-
Operationalize sustainability: include social-impact audits and CITES screening in procurement SOPs to protect brand value and secure long-term access to key growing regions.
Closing — why the full study is a 2026 imperative
Rosehip oil is at an inflection point. Its combination of consumer appeal, favorable regulatory treatment and scalable supply options creates an attractive growth corridor, but one with real operational and reputational hazards. For companies planning launches, scaling formulations, or securing long-term supply, the strategic choices you make in 2026 will determine whether you capture premium margin or simply chase commodity economics.
Our full Rosehip Oil Market report provides the confidential segmentation, supplier-level analysis and procurement tools required to convert insight into action. This preview outlines the high-level framework and the immediate decisions to prioritise; the enclosed datasets and playbooks in the paid report supply the tactical specificity that will deliver advantage. Contact PW Consulting to secure access to the full intelligence package and a customised briefing for your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Rosehip Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Autonomous Cars Market to Hit USD 86.28 Billion by 2032
By pmarketresearch, 2026-07-13
Autonomous Cars Market: Strategic Imperatives for 2026
Executive preview — why this research matters to enterprise decision-makers in 2026
As companies reposition capital and capability for the next wave of mobility, the Autonomous Cars Market is moving from exploratory pilots into commercially material scale. Our latest market study — anchored on a 2025 base year and a rigorous 2026–2032 forecast — quantifies a clear and rapid expansion pathway. From an industry size measured in single-digit billions at the start of the decade, the market surpasses the low‑twenty billions mark by 2025 and is projected to approach the high‑eighties of USD Billion by 2032 under our base scenario, reflecting a compound annual growth rate of 22.5% across the forecast period.
Autonomous Cars Market
For executives deciding where to invest, partner, or divest in 2026, this report is not an academic exercise. It is a practical, decision-grade playbook that translates near-term regulatory inflection points, sensor‑software economics, and fleet commercialization timelines into actionable choices for product, corporate development, and public affairs teams. This article previews the strategic value of the full study while preserving the detailed segment-level datasets and proprietary model that subscribers will find on the report site.
Autonomous Cars Market
Market trajectory and strategic takeaways
- Acceleration to commercial scale: The market’s trajectory shows a pronounced inflection beginning post‑2025, driven by cost optimization in sensing stacks, software maturity, and early fleet scale economies. Boards should expect a transition from grants and pilots to revenue-bearing deployments in target corridors.
- High-growth, still-fragmented structure: Despite fast growth, industry concentration remains modest; the top three firms control less than one-third of the market and the top five roughly a third—underscoring opportunity for fast followers and specialist suppliers to capture niche value.
- Capital and unit economics matter more than capability alone: The path to profitability depends as much on reducing per‑vehicle system cost and operational dispatch economics as it does on algorithmic performance. Firms that crack repeatable cost curves will set the platform economics for ride‑hail, logistics, and commercial vehicles.
What PW Consulting’s report delivers (practical components)
The full study is designed to be a working tool for management teams. Highlights include:
Autonomous Cars Market
- Interactive market model (2020–2032) with scenario toggles for regulatory openness, sensor-cost deflation, and fleet utilization rates — enabling quick sensitivity testing of investment cases.
- Commercial readiness scorecards for 40+ product and service archetypes, ranking where technology risk, regulatory exposure, and unit economics create opportunity or bottleneck.
- Playbooks for five corporate archetypes — incumbent OEM, Tier‑1 supplier, deep‑tech startup, fleet operator, and public‑transport authority — with tailored KPIs, pilot design templates, and go‑to‑market sequencing.
- Regulatory mapping and stakeholder heatmap across key markets, including scenario analysis for likely rule changes and reporting requirements that will influence deployment cadence.
- M&A and partnership heatmaps identifying capability gaps, logical acquisition targets, and timing windows to accelerate scale without overpaying for early hype.
These tools are structured to be used in boardroom discussions, capital allocation models, and product roadmaps. The report intentionally refrains from presenting raw, unlockable segment tables in this preview; detailed split-level revenue and regional allocations are available within the subscriber portal.
Competitive landscape — positioning and strategic implications
The industry’s competitive topology is best understood as an ecosystem battle among fleet operators, vehicle manufacturers, and specialist software/hardware suppliers. Below we synthesize how key players are shaping industry dynamics and what that means for strategic decision-makers.
- Waymo (Operator & Technology Provider) — Waymo has matured into one of the most advanced commercial operators of driverless ride‑hail services. Its iterative sensor and software development, most recently exemplified by a sixth‑generation driver update, emphasizes in‑house integration and cost discipline. For incumbents, Waymo’s model illustrates the combined advantage of operational data capture plus verticalized stack control; for suppliers, it signals that scale customers will increasingly demand low-cost, high‑reliability subsystems.
- Tesla (OEM + Software Platform) — Tesla’s approach integrates advanced driver assistance and automated driving capabilities directly into consumer vehicles at scale. Its path to unsupervised autonomy takes advantage of a massive fleet for data and iterative over‑the‑air improvements. For OEMs and software suppliers, Tesla highlights the strategic premium of fleet‑level data and software monetization, and the necessity of aligning hardware roadmaps with long-term software ambitions.
- Zoox (Purpose-built Robotaxi Operator) — Zoox demonstrates the alternative strategy of designing purpose‑built platforms for ride‑hail, optimizing vehicle architecture and operations around shared mobility economics. Zoox’s regulatory engagements and petitions for novel vehicle forms show how design innovation and regulatory strategy can be combined to create defensible operating models in urban cores.
- Mobileye (Chip and Software Supplier) — Mobileye’s role as a supplier of SoCs and perception stacks underscores the continuing importance of high‑performance, automotive‑grade compute. Mobileye illustrates a path where broad automaker relationships and scalable silicon can accelerate the deployment of Level 3+ capabilities while enabling incremental monetization through feature licensing.
- BMW Group and Mercedes‑Benz Group (OEMs with Level‑3 Deployments) — These OEMs represent the incumbent‑manufacturer playbook: incremental automation features, deep integration with vehicle systems, and regulatory-first commercialization. Their production Level‑3 offerings validate a staged consumer pathway to increased autonomy. Strategic partners should consider how to align feature rollouts with regulatory approvals and service propositions that preserve brand value.
Regulatory and technology inflection points to incorporate into 2026 plans
- Regulatory frameworks are becoming clearer — and actionable: Since 2025 the U.S. has signaled a constructive path: new frameworks emphasize safety while opening commercial pathways and streamlined reporting. The National Highway Traffic Safety Administration’s (NHTSA) frameworks and subsequent rulemaking reduce certain frictions, but they also introduce new reporting obligations that will shape operational compliance costs and go‑to‑market sequencing.
- Public safety convenings matter for licensing and public perception: NHTSA’s national AV safety forum in 2026, convening major operators and OEMs, marks a shift from siloed pilots to coordinated industry‑government engagement. Expect future approvals to favor operators demonstrating robust safety governance and transparent reporting.
- Vehicle form‑factor and equipment rules are changing: Recent government proposals to relax legacy equipment mandates (e.g., exemptions for mirrors under certain conditions) create design space for purpose‑built solutions, but they also raise new legal and insurance considerations that companies must model in their risk frameworks.
- Sensor-cost and integration: the new battleground: Advances in sensor stacks — including cost‑reduction strides in lidar, camera fusion, and purpose silicon — are rapidly altering unit economics. Companies that align procurement, in‑house design, and long‑term silicon roadmaps will gain a sustained cost advantage.
2026 playbook — three strategic moves for executives
We recommend that leadership teams treat 2026 as a decisive year for capability and portfolio configuration. The following three moves should be prioritized and stress‑tested against PW Consulting’s interactive model.
- Lock in data and operational feedback loops: Prioritize pilots and partnerships that provide meaningful operational data (edge cases, fault modes, utilization metrics). Data ownership will be the single most valuable intangible as the market moves from capability validation to cost optimization.
- Build optionality into capital allocation: Adopt staged funding with clear de‑risking milestones tied to sensor cost declines, regulatory approvals, and utilization thresholds. Avoid large, irreversible capital outlays before predictable operational economics emerge.
- Operationalize regulatory engagement: Insert dedicated regulatory liaisons into deployment programs and pursue cooperative pilots with safety agencies. Early alignment on reporting templates and safety governance reduces approval lag and mitigates reputational risk.
How boards and investors should use the full report
Boards should use the full study to translate macro growth potential into quantifiable investment triggers. The report’s scenario engine allows CFOs to test IRR outcomes against variations in capital intensity, fleet utilization, and regulatory timelines. Corporate development teams will find the M&A heatmap and supplier evaluations particularly valuable for prioritizing target diligence. And product leaders should use the consumer readiness assessments and feature‑monetization frameworks to shape roadmaps that match payer willingness with technical feasibility.
Concluding note — why read the full study
This preview outlines the strategic contours executives must navigate in 2026: rapid market expansion, persistent fragmentation, regulatory evolution, and intense competition between platform owners and component specialists. The full PW Consulting Autonomous Cars Market report contains the granular inputs—segment‑level projections, regional scenario matrices, and the live financial model—that allow you to convert these strategic insights into executable plans. Consider this article a trailer: it demonstrates the analytical depth and actionable orientation of the study while preserving the detailed datasets and modeling logic for subscribers who are preparing to make consequential decisions in 2026.
To convert strategy into execution, download the complete report and interactive model from our research portal. PW Consulting’s advisory teams are available to run custom workshops and scenario stress‑tests to align your 2026 capital and product decisions with the most likely market paths.
For detailed analysis of this topic, please visit the official page: Autonomous Cars Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vehicle Intercom Market Set to Grow at 8.37% CAGR (2026-2032)
By pmarketresearch, 2026-07-13
Vehicle Intercom System Market — Strategic Preview for 2026
As defence and professional vehicle platforms migrate from analog assemblies toward software-enabled communications suites, the vehicle intercom systems market is reaching an inflection point that demands executive attention in 2026. PW Consulting’s new study frames this industry not as a niche cabling problem but as a strategic node where vehicle survivability, crew effectiveness, and platform lifecycle economics converge. This preview highlights the study’s strategic value for corporate leaders, procurement officers, and product strategists while preserving the granular segment-level intelligence for subscribers.
Vehicle Intercom System Market
Macro view: steady expansion underpinned by defense and mission-critical demand
Between 2020 and 2025 the global vehicle intercom systems market expanded from approximately USD 0.94 million to USD 1.53 million (base year 2025). Our forecast maps a continuation of this momentum into the 2026–2032 period with a compound annual growth rate near 8.4%, and a market size approaching USD 2.7 million by 2032. These macro datapoints mask a more nuanced reality: growth is concentrated in ruggedized, integrated, and service-centric offerings sold into mission-critical vehicle fleets rather than commodity in-vehicle audio kits.
Vehicle Intercom System Market
For decision-makers, this means three immediate implications:
Vehicle Intercom System Market
- Revenue upside is real but concentrated: leading suppliers continue to capture disproportionate share through bundled hardware + services offerings and platform-level integrations.
- Product strategy must prioritize integration and lifecycle services—new orders are increasingly accompanied by maintenance and spare-part contracts, elongating revenue streams.
- Procurement cycles lengthen and grow more complex as systems become software-defined and require interoperability with tactical radios, VoIP backbones, and vehicle networks.
Why 2026 is a pivotal planning year
Several operational dynamics make strategic choices taken in 2026 disproportionately influential on outcomes through the next procurement cycle:
- Large-scale defense refresh programs and tactical vehicle modernizations are entering contracting windows; suppliers who demonstrate field-proven integrations will secure follow-on orders and sustain aftermarket revenue.
- The shift from purely wired to hybrid wired-wireless and IP-enabled intercom topologies accelerates requirements for cybersecurity certification and software maintenance roadmaps.
- Market concentration metrics reveal material consolidation: the top three firms hold a majority of market share while the top five control an even larger portion, raising both competitive and M&A considerations for mid-tier players.
Technology and procurement dynamics shaping supplier selection
Our analysis synthesizes field evaluations, supplier disclosures, and tender activity to identify the capability vectors that buyers will demand most in 2026:
- Rugged, noise-resistant audio and voice processing optimized for high-noise platforms remain table stakes—vendors differentiating on active noise suppression and crew situational awareness will outperform.
- Seamless integration with vehicle radio systems and VoIP/IP networks is increasingly non-negotiable. Buyers prize suppliers who can deliver validated interfaces and a predictable certification path.
- Wireless intercom components are growing in importance for rapid-deployment and dismounted-crew use cases, but migration is incremental; the interoperability between wired backbone and wireless adjuncts is a key technical challenge.
- Service models—extended warranties, logistics spare allocation, and regional maintenance partnerships—are driving lifetime value, changing the calculus from one-time sale to multi-year contracts.
Competitive landscape — what executives need to know
PW Consulting’s study profiles the incumbent and emerging suppliers shaping the market. A high-level synthesis follows; the full competitive matrices and supplier scorecards are available in the report.
- David Clark Company — Known for rugged digital and wireless intercom solutions tailored to high-noise environments and vehicle platforms. Their strength is product robustness and a long history in crew communication systems; competitive opportunities arise where digital migration and wireless add-ons are required.
- INVISIO — A specialist in wireless intercom systems that integrate closely with vehicle radio platforms for military and professional users. Recent contract activity and elevated order intake have reinforced their role as a strategic supplier to defense programs. Their positioning highlights the market’s tilt toward integrated radio-intercom solutions.
- Chelton — Offers tactical vehicle intercoms with VoIP integration, reflecting the industry’s shift to IP-enabled vehicle architectures. Chelton’s product set appeals to programs prioritizing network convergence and modular architecture.
- C-AT Communications (Applied Technology) — Focused on tactical “ComForce” systems for armored platforms, with a strong presence at specialist trade events and with end-users that require armored-vehicle hardened solutions. Their engagements underscore the continued importance of platform-specific engineering.
- WolfElec Intercoms — Markets intercom systems originally designed for ballistic-protected vehicles and continues to serve armored and security-focused vehicle segments. Their niche focus exemplifies the value of specialization in securing certain vehicle classes.
Across this competitive set, common themes emerge: emphasis on ruggedization, integration with radios and IP networks, and the bundling of services that extend beyond the sale. For potential entrants or buyers seeking to reshuffle supplier bases, the market’s degree of concentration means strategic partnerships or bolt-on acquisitions are viable paths to scale faster than organic growth alone.
Market dynamics and regulatory context
Recent industry activity—public procurement, large order flows, and supplier disclosures—confirms that defense and public-safety procurement is a principal growth engine. Several recent contract awards and high order-intake announcements by market-leading vendors point to sustained procurement flows and the bundling of intercom systems into broader radio and comms packages. Procurement teams should interpret these signals as indicators of ongoing government and institutional demand; however, contract structures are evolving to emphasize lifecycle support and interoperability requirements.
Regulatory and export-control regimes, combined with defense procurement rules, have practical effects that buyers and suppliers must budget for in 2026. Compliance timelines, regional certification requirements, and offsets can materially affect delivery schedules and total cost of ownership.
What the full report delivers — practical, transaction-ready outputs
PW Consulting’s full Vehicle Intercom System Market study is intentionally operational. Subscribers receive:
- Demand modeling with scenario variants tied to defense procurement timelines and commercial fleet refresh cycles.
- Supplier scorecards and comparative capability matrices that weigh technical features, field-readiness, and aftermarket support.
- Go-to-market playbooks for OEMs and Tier‑1 integrators, including partner-mapping and licensing strategies for IP-enabled platforms.
- Procurement templates and negotiation scripts designed to secure lifecycle support, spare-part availability, and software maintenance SLAs.
- Risk registers and mitigation roadmaps addressing supply chain bottlenecks, obsolescence of legacy interfaces, and cybersecurity certification pathways.
- Strategic M&A screening filters informed by market concentration metrics and leading-edge capability gaps.
Each output is supplied with actionable recommendations and a prioritized implementation timeline calibrated for 2026 decision cycles.
Recommended executive actions for 2026
Based on our synthesis of market growth projections, supplier behavior, and technical trajectories, PW Consulting advises leaders to pursue a three-track approach this year:
- Immediate (0–12 months): lock in critical spares and maintenance arrangements for at-risk platforms; validate supplier interoperability claims through staged integration tests; and secure short-term contracts that include clear upgrade paths.
- Near-term (12–24 months): invest in modular, software-upgradable intercom architectures and formalize partnerships with radio-system integrators; evaluate potential strategic acquisitions to plug capability gaps or accelerate access to defense procurement channels.
- Medium-term (24–48 months): build out service-delivery capabilities in target regions and develop a cybersecurity and certification roadmap for IP-enabled intercom solutions to defend against contractability risks.
How to use this study in your 2026 planning
This research is intended as a decision-support instrument: finance teams will find the demand scenarios useful for revenue planning and valuations; procurement and program managers will gain leverage from supplier risk assessments and procurement templates; product teams can benchmark roadmaps against field-proven features and aftermarket practices. Because the market is both consolidating and technology-driven, the right combination of near-term supplier risk mitigation and medium-term product investment will determine market winners.
Closing note — the deeper intelligence is gated for subscribers
This preview highlights the strategic contours and actionable priorities that should inform 2026 decisions. The full PW Consulting Vehicle Intercom System Market report contains the detailed datasets, regional and application splits, supplier scorecards, and contract-level case studies that underpin the recommendations summarized here. To access the complete intelligence, including the granular segmentation and downloadable spreadsheets used for our demand forecasting and competitive benchmarking, please consult the report landing page.
For detailed analysis of this topic, please visit the official page: Vehicle Intercom System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Heat Transfer Equipment Market set to hit USD 159.55 Million by 2032; 4.8% CAGR
By pmarketresearch, 2026-07-13
Heat Transfer Equipment Market — Strategic Outlook for 2026
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present an executive introduction to our Heat Transfer Equipment Market study — a decision-grade intelligence product calibrated for C-suite and investor decisioning in 2026. The report synthesizes historical performance (2020–2025), establishes a 2025 base year, and delivers scenario-based forecasts across the 2026–2032 horizon. At the macro level the market has expanded from USD 90.0 Million in 2020 to USD 114.95 Million in 2025 and is projected to reach approximately USD 159.55 Million by 2032, reflecting a steady compound annual growth rate (CAGR) of 4.8% (USD, Million). This introduction highlights why that trajectory matters to executives today while intentionally preserving the granular segmentation intelligence contained in the full report.
Heat Transfer Equipment Market
Why this study matters for 2026 decision-making
-
Actionable timing: The market’s mid-single digit CAGR signals predictable growth but not runaway expansion — a dynamic that rewards disciplined capital allocation and targeted innovation rather than broad-based scaling.
Heat Transfer Equipment Market -
Portfolio prioritization: Mature segments and high-capex end markets require different commercial approaches (service-led, aftermarket-focused) than lower-capex, rapidly modularized niches. Knowing which approach maps to specific product lines is a typical 2026 board-level question our study helps answer.
Heat Transfer Equipment Market -
Regulatory and technology inflection points: Recent approvals and design trends are reshaping product architectures. Firms that align R&D, regulatory strategy, and go-to-market around these inflections can translate modest market growth into outsized returns.
-
Competitive clarity: Market concentration metrics (CR3 ~42.5% and CR5 ~58.2%) show a sector with meaningful incumbent power but room for disruptive challengers — a setup that invites M&A, focused organic growth, and selective vertical integration.
Market dynamics to watch in 2026
-
Decarbonization and efficiency mandates: Industry-wide pressure to reduce energy intensity continues to drive demand for higher-efficiency heat exchangers and integrated thermal systems. Buyers increasingly evaluate lifecycle cost, not just CAPEX.
-
Electrification and process electrics: As certain industrial thermal loads transition to electrified sources, product design requirements shift (precision control, materials compatibility, and modularity). These transitions create niches for specialized vendors and service providers.
-
Regulatory developments with cross-sector implications: Medical device clearances for integrated stainless-steel heat exchangers highlight how regulation can accelerate adoption in regulated subsegments. A notable example in early 2026 saw U.S. clearance and subsequent commercialization activity for cardiopulmonary devices that include integrated heat exchange components — a reminder that regulatory wins can create new addressable markets overnight.
-
Supply chain and materials volatility: Raw material cycles, lead times for specialty alloys, and fabrication capacity constrain the speed at which suppliers can scale. The report models supplier concentration, single-source risks, and mitigation levers.
Competitive landscape — what top players signal
The competitive map spans long-established industrial fabricators, specialized OEMs for critical applications, and a growing set of niche device manufacturers whose heat-exchange components are increasingly mission-critical. Two illustrative firms covered in depth in the full study are:
-
Nipro Corporation (Osaka, Japan): A specialist whose cardioplegia heat exchangers — using a U-shaped spiral design — demonstrate how precision medical-application engineering translates into defensible IP and premium pricing in adjacent industrial segments. Nipro’s focus underscores the cross-pollination between medical and industrial heat-exchange technologies, particularly where biocompatible materials and tight thermal control matter.
-
Medtronic plc (Dublin, Ireland): Through products such as the ECMOtherm II, Medtronic illustrates how large, diversified medical OEMs position heat-exchange capability as part of a systems offer (device + consumables + service). Their model highlights the commercial value of bundled aftercare and consumable streams in stabilizing margins.
We also track up-and-coming commercialization moves. A recent regulatory milestone in March 2026 — the U.S. authorization and subsequent commercialization of cardiopulmonary oxygenators with integrated stainless-steel heat exchangers — demonstrates how certification can spur market entry and downstream supply chain shifts. For manufacturers and investors, this is a practical indicator: regulatory clarity reduces time-to-revenue for compliant designs and can materially change competitive dynamics.
What the report delivers — practical and operational content
This study is deliberately structured for immediate operational use by strategy, product, commercial, and M&A teams. Highlights include:
-
Robust market sizing and trend analytics: year-by-year historicals (2020–2025), 2025 base-year calibration, and multiple forecast scenarios across 2026–2032 with sensitivity to fuel/pricing, regulatory, and technology adoption assumptions.
-
Scenario playbooks: three path-dependent scenarios (Baseline, Accelerated Efficiency, and Disruptive Entry) that map revenue outcomes, margin pressure points, and CAPEX pacing to distinct competitive actions.
-
Technology and product roadmap: assessment of incumbent architectures, emergent materials, and modular designs — paired with recommended R&D priorities and expected TTM (time-to-market) for incremental improvements.
-
Go-to-market and aftermarket strategies: segmentation of buyer economics, service revenue levers, and pricing frameworks to optimize lifetime value (LTV) for long-cycle industrial customers.
-
Supply-chain risk matrix: supplier concentration mapping, lead-time stress tests, alternative sourcing pathways, and inventory hedging approaches designed for 2026 procurement cycles.
-
Competitive profiles and M&A targets: detailed company dossiers, capability maps, and valuation primitives for inorganic options — including integration risks and potential synergies.
-
Regulatory tracker and playbook: a rolling tracker of jurisdictional approvals and compliance requirements (including recent device-specific approvals), with recommended submission strategies and regulatory timelines for prioritized markets.
-
Financial toolkit: downloadable modeling templates, scenario-adjustable forecasts, and investor slide decks calibrated to board and front-office needs.
Strategic questions the report helps answer in 2026
-
Should we prioritize aftermarket service expansion or product-capacity growth? The report quantifies payoff matrices for each route by lifecycle cohort.
-
Where does consolidation create value? Using concentration indices and M&A casework, we identify which combinations unlock cost synergies versus revenue uplift.
-
How to hedge regulatory and materials risk? The study prescribes contractual, sourcing, and product-design mitigations tied to realistic timelines for approvals and material cycles.
-
Which technology bets are necessary versus optional? By mapping adoption curves to margin impact, the report shows which R&D bets are justified under conservative and aggressive scenarios.
How to use the intelligence — practical next steps
-
For manufacturers: align 2026 capex with the report’s scenario outputs — prioritize investments that increase aftermarket capture and reduce lead-time exposure.
-
For investors and private equity: use the M&A target dossiers and concentration metrics to screen deals that deliver scale benefits or proprietary technology access.
-
For procurement and supply-chain leaders: deploy the supply-risk matrix to renegotiate terms and implement dual-sourcing strategies for critical alloys and components.
-
For product and regulatory teams: adopt the regulatory tracker and playbook to compress approval timelines in high-value subsegments where certification unlocks new commercial channels.
Final observation and call to action
The Heat Transfer Equipment Market in 2026 sits at a strategic inflection: steady overall growth (CAGR 4.8%), clear pockets of regulatory-driven acceleration, and a competitive map that rewards focused, capability-driven moves. The full PW Consulting report contains the granular segmentation, regional and application-level detail, and financial models necessary to convert insight into action — data we deliberately withhold in this preview to protect the analytic value of the deliverable and to maintain our clients’ competitive advantage.
Access the comprehensive study for the full dataset, segmented demand maps, vendor scorecards, and downloadable modeling tools. PW Consulting’s methodology, scenario inputs, and validation approach are documented in the appendix for audit-ready transparency. If you are making strategic bets in 2026 — whether deploying capital, negotiating supplier terms, or planning a product roadmap — this report is designed to be the operational backbone of that decision.
For detailed analysis of this topic, please visit the official page: Heat Transfer Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electric Furnace Transformer Market Poised for 4.0% CAGR Through 2032
By pmarketresearch, 2026-07-13
Electric Furnace Transformer Market: Strategic Imperatives for 2026 — A Preview
Executive summary
The Electric Furnace Transformer market has moved from recovery into a phase of steady, structural growth. Our PW Consulting analysis shows the global market expanding from approximately USD 830 million in 2020 to USD 1,000 million in 2025, and — under the central case — reaching just over USD 1.3 billion by 2032 at a 4.0% compound annual growth rate (CAGR) through the 2026–2032 forecast horizon. For executives planning capital allocation, supply‑chain resilience, product strategy, or M&A in 2026, this research transforms headline growth statistics into actionable decision levers.
Electric Furnace Transformer Market
Why this briefing matters for 2026 strategic decisions
Two dynamics define the 2026 agenda for buyers, OEMs, and investors in electric furnace transformers (EFTs): (1) sustained, moderate market expansion that rewards disciplined scale and differentiation; and (2) a rapidly shifting cost and regulatory environment that elevates operational risk if not actively managed. This combination turns seemingly incremental market growth into a battleground for margin preservation and selective share capture.
Electric Furnace Transformer Market
- Capital planning: a predictable multi‑year growth path (4.0% CAGR) enables staged capacity investments rather than large, binary expansions. Companies that phase investments aligned to demand lags will outperform peers on utilization and ROIC.
- Supplier strategy: input cost volatility — most notably copper and insulation materials — requires integrated procurement playbooks and multi‑sourcing. Hedging and long‑term off‑take contracts will move from optional to essential in 2026.
- Regulatory positioning: tightening energy efficiency and emissions rules, coupled with industry standardization efforts, shift product roadmaps. Firms that front‑load compliance and capture the standardization conversation will gain advantage in tender processes and in value‑added services.
Market trajectory & implications
The market’s historical path demonstrates resilience: a steady recovery through 2020–2025, culminating in a USD 1 billion baseline in 2025. The forecast to 2032 reflects a mature industrial demand profile — driven predominantly by steelmaking and heavy metallurgical applications — and a growing need for higher‑reliability and higher‑current designs. That said, the aggregate growth conceals important commercial inflection points that buyers and suppliers must map to their product and operational strategies.
Electric Furnace Transformer Market
For 2026 specifically, the implication is clear: the environment favors focused competitors that can combine technical differentiation (e.g., high‑current designs, rectifier/series reactor integration, high‑frequency response) with robust cost mitigation against raw‑material headwinds. Tactical responses that will determine 2026 outcomes include selective SKU rationalization, targeted retrofit offerings, and service‑led revenue models for lifecycle optimization.
What the PW Consulting report delivers (practical, board‑ready content)
Our full research package is designed as a toolset for strategy teams and procurement committees. The content is highly operational and intended to support immediate 2026 decision cycles:
- Top‑down market sizing and a bottom‑up forecast model with scenario toggles for commodity price shocks and regulatory acceleration.
- Segment performance maps (by voltage class, application, and region) with demand drivers and risk indicators — note: this preview omits the granular segment tables; full detail is available in the complete report.
- 57‑page competitor benchmarking with capability matrices, technology positioning, and tender win‑loss archetypes.
- Procurement playbook: supplier scorecards, RFQ templates adapted to furnace‑duty specifications, and total cost of ownership (TCO) models for bid evaluation.
- Supply‑chain stress tests showing the P&L and delivery impact of commodity shocks and single‑source dependencies.
- Regulatory roadmap and compliance checklists aligned to emerging regional standards and the latest IEEE standardization effort for AC Electric Arc Furnace transformers.
- M&A and partnership framework that translates market concentration dynamics and capability gaps into priority targets and value creation pathways.
Competitive landscape: who matters and why
The market shows a mix of global technology leaders, regional specialists, and high‑volume manufacturers. Competitive positions vary by technical capability, scale, and proximity to heavy industrial clusters.
- GE Vernova — Positioned as a premium global supplier with offerings that span medium to ultra‑high voltage and specialized EAF units up to the highest MVA classes commonly specified by large steelmakers. Their strengths lie in system integration, R&D depth, and service networks that support large OEMs and utilities.
- Large Chinese manufacturers (examples include TBEA, Shenda, Ningbo Sinopower, Luoyang Xinghe, SCOTECH, Jiangsu Yawei) — These players combine scale manufacturing with aggressive export strategies. Their recent deliveries include very high‑MVA units and a focus on cost competitiveness and localized design variants for key markets.
- Indian specialists (examples include Makpower, KVA Process, Jaybee, Uratransformers) — These firms differentiate through high‑customization for steel and aluminum melting furnaces, designing low‑voltage, high‑current transformer solutions and rapid domestic deployment capabilities for regional steel clusters.
- Mid‑tier specialists — A set of focused companies offer niche capabilities (e.g., rectifier transformers, series reactors, rapid retrofit modules) that make them attractive partners for system integrators and service providers targeting lifecycle revenue.
Collectively, the competitive map rewards three go‑to moves in 2026: (1) deepen technical differentiation in thermal and short‑circuit performance; (2) build service and retrofit propositions to monetize installed bases; (3) hedge manufacturing footprint with regional partnerships to mitigate freight and tariff risks.
Raw material and regulatory dynamics — near‑term risk amplifiers
Two external variables dominate the short‑term risk matrix.
- Raw materials: Copper content per transformer unit remains material to total cost (industry analyses point to a substantial percentage of unit weight), and copper market disruption has direct, near‑real impacts on margins. Notably, copper prices spiked to record levels in early 2026, amplifying the need for procurement hedges or design substitutions where technically viable.
- Regulation and standards: Authorities in multiple jurisdictions are tightening emissions and energy efficiency expectations for heavy industrial operations. At the same time, the metals sector is progressing a new IEEE standard for AC Electric Arc Furnace transformers — an initiative that will influence specification commonality and bidder comparability from 2026 onward.
These forces mean that product teams and procurement must work in lockstep: small improvements in copper utilization, insulation efficiency, or thermal performance can shift competitive sourcing outcomes and tender economics within the year.
How to use the forecast and scenarios in 2026 planning cycles
We advise three concrete applications of the report in near‑term decision routines:
- Board‑level capital allocation: Use the staged demand forecast to prioritize modular capacity expansions rather than greenfield megaprojects. Our scenario module lets CFOs test outcomes under varying commodity and regulatory regimes.
- Procurement and contract design: Adopt the report’s supplier scorecards and TCO templates in upcoming RFQs. Require suppliers to present lifecycle cost sensitivity to copper and insulation price moves as part of bids.
- Product roadmap and compliance: Use the regulatory mapping and standardization timeline to fast‑track compliance‑led features into the next product generation; position these as bid differentiators in tenders expected in 2026–2027.
Recent market signals you cannot ignore
Exhibitions and trade events in late 2025 and early 2026 have signaled continuing product innovation and renewed supplier marketing intensity. Leading companies demonstrated advanced insulation systems, rectifier‑ready units, and component innovations at major shows. These displays indicate that suppliers are preparing for an era where product reliability and efficiency are decisive procurement criteria — not just price.
Concluding perspective — what to do next
For a 2026 playbook, adopt a three‑pronged approach: protect margins through disciplined procurement and design optimization; capture share through service and retrofit offerings; and de‑risk market access via regional manufacturing and standard compliance. The market's moderate overall growth (4.0% CAGR) rewards executional excellence more than speculative expansion. The full PW Consulting report equips your leadership team with the granular segmentation, vendor scorecards, and scenario models required to convert this strategic guidance into deliverables for 2026 board cycles.
Accessing the full intelligence
This preview intentionally highlights strategic findings while withholding the granular regional, voltage‑class, and application‑level tables that contain the actionable levers commercial teams need. To obtain the full dataset, model, and supplier benchmarking deliverables for use in tender evaluation and capital planning, please visit the PW Consulting report page or contact our industry practice. Our full report includes the complete segmentation matrices, downloadable forecast model, and customizable procurement templates designed for immediate deployment in 2026.
For detailed analysis of this topic, please visit the official page: Electric Furnace Transformer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com