

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Heat Transfer Equipment Market set to hit USD 159.55 Million by 2032; 4.8% CAGR

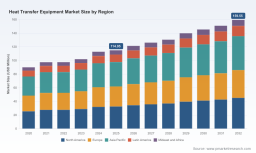
Heat Transfer Equipment Market — Strategic Outlook for 2026
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present an executive introduction to our Heat Transfer Equipment Market study — a decision-grade intelligence product calibrated for C-suite and investor decisioning in 2026. The report synthesizes historical performance (2020–2025), establishes a 2025 base year, and delivers scenario-based forecasts across the 2026–2032 horizon. At the macro level the market has expanded from USD 90.0 Million in 2020 to USD 114.95 Million in 2025 and is projected to reach approximately USD 159.55 Million by 2032, reflecting a steady compound annual growth rate (CAGR) of 4.8% (USD, Million). This introduction highlights why that trajectory matters to executives today while intentionally preserving the granular segmentation intelligence contained in the full report.
Heat Transfer Equipment Market
Why this study matters for 2026 decision-making
-
Actionable timing: The market’s mid-single digit CAGR signals predictable growth but not runaway expansion — a dynamic that rewards disciplined capital allocation and targeted innovation rather than broad-based scaling.
Heat Transfer Equipment Market -
Portfolio prioritization: Mature segments and high-capex end markets require different commercial approaches (service-led, aftermarket-focused) than lower-capex, rapidly modularized niches. Knowing which approach maps to specific product lines is a typical 2026 board-level question our study helps answer.
Heat Transfer Equipment Market -
Regulatory and technology inflection points: Recent approvals and design trends are reshaping product architectures. Firms that align R&D, regulatory strategy, and go-to-market around these inflections can translate modest market growth into outsized returns.
-
Competitive clarity: Market concentration metrics (CR3 ~42.5% and CR5 ~58.2%) show a sector with meaningful incumbent power but room for disruptive challengers — a setup that invites M&A, focused organic growth, and selective vertical integration.
Market dynamics to watch in 2026
-
Decarbonization and efficiency mandates: Industry-wide pressure to reduce energy intensity continues to drive demand for higher-efficiency heat exchangers and integrated thermal systems. Buyers increasingly evaluate lifecycle cost, not just CAPEX.
-
Electrification and process electrics: As certain industrial thermal loads transition to electrified sources, product design requirements shift (precision control, materials compatibility, and modularity). These transitions create niches for specialized vendors and service providers.
-
Regulatory developments with cross-sector implications: Medical device clearances for integrated stainless-steel heat exchangers highlight how regulation can accelerate adoption in regulated subsegments. A notable example in early 2026 saw U.S. clearance and subsequent commercialization activity for cardiopulmonary devices that include integrated heat exchange components — a reminder that regulatory wins can create new addressable markets overnight.
-
Supply chain and materials volatility: Raw material cycles, lead times for specialty alloys, and fabrication capacity constrain the speed at which suppliers can scale. The report models supplier concentration, single-source risks, and mitigation levers.
Competitive landscape — what top players signal
The competitive map spans long-established industrial fabricators, specialized OEMs for critical applications, and a growing set of niche device manufacturers whose heat-exchange components are increasingly mission-critical. Two illustrative firms covered in depth in the full study are:
-
Nipro Corporation (Osaka, Japan): A specialist whose cardioplegia heat exchangers — using a U-shaped spiral design — demonstrate how precision medical-application engineering translates into defensible IP and premium pricing in adjacent industrial segments. Nipro’s focus underscores the cross-pollination between medical and industrial heat-exchange technologies, particularly where biocompatible materials and tight thermal control matter.
-
Medtronic plc (Dublin, Ireland): Through products such as the ECMOtherm II, Medtronic illustrates how large, diversified medical OEMs position heat-exchange capability as part of a systems offer (device + consumables + service). Their model highlights the commercial value of bundled aftercare and consumable streams in stabilizing margins.
We also track up-and-coming commercialization moves. A recent regulatory milestone in March 2026 — the U.S. authorization and subsequent commercialization of cardiopulmonary oxygenators with integrated stainless-steel heat exchangers — demonstrates how certification can spur market entry and downstream supply chain shifts. For manufacturers and investors, this is a practical indicator: regulatory clarity reduces time-to-revenue for compliant designs and can materially change competitive dynamics.
What the report delivers — practical and operational content
This study is deliberately structured for immediate operational use by strategy, product, commercial, and M&A teams. Highlights include:
-
Robust market sizing and trend analytics: year-by-year historicals (2020–2025), 2025 base-year calibration, and multiple forecast scenarios across 2026–2032 with sensitivity to fuel/pricing, regulatory, and technology adoption assumptions.
-
Scenario playbooks: three path-dependent scenarios (Baseline, Accelerated Efficiency, and Disruptive Entry) that map revenue outcomes, margin pressure points, and CAPEX pacing to distinct competitive actions.
-
Technology and product roadmap: assessment of incumbent architectures, emergent materials, and modular designs — paired with recommended R&D priorities and expected TTM (time-to-market) for incremental improvements.
-
Go-to-market and aftermarket strategies: segmentation of buyer economics, service revenue levers, and pricing frameworks to optimize lifetime value (LTV) for long-cycle industrial customers.
-
Supply-chain risk matrix: supplier concentration mapping, lead-time stress tests, alternative sourcing pathways, and inventory hedging approaches designed for 2026 procurement cycles.
-
Competitive profiles and M&A targets: detailed company dossiers, capability maps, and valuation primitives for inorganic options — including integration risks and potential synergies.
-
Regulatory tracker and playbook: a rolling tracker of jurisdictional approvals and compliance requirements (including recent device-specific approvals), with recommended submission strategies and regulatory timelines for prioritized markets.
-
Financial toolkit: downloadable modeling templates, scenario-adjustable forecasts, and investor slide decks calibrated to board and front-office needs.
Strategic questions the report helps answer in 2026
-
Should we prioritize aftermarket service expansion or product-capacity growth? The report quantifies payoff matrices for each route by lifecycle cohort.
-
Where does consolidation create value? Using concentration indices and M&A casework, we identify which combinations unlock cost synergies versus revenue uplift.
-
How to hedge regulatory and materials risk? The study prescribes contractual, sourcing, and product-design mitigations tied to realistic timelines for approvals and material cycles.
-
Which technology bets are necessary versus optional? By mapping adoption curves to margin impact, the report shows which R&D bets are justified under conservative and aggressive scenarios.
How to use the intelligence — practical next steps
-
For manufacturers: align 2026 capex with the report’s scenario outputs — prioritize investments that increase aftermarket capture and reduce lead-time exposure.
-
For investors and private equity: use the M&A target dossiers and concentration metrics to screen deals that deliver scale benefits or proprietary technology access.
-
For procurement and supply-chain leaders: deploy the supply-risk matrix to renegotiate terms and implement dual-sourcing strategies for critical alloys and components.
-
For product and regulatory teams: adopt the regulatory tracker and playbook to compress approval timelines in high-value subsegments where certification unlocks new commercial channels.
Final observation and call to action
The Heat Transfer Equipment Market in 2026 sits at a strategic inflection: steady overall growth (CAGR 4.8%), clear pockets of regulatory-driven acceleration, and a competitive map that rewards focused, capability-driven moves. The full PW Consulting report contains the granular segmentation, regional and application-level detail, and financial models necessary to convert insight into action — data we deliberately withhold in this preview to protect the analytic value of the deliverable and to maintain our clients’ competitive advantage.
Access the comprehensive study for the full dataset, segmented demand maps, vendor scorecards, and downloadable modeling tools. PW Consulting’s methodology, scenario inputs, and validation approach are documented in the appendix for audit-ready transparency. If you are making strategic bets in 2026 — whether deploying capital, negotiating supplier terms, or planning a product roadmap — this report is designed to be the operational backbone of that decision.
For detailed analysis of this topic, please visit the official page: Heat Transfer Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com