

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Electric Furnace Transformer Market Poised for 4.0% CAGR Through 2032

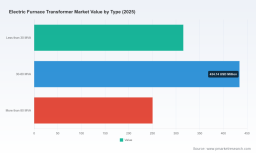
Electric Furnace Transformer Market: Strategic Imperatives for 2026 — A Preview
Executive summary
The Electric Furnace Transformer market has moved from recovery into a phase of steady, structural growth. Our PW Consulting analysis shows the global market expanding from approximately USD 830 million in 2020 to USD 1,000 million in 2025, and — under the central case — reaching just over USD 1.3 billion by 2032 at a 4.0% compound annual growth rate (CAGR) through the 2026–2032 forecast horizon. For executives planning capital allocation, supply‑chain resilience, product strategy, or M&A in 2026, this research transforms headline growth statistics into actionable decision levers.
Electric Furnace Transformer Market
Why this briefing matters for 2026 strategic decisions
Two dynamics define the 2026 agenda for buyers, OEMs, and investors in electric furnace transformers (EFTs): (1) sustained, moderate market expansion that rewards disciplined scale and differentiation; and (2) a rapidly shifting cost and regulatory environment that elevates operational risk if not actively managed. This combination turns seemingly incremental market growth into a battleground for margin preservation and selective share capture.
Electric Furnace Transformer Market
- Capital planning: a predictable multi‑year growth path (4.0% CAGR) enables staged capacity investments rather than large, binary expansions. Companies that phase investments aligned to demand lags will outperform peers on utilization and ROIC.
- Supplier strategy: input cost volatility — most notably copper and insulation materials — requires integrated procurement playbooks and multi‑sourcing. Hedging and long‑term off‑take contracts will move from optional to essential in 2026.
- Regulatory positioning: tightening energy efficiency and emissions rules, coupled with industry standardization efforts, shift product roadmaps. Firms that front‑load compliance and capture the standardization conversation will gain advantage in tender processes and in value‑added services.
Market trajectory & implications
The market’s historical path demonstrates resilience: a steady recovery through 2020–2025, culminating in a USD 1 billion baseline in 2025. The forecast to 2032 reflects a mature industrial demand profile — driven predominantly by steelmaking and heavy metallurgical applications — and a growing need for higher‑reliability and higher‑current designs. That said, the aggregate growth conceals important commercial inflection points that buyers and suppliers must map to their product and operational strategies.
Electric Furnace Transformer Market
For 2026 specifically, the implication is clear: the environment favors focused competitors that can combine technical differentiation (e.g., high‑current designs, rectifier/series reactor integration, high‑frequency response) with robust cost mitigation against raw‑material headwinds. Tactical responses that will determine 2026 outcomes include selective SKU rationalization, targeted retrofit offerings, and service‑led revenue models for lifecycle optimization.
What the PW Consulting report delivers (practical, board‑ready content)
Our full research package is designed as a toolset for strategy teams and procurement committees. The content is highly operational and intended to support immediate 2026 decision cycles:
- Top‑down market sizing and a bottom‑up forecast model with scenario toggles for commodity price shocks and regulatory acceleration.
- Segment performance maps (by voltage class, application, and region) with demand drivers and risk indicators — note: this preview omits the granular segment tables; full detail is available in the complete report.
- 57‑page competitor benchmarking with capability matrices, technology positioning, and tender win‑loss archetypes.
- Procurement playbook: supplier scorecards, RFQ templates adapted to furnace‑duty specifications, and total cost of ownership (TCO) models for bid evaluation.
- Supply‑chain stress tests showing the P&L and delivery impact of commodity shocks and single‑source dependencies.
- Regulatory roadmap and compliance checklists aligned to emerging regional standards and the latest IEEE standardization effort for AC Electric Arc Furnace transformers.
- M&A and partnership framework that translates market concentration dynamics and capability gaps into priority targets and value creation pathways.
Competitive landscape: who matters and why
The market shows a mix of global technology leaders, regional specialists, and high‑volume manufacturers. Competitive positions vary by technical capability, scale, and proximity to heavy industrial clusters.
- GE Vernova — Positioned as a premium global supplier with offerings that span medium to ultra‑high voltage and specialized EAF units up to the highest MVA classes commonly specified by large steelmakers. Their strengths lie in system integration, R&D depth, and service networks that support large OEMs and utilities.
- Large Chinese manufacturers (examples include TBEA, Shenda, Ningbo Sinopower, Luoyang Xinghe, SCOTECH, Jiangsu Yawei) — These players combine scale manufacturing with aggressive export strategies. Their recent deliveries include very high‑MVA units and a focus on cost competitiveness and localized design variants for key markets.
- Indian specialists (examples include Makpower, KVA Process, Jaybee, Uratransformers) — These firms differentiate through high‑customization for steel and aluminum melting furnaces, designing low‑voltage, high‑current transformer solutions and rapid domestic deployment capabilities for regional steel clusters.
- Mid‑tier specialists — A set of focused companies offer niche capabilities (e.g., rectifier transformers, series reactors, rapid retrofit modules) that make them attractive partners for system integrators and service providers targeting lifecycle revenue.
Collectively, the competitive map rewards three go‑to moves in 2026: (1) deepen technical differentiation in thermal and short‑circuit performance; (2) build service and retrofit propositions to monetize installed bases; (3) hedge manufacturing footprint with regional partnerships to mitigate freight and tariff risks.
Raw material and regulatory dynamics — near‑term risk amplifiers
Two external variables dominate the short‑term risk matrix.
- Raw materials: Copper content per transformer unit remains material to total cost (industry analyses point to a substantial percentage of unit weight), and copper market disruption has direct, near‑real impacts on margins. Notably, copper prices spiked to record levels in early 2026, amplifying the need for procurement hedges or design substitutions where technically viable.
- Regulation and standards: Authorities in multiple jurisdictions are tightening emissions and energy efficiency expectations for heavy industrial operations. At the same time, the metals sector is progressing a new IEEE standard for AC Electric Arc Furnace transformers — an initiative that will influence specification commonality and bidder comparability from 2026 onward.
These forces mean that product teams and procurement must work in lockstep: small improvements in copper utilization, insulation efficiency, or thermal performance can shift competitive sourcing outcomes and tender economics within the year.
How to use the forecast and scenarios in 2026 planning cycles
We advise three concrete applications of the report in near‑term decision routines:
- Board‑level capital allocation: Use the staged demand forecast to prioritize modular capacity expansions rather than greenfield megaprojects. Our scenario module lets CFOs test outcomes under varying commodity and regulatory regimes.
- Procurement and contract design: Adopt the report’s supplier scorecards and TCO templates in upcoming RFQs. Require suppliers to present lifecycle cost sensitivity to copper and insulation price moves as part of bids.
- Product roadmap and compliance: Use the regulatory mapping and standardization timeline to fast‑track compliance‑led features into the next product generation; position these as bid differentiators in tenders expected in 2026–2027.
Recent market signals you cannot ignore
Exhibitions and trade events in late 2025 and early 2026 have signaled continuing product innovation and renewed supplier marketing intensity. Leading companies demonstrated advanced insulation systems, rectifier‑ready units, and component innovations at major shows. These displays indicate that suppliers are preparing for an era where product reliability and efficiency are decisive procurement criteria — not just price.
Concluding perspective — what to do next
For a 2026 playbook, adopt a three‑pronged approach: protect margins through disciplined procurement and design optimization; capture share through service and retrofit offerings; and de‑risk market access via regional manufacturing and standard compliance. The market's moderate overall growth (4.0% CAGR) rewards executional excellence more than speculative expansion. The full PW Consulting report equips your leadership team with the granular segmentation, vendor scorecards, and scenario models required to convert this strategic guidance into deliverables for 2026 board cycles.
Accessing the full intelligence
This preview intentionally highlights strategic findings while withholding the granular regional, voltage‑class, and application‑level tables that contain the actionable levers commercial teams need. To obtain the full dataset, model, and supplier benchmarking deliverables for use in tender evaluation and capital planning, please visit the PW Consulting report page or contact our industry practice. Our full report includes the complete segmentation matrices, downloadable forecast model, and customizable procurement templates designed for immediate deployment in 2026.
For detailed analysis of this topic, please visit the official page: Electric Furnace Transformer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com