

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Quantum Computing Market to Hit USD 9.96B by 2032

Quantum Computing Market — Strategic Imperatives for 2026 Decision‑Making
Executive snapshot
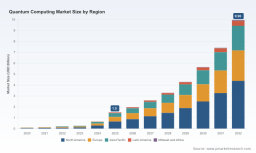
Quantum computing is transitioning from laboratory breakthrough to enterprise agenda item. Our latest PW Consulting market study, anchored on a 2025 base year and covering historical performance (2020–2025) with forecasts to 2032, places the industry on a sustained high‑growth trajectory. The market expanded rapidly over the first half of the decade—moving from single‑digit millions to a multi‑hundred‑million to low‑billion USD environment—and reached approximately USD 1.5 Billion in 2025. Under a central scenario, we model a robust compound annual growth rate of 29% through 2032, bringing the global market close to USD 10 Billion by the end of the forecast period.
Quantum Computing Market
That pace of expansion is not uniform: technology pathways (superconducting, trapped‑ion, photonic, annealing and others), infrastructure maturity (cloud access, colocated devices, dedicated on‑prem systems), and regulatory regimes all create pockets of rapid adoption alongside areas where integration remains nascent. This asymmetry is precisely why 2026 is a critical pivot year for corporate and public sector decision‑makers.
Quantum Computing Market
Why this report matters for 2026 strategy
Many organizations will face a classic build‑versus‑buy decision in 2026. Early adopters that delay architecture choices risk higher conversion costs and longer runways to production; those that commit too aggressively risk vendor lock‑in or stranded investments if competing modalities leapfrog expectations. Our study is designed to inform those tradeoffs with scenario‑driven, actionable guidance.
Quantum Computing Market
- Timing: Identify the commercial inflection points that matter for procurement windows, pilot budgeting, and multi‑year roadmaps.
- Risk management: Quantify operational and supply‑chain risks (device reproducibility, cryogenics, interconnects, component sourcing) and map mitigation levers you can implement today.
- Vendor strategy: Build a defensible partner portfolio—when to partner with hyperscalers, when to co‑invest with specialist vendors, and when to favor multi‑vendor/cloud neutrality to preserve optionality.
- Regulatory & geopolitical readiness: Translate export controls, domestic incentives, and regional industrial strategies into practical compliance and sourcing playbooks.
What’s inside the report — practical, transaction‑grade tools
The PW Consulting study is deliberately operational. Beyond high‑level forecasts and trend analysis, the report includes: scenario models (fast technical progress vs. conservative adoption), vendor due‑diligence templates, total cost of ownership models for cloud vs. on‑prem deployments, capex phasing roadmaps keyed to technical milestones, and an M&A playbook for acquiring quantum‑era IP and talent. We also provide implementation blueprints for use cases where quantum advantage is plausible in the near to mid term—covering optimization, simulation of complex materials/chemistry, and early hybrid classical‑quantum machine learning experiments.
- Interactive financial models you can parameterize with your own cost and revenue assumptions.
- Vendor scorecards and integration checklists for procurement teams.
- Regulatory compliance checklists aligned to recent export control and regional industrial policy changes.
- Workforce and skills transition plans to bridge classical HPC, AI, and quantum engineering teams.
Competitive landscape — capabilities, positioning, and tactical takeaways
The market is consolidating around a set of capability clusters rather than a single winner‑takes‑all outcome. Leading technology suppliers fall into distinct strategic typologies: hyperscale integrators offering cloud access and cross‑platform marketplaces; specialist device companies advancing particular qubit modalities; and vertically integrated vendors selling systems to research and national infrastructure customers.
- Hyperscale platforms: Established cloud providers are moving beyond access to build proprietary device capability and hybrid orchestration. Expect differentiated value from combined cloud, tooling, and data services that lower customer integration costs.
- Device specialists: Companies focused on one modality (superconducting, trapped‑ion, photonic, neutral‑atom, annealing, silicon spin, etc.) are executing on performance roadmaps—many are now offering cloud access and targeted commercial systems for application pilots.
- Systems integrators and regional champions: A cohort of firms is commercializing full‑stack solutions and selling into supercomputing centers, national labs, and industrial incumbents requiring on‑prem or dedicated installations.
Key examples from our competitive matrix (profiles included in full report): IBM’s superconducting roadmap and System One architecture; Google Quantum AI’s emphasis on error correction and logical qubits; Microsoft’s multi‑modal Azure Quantum strategy; Amazon Braket’s marketplace approach coupled with its proprietary cat‑qubit development; D‑Wave’s annealing platforms optimized for combinatorial optimization; IonQ and Quantinuum’s trapped‑ion advancements; photonics entrants targeting fault‑tolerant roadmaps; and regional players pursuing national infrastructure deployments. The leading vendors collectively produce a market that is moderately concentrated—top players hold substantial, but not overwhelming, shares—creating room for strategic partnerships and niche leadership.
Recent market catalysts and structural drivers
Several developments converging in 2024–2026 materially reshape strategic choices for 2026:
- Policy and incentives: Significant public programs and incentive agreements are accelerating domestic manufacturing and systems engineering priorities, with funds targeted at reproducibility, cryogenics, and interconnects—areas that materially affect supply‑chain risk and timing.
- Standardization and benchmarking: Regional standards initiatives and benchmarking coordination are beginning to create interoperable performance baselines—this will reduce buyer due diligence burden but also raise the bar for vendors that cannot demonstrate measurable benchmarks.
- Technological bottlenecks: Cryogenics, in‑vacuum control electronics, and error‑correction overhead remain primary engineering constraints. Advances in these areas materially shorten the time to commercially useful quantum workloads.
- Private capital and distributed systems: New funding rounds and commercial system launches—especially in distributed quantum networking and logical qubit demonstrations—signal that we are moving into a capital‑intensive commercialization phase where deployments will be differentiated by systems engineering and integration rather than raw qubit counts alone.
Strategic implications by decision area
- Procurement & architecture: Favor modular architectures that allow swap‑out of device providers and prioritize hybrid orchestration. Shortlist vendors based on integration overhead, not just headline qubit metrics.
- R&D and IP strategy: Participate in consortia and standards bodies to influence benchmarks and secure early access to interoperability frameworks; consider minority equity stakes or co‑development to secure priority roadmaps.
- Regulatory & supply chain: Reassess sourcing strategies in light of export control regimes and national industrial strategies—plan for segmented supply chains and localized redundancy for mission‑critical projects.
- Workforce & partnerships: Invest in cross‑training classical HPC and quantum engineers; prioritize partnerships with cloud providers for rapid pilot execution while building in‑house capability for differentiated production workloads.
What PW Consulting recommends today (high level)
- Adopt a two‑track strategy: run near‑term pilots to validate primitive advantage in tightly scoped use cases, while establishing architectural guardrails and supplier optionality to capture medium‑term production opportunities.
- Prioritize investments in integration: spend on systems engineering, cryogenic interfaces, and software toolchains now to reduce future migration costs.
- Engage in standards and policy dialogues: active participation shortens compliance timelines and can influence the shape of benchmarking that will determine procurement decisions.
- Use incentives strategically: align proposals to public funding that targets shared bottlenecks—this can materially accelerate timelines and lower capex.
Next steps — where to find the detailed intelligence
This article is a strategic preview. The full PW Consulting Quantum Computing Market report contains the granular segmentation, vendor scorecards, downloadable financial models, scenario dashboards, and step‑by‑step implementation guides that procurement, R&D and C‑suite teams will use to make defensible 2026 decisions. We have intentionally withheld detailed regional and application share tables in this preview to preserve the value of the complete dataset and analytic tools included in the full deliverable.
For organizations preparing to make procurement, partnership, or investment decisions in 2026, the complete report provides the transaction‑grade analysis required to move from pilot to production with confidence: side‑by‑side technology comparisons, detailed integration timelines, regulatory checklists, and bespoke advisory options from PW Consulting to tailor roadmaps to your strategic objectives.
Contact PW Consulting to access the full report, interactive models, and advisory engagement options to convert the quantum market’s projected growth into measurable business outcomes for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Quantum Computing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com