

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
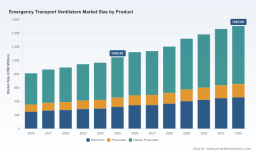
PW Consulting: Emergency Transport Ventilators Market to Top USD 1,046.95M in 2025 (5.36% CAGR)

Emergency Transport Ventilators Market — Strategic Briefing for 2026 Decision-Makers
As health systems, emergency medical services (EMS), and life‑science suppliers move from pandemic crisis response to durable readiness, emergency transport ventilators have shifted from episodic procurement items to strategic assets. PW Consulting’s latest market study — anchored on a 2025 base year and projecting through 2032 — synthesizes a seven‑year forecast, competitive positioning, regulatory dynamics, and actionable commercialization playbooks designed to inform board‑level and business unit decisions in 2026.
Emergency Transport Ventilators Market
Why this study matters in 2026
-
Market momentum is measurable and persistent. Our modeling shows the global emergency transport ventilator market expanded steadily through 2020–2025 and is forecast to continue growing in the 2026–2032 horizon at a compound annual growth rate (CAGR) of 5.36% (USD, revenue in Millions). This trajectory reflects durable demand from hospital networks, organized EMS, military and aeromedical operators, and an expanding remit for pre‑hospital critical care.
Emergency Transport Ventilators Market -
Strategic inflection points are clustered in 2026. Buyers will rethink capex allocation, suppliers will operationalize product roadmaps initiated during crisis years, and regulators and payers will increasingly shape procurement through standards, reimbursement structures, and clinical outcome requirements.
Emergency Transport Ventilators Market -
Decision relevance: for product leaders, the study translates market growth into prioritized feature roadmaps and certification timing; for commercial leaders, it identifies where to invest sales coverage and where to pursue partnerships; and for corporate development teams, it highlights consolidation vectors consistent with current market concentration.
Macro picture: trajectory, concentration, and tail risks
Using 2025 as the analytical baseline, the market registers meaningful scale and resiliency. After multi‑year recovery and modernization of EMS fleets, our 2026 forecast continues expansion toward the 2032 horizon. Market concentration is moderate and actionable: the top three suppliers capture a plurality of share while the top five control a clear majority — a structure that creates both competitive barriers and selective acquisition opportunities for challengers and incumbents alike.
These structural characteristics produce two practical effects for 2026 planning. First, established manufacturers retain advantage through installed base, service networks, and certifications that matter to air and ground transport operators. Second, there is still room for focused entrants that can pair differentiated technology with targeted distribution in underpenetrated segments or geographies.
Key industry dynamics shaping choices in 2026
-
Standards and regulatory gating. International standards that define safety and performance for EMS ventilators are now a baseline buyer requirement; compliance timelines and submission strategies (including 510(k) pathways where relevant) must be mapped into product roadmaps early to avoid launch delays.
-
Reimbursement and procurement economics. Reimbursement frameworks and hospital capital allocation continue to influence buyer willingness to invest in higher‑capability, higher‑priced transport ventilators. Buyers increasingly evaluate total cost of ownership, clinical outcomes, and interoperability with ICU workflows.
-
Supply‑chain and cost pressure. Medical device manufacturing has experienced step‑change cost pressures in recent years; procurement teams are tightening supplier qualification criteria and favoring partners that demonstrate resilient sourcing, predictable lead times, and cost containment strategies.
-
Certifications and operational approvals matter. Aviation and ambulance certifications, as well as proven performance in extreme‑environment and aeromedical contexts, materially affect competitive positioning for devices targeting air and military transport use cases.
Competitive landscape — what executives need to know
The market is served by a mix of global OEMs with broad acute‑care portfolios and specialist vendors focused on portable, mission‑critical devices. Leading players differentiate along a few predictable dimensions: clinical capability (ICU‑grade modes), mobility and robustness (battery, weight, environmental certifications), service and lifecycle support, and regulatory footprint. PW Consulting’s report profiles the full competitive set and provides strategic implications for each competitive archetype.
-
ZOLL Medical Corporation: recognized for robust portable platforms designed for EMS and aeromedical transport. Strengths include strong brand recognition among first responders and deep integration with emergency care ecosystems.
-
Hamilton Medical AG: positions its flagship transport ventilator with ICU‑level functionality for ground, air and water transport — a preferred choice where clinical parity with hospital ventilators is a procurement requirement.
-
WEINMANN and Dräger: European incumbents that combine reliability with extensive service networks; competitive advantages revolve around local approvals and after‑sales support for EMS providers.
-
Mindray, Comen, Amoul and other China‑based manufacturers: offer competitive value propositions and have advanced into certification for aviation and ambulance markets — creating options for cost‑sensitive buyers and emerging market tenders.
-
Specialist innovators (O‑Two, Impact Instrumentation, Inbentus): leverage turbine technology, compact form‑factors, and ruggedization to win narrowly defined mission profiles (e.g., battlefield, aeromedical, urban EMS).
Notably, several vendors continue to invest in multi‑mode capability (invasive and non‑invasive), battery endurance, and connectivity — capabilities that materially influence buying decisions in 2026 as systems aim for continuity of care from field to ICU.
Recent developments that recalibrate 2026 strategy
-
New product entries with aviation and ambulance certifications reinforce segmentation of demand by operational use case: innovations that shorten certification timelines or deliver dual‑certified devices can unlock premium contracts in aeromedical and defense sectors.
-
Regulatory approvals and 510(k) clearances for new models continue to set launch gates; product teams should factor in regulatory lead times and evidence generation into 2026 launch calendars.
-
Rising equipment costs and capital scrutiny are prompting procurement bodies to shift toward outcome‑based purchasing and service‑inclusive contracts — commercial teams must adapt pricing and warranty propositions accordingly.
What PW Consulting’s full report delivers (practical, executable content)
-
A calibrated market model with historical data (2020–2025) and granular forecasts through 2032, enabling scenario analysis across demand, price, and regulatory outcomes.
-
Segmentation logic and demand drivers by product, interface, and end‑use — with actionable implications for product roadmaps and sales prioritization. (Detailed segment numbers and region splits are reserved for the full report.)
-
Competitive dossiers on the leading suppliers with capability matrices, go‑to‑market strengths, and service coverage maps — including acquisition‑ready targets and integration playbooks for corporate development teams.
-
Regulatory and reimbursement navigator: maps of global approval pathways, compliance checklists for EMS standards, and payer levers that affect hospital and EMS purchasing.
-
Commercial and procurement playbooks: recommended contracting structures (e.g., capex replacement programs, managed service agreements), pricing levers, and case examples of successful procurement pilots.
-
Supply‑chain stress tests and sourcing strategies to mitigate raw‑material cost inflation and component shortages, with a focus on verticals that matter most to transport ventilator production.
Actionable recommendations for 2026 — three priorities
-
Embed regulatory and clinical evidence into product planning. Ensure new model timelines account for certification and clinical validation. Winning proposals to large EMS buyers and aeromedical integrators increasingly require documented compliance with EMS‑specific standards and clinical transition studies.
-
Reframe commercial offers around lifecycle economics. Pricing strategies that emphasize uptime guarantees, integrated consumable supply, and buyback/upgrade options will resonate in an era of constrained hospital capex and rising scrutiny on procurement ROI.
-
Targeted inorganic growth and partnerships. Given the market’s moderate concentration, bolt‑on acquisitions that deliver certifications, distribution reach, or unique operational features (e.g., aviation approvals, turbine technology) can accelerate scale and shorten time to market.
Risks and mitigation for 2026 planning
-
Regulatory bottlenecks: build contingency for longer than expected approval cycles and prioritize early dialogue with regulators and notified bodies.
-
Price and input cost volatility: negotiate multi‑year supply agreements and explore design adjustments that reduce exposure to scarce components without compromising performance.
-
Competitive margin pressure: differentiate on service, certification, and interoperability rather than competing solely on device price.
Conclusion — the strategic delta for 2026
For leaders deciding where to allocate R&D spend, how to structure sales coverage, or whether to pursue M&A in 2026, the essential insight is this: the emergency transport ventilator market is maturing into a strategic subsector of acute care equipment — one defined as much by certification, service economics and operational robustness as by unit price. Successful players in 2026 will combine timely regulatory execution, resilient manufacturing, and commercial propositions that reduce buyer risk across the device lifecycle.
PW Consulting’s full Emergency Transport Ventilators Market report provides the quantitative models, competitor playbooks, and procurement templates required to convert this strategic view into executable plans. For access to the detailed segmentation, regional analyses, and vendor scorecards that we intentionally withhold here, visit our report page or contact our industry practice to schedule a briefing tailored to your 2026 objectives.
For detailed analysis of this topic, please visit the official page: Emergency Transport Ventilators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com