

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: XRF Spectrometer Market Set for 6.98% CAGR (2026–2032)

X-ray Fluorescence Spectrometer Market: Strategic Imperatives for 2026 Decision-Makers
Executive preview
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a focused preview of our new X-ray Fluorescence (XRF) Spectrometer Market study. This briefing is written for corporate strategy teams, procurement leaders, product managers, and M&A executives who must make high-stakes decisions in 2026 informed by robust commercial and technical insight. The aim here is to surface the study’s strategic value and practical takeaways while preserving the detailed, segment-level intelligence that drives competitive advantage — that material is reserved for the full report.
X-ray Fluorescence Spectrometer Market
Why this research matters in 2026
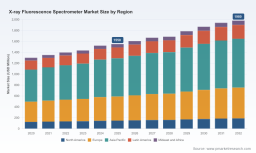
The XRF spectrometer market is in an established growth phase driven by ongoing industrial quality control demands, environmental regulation enforcement, and expanding field-testing use cases. PW Consulting’s market model — grounded on a 2025 base year with historical analysis from 2020–2025 and a forward-looking forecast covering 2026–2032 — quantifies this trajectory. The market expanded from roughly USD 1.3 billion in 2020 to about USD 1.55 billion in 2025, and our projections place it at approximately USD 1.98 billion by 2032, implying a compound annual growth rate (CAGR) of roughly 6.98% over the forecast window.
X-ray Fluorescence Spectrometer Market
Those headline numbers matter because they: (1) validate continued vendor investment and product refresh cycles; (2) underpin capex planning for industrial and laboratory buyers; and (3) signal an expanding aftermarket opportunity for services, consumables, and software-enabled analytics.
X-ray Fluorescence Spectrometer Market
What the full report delivers — operationally useful content
- Comprehensive market sizing and a transparent forecasting model (base year 2025; historical 2020–2025; forecast 2026–2032) with sensitivity analysis for macroeconomic and technology adoption scenarios.
- Segment-level demand drivers and end-user adoption pathways (by instrument type, application vertical, and geography) — note: segment breakdowns are included in the full report to support procurement and GTM decisions.
- Vendor landscaping with strategic profiles, product positioning maps, technology differentiation matrices, and a pragmatic vendor selection checklist for bench vs. handheld deployments.
- CapEx and total cost of ownership (TCO) frameworks that incorporate purchase cost ranges, service contracts, consumables, and lifecycle replacement timing.
- Use-case playbooks for environmental testing, mining & metals, pharmaceutical quality control, and industrial manufacturing, including measurement uncertainty considerations and sample-preparation trade-offs.
- M&A and partnership screening criteria, including a prioritized target list and a short due-diligence template for technology, go-to-market, and aftermarket synergies.
- An actionable supplier negotiation toolkit (including warranty and calibration service clauses) and a procurement scorecard for enterprise rollouts.
Key strategic implications for 2026 decisions
The following implications synthesize the report’s primary findings into immediate actions and decision frameworks:
- CapEx and procurement timing: With instrument prices spanning a broad range, buyers should align procurement with a 24–36 month roadmap that balances new product introductions and internal depreciation cycles. Our TCO framework models show that service and consumable economics materially affect lifecycle costs; decisions should therefore be vendor-agnostic at the purchase stage but service-aware in contracting.
- Fleet rationalization: Organizations operating mixed fleets of benchtop and portable XRF devices can often reduce cost-per-test by standardizing on fewer platforms while leveraging handhelds for field triage. The qualitative benefits of portability (reduced sampling time, field decisioning) must be balanced against laboratory precision needs.
- Aftermarket monetization: The projected market growth creates room for differentiated service models — subscription-based calibration, predictive maintenance tied to instrument telemetry, and consumable bundles. Vendors and service providers that convert installed bases into recurring revenue will capture disproportionate value.
- Regulatory and compliance risk: XRF instruments are subject to radiation-protection requirements and national regulations. Buyers must factor compliance costs (training, shielding, certifications) into procurement and site planning budgets.
- Product roadmap sensitivity: New model introductions and incremental improvements in detector technology or software analytics can influence replacement cycles. Procurement should include clauses to mitigate obsolescence risk when multiyear rollouts are planned.
Competitive landscape — how incumbents are positioning
The market remains moderately fragmented with leading vendors focusing on differentiated product stacks, service models, and niche verticals. Our review highlights several strategic archetypes and the practical implications for buyers and partners:
- SPECTRO (Germany): Strong in high-precision benchtop systems and established pharma use cases. SPECTRO emphasizes instrument accuracy and application-specific attachments — a good supplier where laboratory-grade repeatability is prioritized.
- Malvern Panalytical (UK): Offers a mix of benchtop and handheld solutions with a notable portfolio for powder and material analysis. Their strength is in integrated workflows from sample presentation to analytics — attractive for pharma and advanced materials labs.
- HORIBA (Japan): Competes on analytical robustness with solutions targeting both pharmaceutical and clinical materials testing. Their strategy blends instrumentation with ancillary measurement services.
- Thermo Fisher Scientific (USA): A prominent player in the handheld segment with the Niton series and a strong global service network — suited for enterprises prioritizing field analytics and rapid deployment.
- Rigaku (Japan): Positioning centers on benchtop systems for industrial QC and pharma labs; they emphasize ruggedness and integration into manufacturing lines.
- Hitachi High‑Tech (Japan): Bridges handheld and benchtop categories with a focus on QA workflows for regulated industries.
Market concentration metrics in the study indicate modest aggregation among the top vendors — a competitive environment that favours specialization and strong service ecosystems over sheer scale. Recent product moves underscore continuing innovation and renewal: Shimadzu’s portfolio addition in late 2025, Thermo Fisher’s handheld launch in January 2026, and Rigaku’s NEX QC II benchtop series introduced in March 2026 all speak to active R&D cycles and an urgent cadence of product refreshes.
Operational realities and hidden costs
- Consumables and operating expense: Several analyzers require consumables and periodic component replacement (e.g., X-ray tubes, calibration standards, sample cups), which can materially increase operating costs over a device’s lifetime — buyers must model these costs rather than rely solely on headline purchase prices.
- CapEx variability: Instruments can range from modestly priced handhelds to high-end benchtops costing significantly more; this range requires tailored financing and depreciation strategies for enterprises with broad testing needs.
- Service and calibration: Contract scope (on-site vs. depot, preventive maintenance frequency) materially impacts uptime and measurement traceability — a critical factor for regulated industries like pharmaceuticals.
90 / 180 / 360‑day playbook for executive teams
- 90 days: Run a rapid inventory of existing XRF assets, capture warranty and service-contract end dates, and initiate a TCO assessment across candidate vendors using our report’s templates.
- 180 days: Pilot one or two newer handheld and benchtop platforms in representative sites, negotiate multi‑site service agreements with clear performance SLAs, and finalize standard operating procedures that address radiation safety and calibration cadence.
- 360 days: Decide on scale investments vs. incremental refresh based on pilot outcomes, lock in long-term consumable pricing where possible, and consider strategic partnerships or tuck‑in acquisitions to close capability gaps in analytics or aftermarket services.
What we intentionally withhold in this preview (and why)
To preserve the commercial value of the full study and to support proprietary decision-making, this preview does not disclose the detailed splits by region, instrument type, or end application; nor does it include the full vendor scoring matrix, contract templates, or market-by-country tables. These elements are included in the full PW Consulting report because they are the actionable intelligence buyers and investors use to negotiate contracts, size opportunity windows, and prioritize M&A targets.
- Detailed regional and application-level demand profiles (available in the full report).
- Vendor-by-product performance scores and scoring methodology.
- Granular price curves per model and manufacturer.
- Primary interview transcripts and confidential supplier feedback.
Methodology and evidence base
The study combines a bottom-up market-model calibrated with primary interviews across OEMs, channel partners, and end users, together with a top-down validation using historical shipment and revenue series. Key modeling features include scenario analysis for adoption curves, sensitivity to commodity cycles (relevant to mining & metals demand), and regulatory shock scenarios affecting deployment lead times. The base year is 2025, historical coverage spans 2020–2025, and forecasts extend from 2026 through 2032; all monetary figures are presented in USD (Million).
Conclusion — the strategic value of the full report
For decision-makers in 2026, the PW Consulting XRF market study is designed to convert market data into executable choices: when to buy, what to buy, which vendor to partner with, and how to monetize installed bases. The market’s healthy near- and mid-term growth (with a roughly 6.98% CAGR in our forecast) creates both opportunity and urgency for companies seeking to defend or expand market positions. If your 2026 plans include capital allocation to testing instrumentation, a GTM pivot for analytical services, or M&A in adjacent instrumentation and analytics, the full report delivers the calibrated intelligence and operational tools you will need to act with confidence.
To access the complete report, vendor matrices, and downloadable TCO models, please visit the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: X-ray Fluorescence Spectrometer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com