

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Vital Signs Monitor Market to Hit USD 9,735M by 2032 at 7.35% CAGR

Vital Signs Monitor Market — Strategic Imperatives for 2026
Executive snapshot
The Vital Signs Monitor market is returning to the strategic agenda for healthcare OEMs, hospital systems, and private equity investors entering 2026. After steady expansion through the first half of the decade, the market sits on a trajectory that accelerates across the 2026–2032 forecast window at a compound annual growth rate of 7.35%. In absolute terms this research traces the market from roughly USD 4.3 billion in 2020 to about USD 5.9 billion in 2025, with a professional forecast that projects the opportunity approaching the USD 10 billion mark by 2032. Those headline numbers matter — but the real strategic value of this study is in translating macro growth into concrete choices for product roadmaps, commercial models, and M&A prioritization in 2026.
Vital Signs Monitor Market
Why this report matters for 2026 decision-making
-
Timing of regulatory and reimbursement inflection points: New CPT codes and regulatory communications that take effect during or immediately prior to 2026 materially change the commercial calculus for remote and short-duration monitoring products. Market participants that adapt their go-to-market and coding strategies early will capture disproportionate share of newly reimbursed workflows.
Vital Signs Monitor Market -
Consolidation and concentration dynamics: The market exhibits a mid-to-high concentration profile among incumbents, which creates a strategic paradox — large suppliers retain channel control and scale benefits, while mid-sized and niche innovators can outmaneuver on differentiated, connectivity-first propositions. The report decodes how concentration shapes pricing elasticity, procurement tender behavior, and partnership opportunities.
Vital Signs Monitor Market -
Technology and workflow convergence: Advancements in wearable sensors, edge analytics, and EMR-integrated workflows are shifting procurement criteria from standalone device specs to ecosystem fit. Firms that think in terms of integrated monitoring pathways (device + software + clinical decision support) win procurement discussions and create stickier revenue streams.
-
Risk management and supply-chain sensitivity: High-profile safety events and recalls in the prior 24 months are reshaping clinical procurement policies and third-party battery/device sourcing rules. Risk-averse buyers will prioritize suppliers with transparent quality systems and documented post-market surveillance programs.
What this report delivers (practical, transaction-ready content)
PW Consulting’s Vital Signs Monitor Market study is built to be executable. It goes beyond descriptive narrative to provide the tools and outputs executives need in 2026:
-
Robust base-year market sizing and a detailed forecast model covering 2026–2032, including scenario runs tailored to alternative regulatory and reimbursement assumptions.
-
Commercial playbooks for five buyer archetypes (large health systems, ambulatory surgery centers, clinics, home-health operators, and private label/contract manufacturers) that outline procurement triggers, TCO levers, and negotiation playbooks.
-
Product roadmap guidance linking clinical use-cases to prioritized feature investments (connectivity modalities, battery/portability trade-offs, and algorithmic decision support) informed by supplier capability mapping.
-
M&A and partnership heatmaps highlighting high-value targets by capability, with an assessment of integration complexity and a short-list of candidates for bolt-on acquisitions versus strategic alliances.
-
Regulatory and reimbursement tracker with actionable checklists to operationalize new CPT codes and mitigate liability exposure relating to device safety advisories and recalls.
-
Commercial benchmark dashboards that let leadership calibrate pricing, distributor margins, and service model economics against market norms.
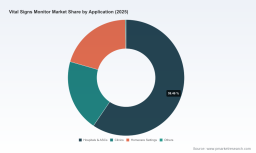
To preserve competitive sensitivity, the public executive summary omits the granular regional and application splits — these are available in the licensed dataset and interactive model.
Competitive landscape — how incumbent strategies are evolving
The competitive field is organized around a few strategic vectors: integrated hospital systems and enterprise EMR connectivity, portable/wearable continuous monitoring, home- and consumer-facing simplicity, and component/sensor specialization. Our analysis focuses on how leading firms are positioning along these vectors and the likely battlegrounds for 2026:
-
GE HealthCare emphasizes multi-parameter, portable systems with clinical-grade clearances and hospital workflows. Their investments prioritize ease of deployment in critical care and perioperative environments.
-
Koninklijke Philips N.V. continues to embed monitoring into broader patient surveillance platforms, with strengths in hospital-wide deployment and clinical decision support integration.
-
Medtronic is executing a strategy that blends hospital-grade modules with wearable, integrated monitoring — targeting chronic-care pathways and seamless transitions between ambulatory and inpatient settings.
-
Masimo targets continuous, multi-parameter platforms with a focus on ambulatory and transport use-cases, competing on sensor fidelity and low-motion performance.
-
Nihon Kohden and other established hospital-focused vendors defend critical care gold-standard features; their advantage is deep clinical validation and longstanding acceptance in high-acuity workflows.
-
Specialists such as Nonin and OMRON occupy the precision sensor and mass-market/homecare end of the spectrum, respectively; their models trade breadth for sensor accuracy, cost efficiency, and channel reach into consumer and home-health segments.
-
Baxter (via Welch Allyn) and SunTech represent combinations of strong field sales coverage and integrated workflow solutions, particularly where EMR and early warning score automation matter.
Market concentration metrics indicate a meaningful advantage for the largest suppliers in negotiating with enterprise buyers, but they also underscore opportunities for focused start-ups and medtechs that deliver differentiated clinical evidence or address gaps in the incumbent technology stack.
Regulatory and reimbursement shocks to plan for in 2026
-
Reimbursement: CMS finalized new CPT codes (effective January 1, 2026) that expand reimbursement eligibility for specific short-duration remote patient monitoring use-cases. This change materially improves the ROI case for devices and software stacks that can demonstrate compliance with the coding criteria.
-
Safety and market access: A 2025 safety communication from the FDA about unauthorized OTC infant monitoring devices raised buyer scrutiny and created new documentation requirements for consumer-adjacent products. Coupled with recent device-specific recalls, buyers now place elevated emphasis on supply-chain governance, post-market surveillance, and use-of-third-party accessory policies.
-
Operational impact: Procurement teams are revising RFPs to include supplier attestations around battery sourcing, software maintenance guarantees, and upgrade pathways. These RFP dynamics favor vendors with certified quality systems and a clear aftermarket service roadmap.
Implications for five archetypal 2026 strategies
-
For OEMs focused on enterprise hospitals: Prioritize EMR integration, validated clinical decision support, and multi-parameter platforms that demonstrate ICU-grade performance. Negotiate bundled service agreements that lock in upgrade and maintenance revenue.
-
For firms targeting ambulatory and ASC workflows: Emphasize portability, rapid onboarding, and seamless data transfer into outpatient EHRs. Leverage the new CPT codes by creating simple submission workflows and reimbursement support services.
-
For home-health and consumer-facing brands: Differentiate through simplified user experience, battery reliability, and clear regulatory positioning; prepare for heightened regulatory scrutiny and the need for consumer safety evidence.
-
For private equity and M&A teams: Focus diligence on companies with defensible clinical evidence and recurring service revenues; be wary of targets exposed to third-party accessory-related liabilities unless remedied in warranties and contract terms.
-
For distributors and value-added resellers: Develop bundled service propositions that combine device supply, connectivity integration, and reimbursement navigation to capture more of the downstream value pool.
How to use this research in 90 days
-
Week 1–4: Run the report’s scenario module against your product roadmap and identify three “must-change” product features or commercial terms required to capture newly reimbursed workflows.
-
Month 2: Use the M&A heatmap and supplier risk assessments to produce a prioritized shortlist for bolt-on acquisitions or strategic partnerships; validate assumptions with targeted reference checks.
-
Month 3: Re-design a pilot program that leverages the CPT code changes and the report’s buyer-playbook to secure a reference customer, then iterate for scale.
Next steps — where to find the granular intelligence
This introduction highlights the strategic contours you must consider as 2026 unfolds: a larger, faster-growing market; reimbursement and regulatory pivots that reward readiness; and a competitive map that favors integrated, evidence-backed propositions. To protect the commercial sensitivity of segmentation tables, supplier-level financials, and our full interactive forecast, we provide the detailed datasets and modelling workbook through PW Consulting’s licensed report package. The licensed deliverable includes downloadable models, configurable scenario tools, and the complete list of granular regional and application splits that informed the analysis summarized here.
Contact PW Consulting for a preview workshop and a tailored briefing. In the next 60 minutes we can align the findings to your strategic priorities and outline a 90-day execution plan to capture the most immediate value from the 2026 market inflection.
For detailed analysis of this topic, please visit the official page: Vital Signs Monitor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com