

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Facial Mask Market Growing at a Robust 7.6% CAGR Through 2032
By pmarketresearch, 2026-07-13
Facial Mask Market 2026: Strategic Imperatives from PW Consulting’s Industry Intelligence
As companies set strategy for 2026, the facial mask market presents a blend of resilient consumer demand, concentrated supplier structures, rapid product innovation, and an evolving regulatory milieu. PW Consulting’s latest market research (base year 2025, historical coverage 2020–2025, forecast 2026–2032) synthesizes these forces into an actionable playbook for executives, investors, and innovation leads. The study projects a multi-year expansion at a compound annual growth rate (CAGR) of 7.6%, with a clear trajectory from early-pandemic demand stabilization into differentiated, premium-led growth. Below I summarize the strategic value of this intelligence, highlight the practical components of the report, and outline how forward-looking organizations should use these insights to shape competitive advantage in 2026 and beyond.
Facial Mask Market
Market snapshot: stability, scale, and the growth path
After a period of heightened volatility, the facial mask market has rebalanced into a growth phase underpinned by recurring at-home consumption and selective professional demand. Our analysis tracks market size across 2020–2025 and extends through 2032, demonstrating a steady climb that is projected to reach materially higher levels by the end of the forecast window. This steady CAGR of 7.6% reflects the combined influence of product premiumization (advanced substrates such as bio‑cellulose and hydrogels), expanded daily-use routines, and incremental adoption in new markets and channels.
Facial Mask Market
Two structural observations matter for 2026 planning: first, the market exhibits above-average concentration among leading manufacturers and brand owners—making strategic partnerships and supply security high priorities. Second, premium substrate innovation and ingredient storytelling are the primary levers driving margin expansion and willingness-to-pay among target consumers.
Facial Mask Market
Why this research matters for 2026 decision-making
- Prioritize supply resilience: With a concentrated supply base and specific raw-material dependencies (notably bio‑cellulose and hydrogel substrates), procurement strategies must shift from price-centric to resilience-centric. The report quantifies supplier concentration and models supply disruption scenarios to support contract and inventory decisions.
- Align R&D and portfolio choices with premiumization: Consumer willingness to pay for efficacy and sustainability-backed claims continues to rise. Our report maps ingredient-technology pairings to commercial outcomes to help R&D prioritize high-impact formulations and substrate investments.
- Calibrate channel and pricing tactics: Evolving channel mixes—direct-to-consumer, retail, and professional—require bespoke pricing and promotional models. The study includes scenario-based revenue and margin projections under plausible channel-shift assumptions relevant for 2026 planning cycles.
- De-risk regulatory transitions: Recent regulatory updates and guidance across jurisdictions introduce compliance and labeling considerations that affect time-to-market and cost structures. We provide a regulatory playbook keyed to common market entry strategies.
What the PW Consulting report contains (practical elements)
- Market sizing and long‑range financial forecasts (base year 2025; historical 2020–2025; forecast period 2026–2032) with sensitivity analyses and scenario pathways tied to macro and consumer-behavior variables.
- Demand drivers and segmentation frameworks that explain growth vectors without exposing competitive-sensitive granularity—enabling strategic planning without compromising client confidentiality.
- Supply-chain and sourcing diagnostics, including raw-material dependency mapping, supplier risk heatmaps, and cost-to-serve models for primary substrates and packaging formats.
- Regulatory and standards tracker focused on near-term changes likely to affect label claims, testing burden, and market access in core geographies.
- Commercial playbooks for market entry and scale-up, covering B2B contract manufacturing, private label strategies, and direct-to-consumer brand expansion.
- Financial benchmarks and valuation comparables for M&A and JV decision-making, plus an M&A checklist that prioritizes targets delivering capacity, IP, or channel access.
- Innovation pipeline assessment with technology roadmaps—prioritizing bio‑cellulose, hydrogel, and sustainable packaging options that show strongest ROI across adoption scenarios.
Competitive landscape: what to watch among leading firms
The industry is shaped by a mix of large multinational brand owners and specialized contract manufacturers/ODM/CDMOs. Key players combine scale, formulation expertise, and channel reach—each with distinct strategic positioning:
- COSMAX (Seongnam, South Korea) — Noted for ODM and contract manufacturing expertise, particularly in hydrogel and bio‑cellulose mask formats. Their deep R&D in K‑beauty technologies and private‑label manufacturing makes them a go‑to partner for brands seeking rapid productization.
- Kolmar Korea (Seoul, South Korea) — A global ODM with strengths in scalable sheet‑mask manufacturing and recent product innovations in sustainable packaging. Their move toward recyclable pouch solutions signals how upstream packaging innovations can influence downstream brand claims.
- Nox Bellcow (Zhongshan, China) — A high‑volume OEM/ODM supplier with automated lines and global export footprint; attractive for cost‑efficient scale and rapid order fulfillment across emerging markets.
- TCI Bio (Taipei, Taiwan) — Specialized CDMO and private‑label producer with significant biocellulose capacity; a strategic partner for premium brands seeking organic ingredient options and bespoke formulation services.
- L’Oréal, Estée Lauder, Johnson & Johnson, Shiseido — These multinational brand owners leverage R&D, marketing scale, and distribution to shape consumer preference and set pricing reference points. Their portfolio expansions and ingredient investments are key signals for market direction.
Our report includes comparative profiles that assess technological capabilities, manufacturing footprint, and partnership openness—scored against strategic criteria relevant to sourcing, co‑development, and M&A.
Regulatory and industry dynamics shaping 2026 choices
- Regulation matters: Recent updates in harmonized standards for medical face masks in the EU and ongoing guidance such as the FDA’s Cosmetic Product Safety and Labeling Guidance increase compliance complexity. These developments impact product classification, testing obligations, and permissible claims—factors that materially affect time-to-market and total cost of commercialization.
- National oversight: Export-focused manufacturers continue to navigate varying national safety assessment regimes; for example, oversight by South Korea’s Ministry of Food and Drug Safety remains influential for suppliers serving multiple export markets.
- Raw‑material trends: Bio‑cellulose and hydrogel substrates remain the primary raw materials for premium offerings, with a rising consumer preference for organic or natural ingredient narratives. Our material cost and availability scenarios help procurement and R&D teams plan multi-year sourcing strategies.
- Consumer behavior: Sheet mask formats continue to dominate purchase behavior due to convenience and targeted benefits (hydration, brightening, anti‑aging). This entrenched preference shapes SKU rationalization and innovation focus areas for 2026.
Recent developments that will influence near‑term tactics
- Clinical innovation and evidence: Recent clinical programs examining LED mask adjuncts highlight growing interest in device-plus-mask hybrid solutions—an area brands may exploit for differentiation if they can operationalize claims within regulatory constraints.
- Sustainability in packaging: Product launches and R&D efforts to deploy recyclable pouches are advancing; early adopters can lock in sustainability credentials while managing cost trade-offs.
- Portfolio reshaping by major brands: Ongoing portfolio expansions by large multinationals reinforce the need for nimble positioning among niche players and private label suppliers.
- Regulatory standard updates: Updated EU harmonized standards for medical masks signal the need for compliance roadmaps for any supplier or brand pursuing cross-border clinical or medical positioning.
How senior leaders should act in 2026
- Adopt a dual-track sourcing strategy: secure capacity with established CDMOs/ODMs while qualifying secondary suppliers to mitigate single-source risk.
- Invest in evidence generation selectively: prioritize clinical or consumer-efficacy studies where claims materially support price premiums or channel expansion.
- Embed regulatory forecasting into product roadmaps: anticipate labeling and testing shifts to avoid costly reformulation or repackaging downstream.
- Use M&A selectively to acquire capacity or proprietary substrates rather than volume alone—our valuation matrices identify where acquisition creates strategic optionality.
- Differentiate with sustainability that matters: focus on packaging and ingredient changes that are verifiable and resonate with core consumer segments.
Next steps
PW Consulting’s full report provides the detailed forecasting models, supplier risk matrices, go‑to‑market playbooks, and competitive benchmarking that support 2026 strategic planning. This article is a strategic preview designed to establish the most important decision levers; the complete study contains the granular inputs, scenario outputs, and implementation templates your leadership team will need to execute. For an executive briefing, customized scenario modeling, or to access the full dataset and segmentation tables, contact PW Consulting to schedule a consultative walkthrough and obtain the full intelligence package.
For detailed analysis of this topic, please visit the official page: Facial Mask Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Wheel Bearing Market Set for 6.5% CAGR (2026-2032)
By pmarketresearch, 2026-07-13
Automotive Wheel Bearing Market — A Strategic Preview for 2026 Decision-Makers
Executive summary
As OEMs, tier‑1 suppliers and aftermarket specialists plan their 2026 playbooks, understanding the trajectory of the automotive wheel bearing market is mission‑critical. PW Consulting’s latest study (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes market sizing, competitive positioning, technology inflections and regulatory drivers into an actionable intelligence set. The market is growing at a steady compound annual growth rate (CAGR) of 6.5% across the 2026–2032 forecast window, building on a 2025 baseline and reaching materially larger scale by 2032. Importantly, the market exhibits moderate concentration — the top three global players account for a clear majority of industry revenues, and the top five extend that dominance further — a structural reality that shapes pricing power, technology diffusion and M&A dynamics.
Automotive Wheel Bearing Market
Why this analysis matters for 2026 strategy
-
Product roadmap calibration: wheel bearing design is no longer a commodity decision. Integrated sensors, pre‑lubricated hub units, advanced sealing and drag‑torque optimization are differentiators for both OEM spec and aftermarket preference. Firms that align R&D and manufacturing investments to these vectors will secure specification slots and aftermarket mindshare.
Automotive Wheel Bearing Market -
Vehicle powertrain shifts: electrification is changing duty cycles and thermal characteristics of wheel bearings. While EV penetration impacts absolute unit and revenue mixes differently across segments, the technical requirements for sealing, lubrication and sensor integration are shifting — creating both risk and opportunity for incumbents and new entrants.
Automotive Wheel Bearing Market -
Supply chain resilience and raw materials: fluctuations in steel, specialty alloys and grease base stocks, combined with tighter performance and environmental standards, necessitate upstream engagement. Buyers and suppliers must revisit sourcing strategies and qualification protocols in 2026 to avoid margin erosion and disruption.
-
Aftermarket and service models: extended service intervals and predictive‑maintenance adoption change replacement patterns — an opportunity for suppliers who can bundle hardware with diagnostics, repacking services or value‑added kits.
Market dynamics — forces you cannot ignore
-
Standards and testing: ASTM D1263 remains a reference for grease leakage tendencies, a critical performance parameter for high‑speed, high‑temperature wheel bearing applications. Expect OEM and aftermarket specifiers to increasingly reference standardized test regimes when qualifying lubricants and sealed units.
-
Predictive reliability: new methodologies — notably those articulated in recent SAE research — enable life and damage forecasting using real‑time load analytics. Suppliers embedding sensing and data pipelines into hub units can move from component vendors to service partners with recurring revenue models.
-
Seal and torque engineering: academic and industry research is refining our understanding of drag torque behavior and interference optimization in assemblies. Improvements here translate directly into lower energy losses, improved NVH and longer service life — attributes that feed back into OEM vehicle efficiency targets.
-
Maintenance innovation: documented developments in grease repacking devices and maintenance tools point to a renaissance in aftermarket serviceability. Companies that support professional service channels with certified repacking and refurbishment solutions will capture incremental aftermarket share.
Competitive landscape — what the leaders are doing
The wheel bearing market is shaped by several global engineering leaders whose strategic choices set the agenda for the ecosystem. Key firms include SKF Group, Schaeffler AG (FAG), NSK Ltd., NTN Corporation, JTEKT Corporation and The Timken Company. These incumbents combine deep mechanical expertise with system‑level offerings — hub assemblies, pre‑lubricated units, integrated sensors and aftermarket kits — and are actively positioning to win both OEM and replacement business.
-
SKF Group (Gothenburg, Sweden; https://www.skf.com) leverages a strong history in hub bearing units and sensor integration. Its emphasis on pre‑lubricated units and full kits is designed to reduce failure modes while simplifying installation for OEMs and workshops.
-
Schaeffler AG (Herzogenaurach, Germany; https://www.schaeffler.com) continues to push complete hub solutions under established brand umbrellas, focusing on repairability and aftermarket kits that match OEM specifications — a lucrative play given warranty and service economics.
-
NSK Ltd. (Tokyo, Japan; https://www.nsk.com) has invested in advanced sealing and mounting technologies, addressing the thermal and geometric challenges presented by higher torque, lower‑noise applications common in modern vehicles.
-
NTN Corporation (Osaka, Japan; https://www.ntnglobal.com) develops integrated hub assemblies for passenger and light commercial vehicles with an eye to manufacturability and ease of installation, appealing to cost‑conscious OEM programs.
-
JTEKT Corporation (Osaka, Japan; https://www.jtekt.co.jp) emphasizes reliability through integrated sensor covers and robust sealing, targeting vehicle programs where long life and low maintenance are priority selling points.
-
The Timken Company (North Canton, Ohio, USA; https://www.timken.com) focuses on engineered rolling element solutions and aftermarket availability, with a reputation for performance in demanding applications.
These players collectively account for a significant share of the market (the three largest capture a majority, and the top five an even larger portion), producing a landscape where strategic collaboration, selective vertical integration and targeted acquisitions are used to defend share or enter adjacencies.
What the PW Consulting report delivers (practical, actionable contents)
Designed for strategy teams, business development leaders and M&A practitioners, the report is structured to enable immediate decision-making in 2026:
- Market sizing and forecast model (base year 2025; historical 2020–2025; forecast 2026–2032) — including sensitivity scenarios around EV adoption and servicing paradigms.
- Competitive benchmarking — capability maps for leading suppliers, product portfolios and go‑to‑market models.
- Technology heatmap — sealing, lubrication, sensor integration, and NVH/drag torque advancements, with implications for BOM and testing protocols.
- Regulatory and standards impact assessment — translating ASTM, SAE and specialist tribology findings into supplier and OEM actions.
- Supply chain risk matrix — raw material exposure, qualification lead times and contingency strategies for critical components.
- Aftermarket and service strategies — refurbishment, repacking and diagnostic service opportunities with revenue models and partner options.
- M&A and partnership playbook — target profiles, valuation approaches and integration considerations tailored to 2026 market realities.
How leading companies should act in 2026 — tactical recommendations
-
Prioritize sensorized hub platforms where lifecycle analytics create recurring revenue. The convergence of SAE‑level predictive methodologies and practical sensing hardware means early adopters can transition from one‑time component sales to subscription or service contracts.
-
Invest in validated grease formulations and sealing tech that meet standardized leakage and drag‑torque criteria. Reference to ASTM and tribology research will be a procurement differentiator for programs targeting efficiency and durability.
-
Re‑examine supply contracts for specialty alloys and grease precursors. Given the concentration of market power and potential supply disruptions, secure multi‑tier sourcing and pursue design changes that reduce dependence on high‑volatility inputs where feasible.
-
Build aftermarket ecosystems around certified repacking, refurbishment and diagnostics. This not only extends lifetime value but also preserves brand control in a market that increasingly values professional servicing.
-
Use M&A selectively to acquire sensing capabilities, advanced sealing IP or regional aftermarket distribution. The industry’s concentration profile favors bolt‑on consolidation in targeted geographies or technology niches.
Limitations of this preview and where to find the full intelligence
This article is a strategic preview designed to surface the most salient trends and recommended actions for 2026. To preserve proprietary value and to drive decisive client engagements, detailed segment tables (regional, type and application splits), company revenue breakdowns and the full-year-by-year forecast model are intentionally omitted from this summary. The full dataset — including granular segmentation, downloadable models and company scorecards — is available through PW Consulting’s full report and client portal.
Next steps
For executives preparing 2026 budgets, product roadmaps or M&A pipelines, PW Consulting can provide bespoke briefings, a workshop to stress‑test strategy against our forecast scenarios, or a carve‑out diligence pack for specific acquisition targets. Contact our automotive practice to schedule an executive session and obtain the complete data package that informs procurement, product and corporate development decisions in this increasingly strategic component market.
For detailed analysis of this topic, please visit the official page: Automotive Wheel Bearing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electric Wheelchair Market to Reach USD 8.05B in 2025; 9.5% CAGR to 2032
By pmarketresearch, 2026-07-13
Electric Wheelchair Market 2026: Strategic Preview for Executive Decision-Making
As healthcare delivery, aging demographics, and assistive-technology innovation converge, the electric wheelchair market has entered a sustained growth phase that will reshape supplier strategies and buyer expectations through the end of the decade. This executive preview—prepared by PW Consulting’s industry practice—summarizes the strategic implications that our full Electric Wheelchair Market study provides for 2026 decision cycles. It highlights macro scale, market structure, competitive dynamics, regulatory inflection points, and the practical tools buyers and suppliers will need to convert disruption into durable advantage.
Electric Wheelchair Market
Macro snapshot: a market moving from niche to mainstream
By our base year (2025) the global electric wheelchair market reached an estimated USD 8.05 Billion, roughly doubling from the start of the decade. We forecast the market to grow at a compound annual growth rate (CAGR) of 9.5% across the 2026–2032 period, culminating in a market worth approximately USD 15.23 Billion by 2032. That trajectory reflects a mix of demographic tailwinds, clinical adoption of advanced mobility solutions, and product innovation—especially around battery technology, compact drives, and modular control systems.
Electric Wheelchair Market
For 2026, the implication is clear: buyers will face a bifurcated market in which premium, tech-enabled solutions expand rapidly while cost-focused providers push down the entry price for basic powered mobility. That divergence creates both margin pressure and opportunity for companies able to define and own adjacent value propositions (data services, seating systems, and retrofit electrification modules).
Electric Wheelchair Market
Why this study matters to 2026 strategic choices
- Timing of investment: The growth inflection through 2026 rewards selective capex in manufacturing flexibility, battery testing, and regulatory readiness. Firms that delay certification or supply-chain resiliency upgrades will experience longer sales cycles and higher warranty risk.
- Portfolio prioritization: With performance and control interfaces becoming decisive purchase drivers, 2026 is the year to decide which product families to scale, which to sunset, and where to deploy R&D dollars to capture premium unit economics.
- Route-to-market optimization: Reimbursement updates and evolving payer criteria in major markets mean that channel strategies (retail dealers, hospitals, direct-to-consumer) must be rebalanced to preserve revenue growth.
- M&A and partnership windows: Given the moderate market concentration (CR3 and CR5 metrics indicate a market with significant independent players alongside global leaders), 2026 will be tactically favorable for tuck-ins that add battery, telematics, or seating expertise without changing core distribution footprints.
Competitive landscape — assessing capability, not just brand
The market comprises a blend of legacy specialists, vertically integrated manufacturers, and high-volume OEMs. Our study maps company capabilities across product engineering, supply chain scale, clinical-grade rehabilitation expertise, and aftermarket services. Notable players with differentiated strengths include well-known rehabilitation specialists and mobility giants, as well as an expanding set of Asia-based manufacturers and component suppliers that are redefining unit economics.
- Rehabilitation specialists: Firms with deep clinical credentials continue to command pricing authority around complex-rehab power chairs by owning therapeutic seating systems and control interfaces.
- Consumer mobility leaders: Companies focused on lifestyle and consumer ease-of-use maintain strong retail channels and fast product refresh cadences.
- Component and OEM suppliers: Specialist suppliers of electric drive units, lithium-battery packs, and carbon-fiber frames are increasingly strategic partners—especially for manufacturers seeking to speed time-to-market.
Our competitive profiles (included in the full report) evaluate each firm not as a single line item but as a composite of R&D posture, regulatory track record, distribution footprint, and service infrastructure—plus their exposure to emerging risk vectors such as firmware liabilities and battery transport restrictions.
Regulatory and operational dynamics shaping 2026
The sector is being reshaped by a cluster of regulatory actions and industry responses that must be factored into any 2026 plan:
- Device classification and market entry: Power wheelchairs remain subject to medical device regulations in major markets, which raises the bar for documentation, clinical evidence, and post-market surveillance. Certification timelines should be part of go/no-go investment modeling.
- Safety incidents and firmware liability: High-profile Class I recalls related to joystick firmware and control electronics have underscored the reputational and financial costs of software regressions. Firms must treat embedded software as a first-order regulatory risk—investing in firmware validation, fault-tolerant architectures, and recall contingency playbooks.
- Battery transport and airline policies: New airline and industry guidance (including updated lithium-battery handling and watt-hour limits) have immediate operational impact on cross-border distribution, rental fleets, and patient travel services. Compliance will increasingly be a logistics and customer-support competency, not just an engineering one.
- Reimbursement shifts: Recent changes to coding and reimbursement for advanced control interfaces and seating accessories in major markets alter purchasing calculus for institutional buyers and create monetizable upgrade paths for manufacturers.
Product, channel, and service plays to prioritize in 2026
Based on the modeled growth scenarios and the regulatory landscape, PW Consulting recommends that companies evaluate a three-axis strategy:
- Product modularity: Design platforms that allow shared drives, batteries, and control modules across multiple seat and frame variants. Modularity reduces SKU proliferation and accelerates certified upgrades.
- Compliance-as-a-competitive-advantage: Build demonstrable, auditable processes for firmware lifecycle management and battery safety to reduce recall risk and drive trust with institutional purchasers.
- Aftermarket and services monetization: Create subscription-style offerings for maintenance, battery replacement, telematics, and extended warranties to improve lifetime value—particularly as device lifecycles lengthen.
M&A and partnership lenses for 2026
Given the market’s moderate concentration and the increasing importance of component specialization, strategic transactions should be judged by three criteria:
- Technology complementarity: Does the target add battery, control, or seating IP that reduces time-to-market for premium offerings?
- Distribution leverage: Will the asset expand access to high-growth channels (e.g., rehabilitation clinics, veteran services, or international distributors) without onerous channel conflict?
- Regulatory readiness: Does the target have clean compliance documentation and an auditable post-market surveillance system?
We map hypothetical synergies and integration risks in our full report, providing acquisition scorecards and pro forma scenarios tailored to strategic buyers, private equity investors, and OEMs seeking vertical integration.
What is included in the full PW Consulting Electric Wheelchair Market study
Our complete report is designed as an operational playbook for 2026. It includes:
- Annualized market sizing (historical series and forecast through 2032) with sensitivity scenarios tied to key variables (battery regulation, reimbursement policy, and supply-chain normalization).
- Market-structure analysis that explains where value accrues (products, services, components) without disclosing granular segment tables in this preview.
- Detailed company profiles and capability maps, benchmarking R&D investment, product portfolios, and service footprints for the principal market participants.
- Regulatory and safety dossier summarizing recalls, policy changes, and certification routes plus recommended compliance investments and timelines.
- Commercial playbooks, including pricing frameworks, channel optimization strategies, and go-to-market templates for hospital, homecare, and senior-care channels.
- Transaction playbooks for M&A and strategic partnerships with modelled synergies, valuation ranges, and integration roadmaps.
- Practical spreadsheet models: forecast scenarios, build vs. buy matrices, and ROI calculators for fleet electrification, new-product introductions, and aftermarket services.
How to use our insights to inform 2026 decisions
Executives and investors should use the study to accelerate three discrete decisions this year:
- Near-term capital allocation: Prioritize investments that reduce regulatory and firmware risk, and scale modular platform pilots that can be certified fast.
- Portfolio pruning vs. expansion: Use the report’s ROI models to identify non-core SKUs for divestiture and determine which premium features justify a higher lifetime price point under new reimbursement rules.
- Channel and service pilots: Launch limited-scope aftermarket offerings (battery subscription, remote diagnostics) in regions with favorable reimbursement to validate recurring revenue models.
Closing perspective: 2026 as a strategic hinge year
The electric wheelchair market is no longer a small adjacent category—it is transitioning into a mature, multi-billion-dollar market with clear winners and losers emerging by their choices in product architecture, regulatory discipline, and service monetization. With a projected CAGR of roughly 9.5% and market size expansion from the mid-decade baseline toward the 2032 forecast, companies that treat 2026 as a hinge year—making disciplined bets on modularity, compliance, and service—will capture disproportionate share of the market value pool.
This preview intentionally omits granular segment tables and region-application splits to focus on the strategic narrative and to protect the actionable analytics contained in the full study. For the complete dataset, company scorecards, scenario models, and the tactical playbooks required to implement the recommendations summarized here, please consult the PW Consulting Electric Wheelchair Market report hosted on our research portal.
For detailed analysis of this topic, please visit the official page: Electric Wheelchair Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
XOS Market to Reach USD 97.5 Million by 2032 at 6.5% CAGR — PW Consulting
By pmarketresearch, 2026-07-13
Xylooligosaccharides (XOS) Market — Strategic Imperatives for 2026
As PW Consulting’s lead industry analyst, I present a concise, decision‑focused preview of our comprehensive Xylooligosaccharides (XOS) Market study. This briefing is written to inform C‑suite and strategy teams as they define 2026 priorities: where to invest, which capabilities to accelerate, and how to approach regulatory and supply risks. The language below demonstrates the analytical depth you can expect from the full study while deliberately preserving core segmented datasets — a purposeful “trailer” designed to prompt direct access to the full intelligence package for transaction‑grade planning.
Xylooligosaccharides (XOS) Market
Market snapshot: measurable momentum and structural context
XOS has moved from a niche ingredient to a commercially meaningful category over the last half‑decade. Our model shows the global market expanded from approximately USD 50 million in 2020 to about USD 63 million in 2025, and is forecast to reach roughly USD 66.7 million in 2026 on the way to about USD 97.5 million by 2032 — driven by an average compound annual growth rate (CAGR) of 6.5% for the 2026–2032 forecast window. These headline figures reflect steady adoption across food & beverage, animal nutrition and nutraceutical channels, and they quantify an investible opportunity for vertically integrated producers, ingredient formulators, and branded product owners.
Xylooligosaccharides (XOS) Market
Market structure matters: the XOS industry exhibits moderate concentration, with the top three suppliers accounting for more than half of reported commercial supply and the top five controlling roughly two‑thirds of capacity. This concentration creates a dual dynamic: scale advantages for incumbents (cost, distribution, quality assurance) and meaningful windows for differentiated entrants that can offer unmatched purity, formulation support or regulatory readiness.
Xylooligosaccharides (XOS) Market
Why this research matters for 2026 decisions
- Investment prioritization. The 6.5% medium‑term CAGR and the proven 2020–2025 growth trajectory provide a defensible baseline for capital allocation. Investors should calibrate expansion capex and brownfield greenfield decisions to realistic volume ramp profiles we detail in the full report.
- Regulatory strategy as a competitive moat. Regulatory status is a binary gate in several markets. The United States currently benefits from GRAS acceptance for many XOS uses, while Canada has issued non‑novel determinations for certain feedstocks. In contrast, the European Union treats XOS as a novel food under Regulation (EU) 2015/2283, creating a pre‑market authorization requirement that materially affects time‑to‑market and go‑to‑market sequencing. Our study provides a practical roadmap to convert regulatory workstreams into commercial advantage.
- Supply chain and raw material playbook. XOS manufacturers commonly rely on corn cobs — a low‑cost, widely available agricultural by‑product containing high xylan content — as the primary upstream feedstock. Understanding feedstock sourcing economics, seasonal variability, and logistics is essential; the report includes a sensitivity model linking feedstock price swings to producer margins and finished‑goods pricing.
- Commercial segmentation and channel focus. Adoption dynamics differ markedly by end‑use: beverage formulators demand liquid grades and stringent solubility/clarity metrics, nutraceutical customers prioritize high‑purity powders and certified analytics, while animal nutrition buyers emphasize cost/performance and supply reliability. Our go‑to‑market playbook translates those differences into prioritized product roadmaps and channel KPIs.
Competitive landscape — what to watch in 2026
The competitive picture is dominated by a cluster of established Chinese producers alongside a few legacy developers with deep IP and long commercial track records. Leading Chinese manufacturers have scaled aggressively: several report multi‑thousand‑ton production footprints geared to dietary supplement and functional food applications, while others have recently commissioned liquid‑grade lines to address beverage demand. Japan’s Suntory remains noteworthy as the original commercial pioneer, retaining technical know‑how in enzymatic production routes and longstanding customer relationships.
- Scale and cost leadership. Major Chinese producers benefit from integrated feedstock sourcing, low manufacturing cost bases and proximity to large domestic demand pools — factors that underpin competitive pricing and rapid capacity deployment.
- Product differentiation. Market winners will be those that segment on quality and formulation support: high‑purity powders for nutraceutical brands, spray‑dried formulations for consumer goods, and beverage‑grade liquids tailored for ready‑to‑drink applications. Recent capital projects have targeted these niches, and we expect further tiering of supplier value propositions in 2026.
- Recent market development. Capacity shifts continue to occur: for example, a leading powder producer expanded liquid‑grade capacity in early 2026 to serve beverage formulators — a signal that producers are chasing higher‑value, application‑specific demand as the category matures.
Operational considerations for buyers and producers
- Feedstock management. Corn cobs are abundant and cost‑effective due to high xylan content, but buyers should insist on contracted volumes, quality specs and traceability clauses to avoid seasonal variability and quality drift. Our report contains supplier scorecards and contracting templates for feedstock offtake.
- Process selection and quality assurance. Enzymatic routes and purification stages determine product purity, degree of polymerization, and impurity profiles — attributes that directly affect allowable applications and shelf stability. We benchmark process technologies versus commercial outcomes in a dedicated technical appendix.
- Regulatory and claims strategy. For jurisdictions where XOS is novel, producers must budget for pre‑market dossiers and post‑authorization surveillance. Where GRAS status or non‑novel determinations exist, companies should still maintain strong documentation to support claims and to expedite customer adoption. The full study includes a regulatory matrix and a templated authorization timeline for each target geography.
- Quality & sustainability narratives. Buyers and brands will increasingly demand robust supply chain transparency and low‑carbon claims. Traceability from cob to capsule, and demonstrable yield improvements that reduce waste, are becoming commercial differentiators.
Go‑to‑market playbook for 2026
- Phase entry by regulatory clarity. Prioritize markets with clear and permissive regulatory regimes to establish volume and reference customers quickly; simultaneously invest in EU authorization for strategic longer‑term presence.
- Tailor product architecture. Maintain a triage of product grades: high‑purity powder for nutraceuticals, beverage‑grade liquids for formulators, and cost‑optimized grades for animal nutrition. Invest in analytics and formulation support to accelerate OEM adoption.
- Secure feedstock and manufacturing capacity. Negotiate multi‑year offtake agreements with agricultural cooperatives, and consider contract manufacturing partnerships in regions that provide logistics or regulatory advantages.
- Use M&A and JV selectively. Where market access or technical IP is the bottleneck, targeted partnerships (minority stakes, exclusives, tolling contracts) can unlock rapid scale without carrying full greenfield risk.
- Commercial risk management. Build flexible pricing clauses tied to feedstock indices, and structure supply agreements with clear quality dispute resolution pathways.
What the full PW Consulting report delivers (high‑value, operational outputs)
- Detailed demand model and scenario analysis (2020–2032) with sensitivity to feedstock and macroeconomic shocks.
- Regulatory matrix and stepwise authorization roadmaps for key markets, including estimated timelines and dossier requirements.
- Supplier scorecards and a prioritized shortlist for offtake or strategic partnership candidates, including technical capabilities and estimated commercial capacities.
- Product grade taxonomy with application match‑matrix and pricing bands, plus formulation playbooks for beverage, supplement and feed customers.
- Investment case templates, capex/opex models and payback scenarios for brownfield expansions, greenfield sites and tolling arrangements.
- M&A and partnership playbook: red flags, valuation multipliers and integration checklists specific to XOS producers and ingredient formulators.
Our preview above uses headline market sizing and structural signals to establish the commercial case for action in 2026. For teams structuring investment memoranda, negotiating supply agreements, or defining entry strategies, the full PW Consulting XOS Market report provides the granular segmentation, regional and application breakdowns, and unit‑level economics required to execute with conviction. If your 2026 strategy depends on rigorous, transaction‑grade intelligence — including the fine‑grained segmentation we intentionally withheld here — contact PW Consulting or visit our XOS Market page to access the complete dataset, modeling files and advisory engagement options.
For detailed analysis of this topic, please visit the official page: Xylooligosaccharides (XOS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tower Crane Market to Reach USD 344.8M by 2032, Growing at 6.1% CAGR — PW Consulting
By pmarketresearch, 2026-07-13
Tower Crane Market: A Strategic Primer for 2026 Decision‑Making
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise yet actionable orientation to our full Tower Crane Market research. This piece is written for senior executives, portfolio managers, procurement leads, and product strategists who must convert market intelligence into decisive moves in 2026. It surfaces the evidence-based trends, competitive tensions, regulatory inflections, and executional playbooks that will determine winner and laggard behavior — while reserving the full granular modeling and proprietary splits for the complete report.
Tower Crane Market
Executive snapshot — what the numbers mean for strategy
The tower crane market has regained momentum after a period of cyclical pressure. Our base-year sizing places the market at USD 215.0 Million in 2025, up from approximately USD 163 Million in 2020, reflecting recovery and selective structural demand. Looking forward, the market is forecast to expand at a compound annual growth rate (CAGR) of 6.1% across the 2026–2032 forecast window, reaching roughly USD 345 Million by 2032. Those topline dynamics underpin three strategic implications for 2026 decision-makers:
Tower Crane Market
- Demand visibility is improving, not exploding. Growth is steady and investable — enabling disciplined capital allocation rather than speculative capacity builds.
- Competitive positioning will be decided at the product and aftermarket level. With a concentrated vendor set, market share moves are incremental but high-impact when paired with superior service models.
- Macro and regulatory volatility (materials, site rules, approvals) create asymmetric risks that can be hedged through procurement timing, dealer networks, and retrofit/upgrade offerings.
Why 2026 is an inflection point
Two forces make 2026 different from the prior half‑decade. First, product innovation has shifted from marginal improvements to system-level gains: luffing-jib architectures and flat-top modular platforms now come with embedded assistance systems and faster erection cycles, reducing downtime and total cost of ownership. Second, the regulatory and certification environment is tightening in key jurisdictions, raising the bar for market access and aftersales service capabilities.
Tower Crane Market
These forces alter the economics of ownership and the calculus for fleet operators, rental houses, and contractors. Procurement decisions in 2026 therefore require greater attention to lifecycle economics, certification timelines, and dealer coverage — not just unit sticker price.
Market dynamics & operational risks
- Raw material sensitivity: Steel cost remains a primary input risk. Recent spot readings have shown elevated nominal levels, which compress margins for suppliers with fixed-price backlogs and raise replacement cost for owners planning fleet expansion. Understanding the linkage between steel price cycles and OEM quoting behavior is now fundamental to procurement timing.
- Regulatory shifting: New permitting regimes and type‑approval programs are reshaping route‑to‑market friction. For example, some jurisdictions implemented permit requirements for assembly and reconfiguration activities in 2026, while others accelerated type‑approval certifications for multiple models. These trends favor suppliers with local certification footprints and agile compliance functions.
- Aftermarket & uptime economics: The competitive margin is increasingly in service bundles — remote diagnostics, predictive maintenance, fast spare availability, and certified erection teams deliver measurable reductions in out‑of‑service time, a point reinforced by recent product launches that emphasize reduced teardown/erection cycles.
Technology and product trends to prioritize
- Intelligent assistance systems: Crane models featuring integrated sensors and operator assistance are moving from premium options to expected functionality. These systems shorten learning curves for crews and materially reduce safety incidents — a selling point for large contractors.
- Modularity & self‑erection: Modular flat‑top platforms and self‑erecting variants continue to win where urban infill and tight site logistics dominate. For manufacturers, modularity reduces variant costs and enables faster global deployment.
- High‑capacity luffing jib advances: Recent generations of luffing jibs deliver higher headroom for inner‑city high‑rise projects and faster project timelines; this is changing spec decisions on complex sites.
Competitive landscape — who matters and why
The tower crane market exhibits meaningful concentration among established OEMs. The competitive pattern is less about low‑cost disruption and more about proven capability, certification reach, dealer network density, and aftermarket execution. Key players to watch include legacy European leaders, North American specialists, and Chinese OEMs that have broadened their global product lines. Strategic observations:
- Liebherr Group (Germany): Their HC‑L luffing and flat‑top series emphasize intelligent assistance and rapid erection. Liebherr’s project deliveries and regional dealer engagements demonstrate a playbook centered on premium engineering paired with close distributor collaboration.
- The Manitowoc Company, Inc. / Potain (USA): Potain’s modular and self‑erecting portfolio targets operational efficiency and site versatility — important where rental fleets need fast turnarounds and predictable lifecycle costs.
- Terex Corporation (USA): Terex’s CTL luffing jib range combines advanced controls and safety systems — positioning the brand for complex site specifications and certified installation contracts.
- Zoomlion & XCMG (China): Both groups have amplified their export‑grade flat‑top and heavy‑duty models, supported by increasingly global certification footprints. Their strategy blends competitive pricing with growing product sophistication.
- SANY Group (China): SANY’s modular SFT/STT lines focus on safety and regional certification, reflecting a twin strategy of rapid market penetration backed by compliance wins.
- Specialist OEMs (Raimondi, Wolffkran, Comansa, Favelle Favco, JASO): These players compete on niche strengths — compact footprints, high lifting efficiency, or regional serviceability — and are the typical partners for contractors with specific site demands.
Recent corporate actions underscore these dynamics: model showcases at major trade events, distributor network expansions in key European regions, type‑approval wins in Southeast Asia, and partnerships aimed at strengthening local support. For market entrants and incumbents alike, such developments are early indicators of where competition will intensify in 2026.
What the full report delivers (practical, operational, proprietary)
Our Tower Crane Market report is intentionally designed as a decision‑ready toolset for 2026 planning cycles. Highlights include:
- Topline market sizing (historical 2020–2025 and forecast 2026–2032) with scenario‑based projections tied to macro inputs.
- A concentrated competitive index and qualitative benchmarking of product families, distribution strategies, and aftermarket capabilities.
- Procurement playbooks: vendor selection matrices, TCO models, contract structures for rental vs. ownership, and timing guidance linked to raw material cycles.
- Regulatory heatmaps and certification timelines for priority markets, including checklists and compliance risk scores for model approvals.
- Service and spare parts economics: SLA templates, warranty strategy options, and modular upgrade paths to extend fleet life.
- M&A and partnership scout list — high‑value targets profiled by strategic fit (geography, product, service footprint) and integration complexity.
- Dashboards and Excel models for sensitivity testing (price, steel cost, utilization), enabling CFOs and strategy leads to stress‑test capital plans.
Importantly, the report contains granular splits by lifting capacity, application, and region — analyzed to reveal demand pockets and margin differentials — but these proprietary segment tables and model outputs are gated to the full document to preserve client value and ensure credible benchmarking.
How to use these insights in 2026: six tactical moves
- Align procurement windows with steel‑price trend forecasts and supplier quoting behavior to preserve margin and avoid high‑cost backlogs.
- Prioritize certification roadmaps in market entry plans — faster approvals materially reduce time‑to‑revenue for new models.
- Shift capex from broad fleet expansion to selective high‑utilization units plus enhanced aftermarket contracts that improve uptime economics.
- Negotiate performance‑based service agreements with OEMs and dealers to internalize uptime risks.
- Identify regional distributors with proven erection and certification capabilities as strategic partners rather than transactional resellers.
- Use scenario models to size M&A targets or alliance partners that close distribution gaps or add certification assets quickly.
Final perspective
The tower crane market in 2026 is a market of disciplined growth: steady topline expansion, concentrated supplier power, and outsized returns available to operators who master lifecycle economics, regulatory agility, and aftermarket differentiation. Our research synthesizes these threads into a pragmatic strategic playbook — offering the granularity to inform procurement, product, and M&A decisions while protecting the proprietary modeling that delivers actionable competitive advantage.
For the detailed segment tables, certification timetables, vendor scorecards, and the full set of executable tools and models, access the complete PW Consulting Tower Crane Market report on our website. The full report is where the evidence meets the executable plan.
For detailed analysis of this topic, please visit the official page: Tower Crane Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Semitrailer Market 2026: Strategic Imperatives from PW Consulting’s Market Outlook
As fleets, OEMs, suppliers and private equity investors prepare strategic plans in 2026, the semitrailer market presents a mix of steady expansion, technological disruption and input-cost volatility. PW Consulting’s latest Semitrailer Market study (base year 2025; historical coverage 2020–2025; forecast 2026–2032) synthesizes the right combination of macros, competitive benchmarking and operational toolkits that decision-makers need to convert ambiguity into decisive action. The study calculates a compound annual growth rate (CAGR) of 5.6% through the forecast window and models multiple scenarios that take the market from USD 213.0 Million in 2025 to an illustrative mid-range outcome of roughly USD 312 Million by 2032.
Semitrailer (Semi-Trailer) Market
Why this study matters for 2026 decision cycles
-
Timing of capital allocation: With fleet replacement and factory-capacity investments being long‑lived, choices made in 2026 will determine cost position and market share for much of the next decade. Our forecast and scenario modules convert macro drivers into year-by-year demand curves engineers and CFOs can plug into capex plans.
Semitrailer (Semi-Trailer) Market -
Input-cost and margin management: Raw-material volatility and trade policy have materially altered cost structures. The report quantifies the margin sensitivity of common vehicle architectures to steel and aluminum price moves and helps prioritize design choices that protect gross margins.
Semitrailer (Semi-Trailer) Market -
Regulatory and safety roadmaps: Anticipated regulatory shifts—ranging from rear-impact guard certification rules to standardization of automatic emergency braking and automated driving system guidance—require product and compliance roadmaps. The study maps plausible regulatory milestones and the required engineering and testing investments.
-
Competitive positioning: The market remains fragmented (CR3 ~24.6%, CR5 ~26.2%), so focused consolidation, differentiated product strategy, or service-led models can all succeed. Our profiles and strategic playbook specify which go-to-market models work against each competitive archetype.
Market trajectory at a glance
The semitrailer market has shown resilient expansion through the early 2020s. PW Consulting’s historical reconstruction highlights a progression from a mid‑single‑hundred million USD market in 2020 to USD 213.0 Million in 2025. Under our central scenario—reflecting baseline macro growth, continued freight demand and incremental fleet modernization—market value reaches approximately USD 311.7 Million by 2032. The 5.6% CAGR embedded in our forecast reflects moderate fleet renewal rates, continued modal demand for road freight, and increasing value per trailer as electrification, telematics and safety features become standard.
Key dynamics shaping the market
-
Raw-material inflation: Steel prices climbed strongly in 2024–2025 (industry data shows a ~21% YoY increase as of April 2025), compressing margins and prompting design re‑optimization. Manufacturers face a trade-off: maintain legacy bill-of-materials to preserve pricing parity, or accelerate lightweight-material adoption—aluminum and composites—to offset fuel and emissions advantages for customers.
-
Trade and input protection: Continued tariffs on steel and aluminum imports materially raise component costs and favor regionalized sourcing or vertical integration strategies. The report models tariff pass-through under multiple pricing regimes and offers hedging and sourcing playbooks.
-
Safety and automation regulation: U.S. regulatory authorities signaled changes to certification labeling for rear-impact guards and are moving toward standardized automatic emergency braking requirements and updated automated driving system regulations. These shifts create both compliance costs and product differentiation opportunities for early adopters.
-
Product and technological evolution: Across OEMs we identify three complementary technology vectors—lightweight structures (aluminum/composite), telematics/connectivity, and safety automation integration. Success will depend on modular architectures that allow incremental upgrades rather than full redesigns.
-
Market fragmentation and channel economics: The relatively low market concentration means national champions coexist with specialty and regional producers. Pricing power varies by segment and application; aftermarket and service contracts are an increasingly attractive margin pool.
Competitive landscape—what incumbents are doing
Our report profiles over a dozen core manufacturers and maps their strategic posture along product breadth, manufacturing scale, material strategy and go-to-market model. Highlights include:
-
Platform and material leadership: Several established OEMs are doubling down on lightweight aluminum and composite assemblies to capture total cost of ownership (TCO) benefits—improving fuel economy and complying with tighter emissions expectations.
-
Connectivity and integrated chassis solutions: Major manufacturers are embedding telematics and advanced chassis designs, creating incremental recurring-revenue opportunities through data and fleet-management services.
-
Specialist and custom builders: Companies focusing on tankers, lowbeds, heavy‑haul and forestry applications are defending niche positions through patented designs and deep aftermarket service capabilities.
-
Scale players vs. nimble innovators: High-volume producers are leveraging production economics and distribution reach, while smaller manufacturers compete on custom engineering, speed-to-market and specialty configurations.
Recent industry moves illustrate these dynamics. In April 2026, one OEM completed a high‑speed rear impact guard crash validation test, setting a new safety benchmark for rear guards and signaling product differentiation through safety validation. Earlier, in 2025, several manufacturers rolled out eco‑focused product lines to align with emissions and sustainability expectations. These developments highlight how safety certification and green credentials are becoming competitive levers.
What the report contains (practical deliverables)
-
Market sizing and high‑frequency trend tables (base year 2025; historical 2020–2025; forecast 2026–2032) with scenario sensitivity to fuel, GDP and trade shocks.
-
Scenario analytics and stress tests: upside, baseline and downside demand paths linked to fleet-replacement timing and regulatory adoption curves.
-
Supply-chain cost models capturing material, labor and logistics drivers; tariff and hedging playbooks; and break-even analyses for alternative material use (steel vs. aluminum vs. composites).
-
Competitive profiles and capability maps for the leading manufacturers, including innovation posture, channel strength and M&A targets matched to strategic objectives.
-
Commercial playbooks: pricing strategy templates, aftermarket and service monetization frameworks, and sales-channel optimization recommendations.
-
Implementation tools: a downloadable Excel model (plug-and-play) to test investment options, and a prioritized 90‑day action plan for 2026 executives.
-
Regulatory impact assessments, including compliance timelines, testing cost estimates and implications of pending agency guidance on safety and automation.
Strategic recommendations for executives (2026 priorities)
-
Hedge material exposure and regionalize sourcing: Mitigate tariff and price risk by diversifying suppliers, pursuing longer-term contracts for critical grades of steel and exploring near-shore manufacturing options where economics permit.
-
Invest selectively in lightweight architectures: Target modular designs that allow incremental conversion to aluminum/composite skins and subframes, focusing first where fuel and emissions gains yield measurable customer TCO improvements.
-
Monetize telematics: Shift from one-time hardware sales to recurring revenue through fleet analytics, uptime guarantees and predictive-maintenance services, which enhance customer stickiness and stabilize margins.
-
Prepare for safety and automation mandates: Prioritize engineering capacity for automatic emergency braking integration and validate rear‑guard designs to capture early-adopter demand and avoid retrofit costs.
-
Evaluate M&A and partnership pathways: Use M&A to acquire specialty capabilities (e.g., tankers, lowbeds, refrigerated tech) or to scale manufacturing footprints in high-growth corridors identified by our regional demand overlays.
-
Expand service networks and parts availability: With aftermarket services representing an outsized margin opportunity, invest in dealer training, parts logistics and digital spare-part channels.
-
Embed scenario planning in capital allocation: Use the report’s scenario models to stress test factory utilization and working capital under alternative demand and raw-material price trajectories before finalizing 2026–2027 capex commitments.
How to use the report in your 2026 playbook
Use the study as a living decision-support asset: integrate the model into monthly planning; run bespoke “what-if” cases for your product families; and deploy the competitor capability maps to prioritize strategic partnerships or defensive moves. For private equity and corporate development teams, the report accelerates target screening and valuation sensitivity to material-price and regulatory outcomes. For OEM product leaders, the engineering impact matrices and validation-cost estimates make explicit the trade-offs between early compliance and potential first-mover advantage.
Closing—what we’re intentionally withholding here
To honor the “preview” principle and drive value to the full study, we have deliberately withheld the granular split tables and raw segment-by-region/application dollar values in this public summary. The full PW Consulting Semitrailer Market report contains detailed segmented forecasts, unit-volume assumptions, dealer-channel economics and proprietary demand maps that translate the high-level picture above into executable plans. Subscribers and clients gain access to the downloadable models, supplier-scorecards and the complete competitive databook.
If your 2026 priorities include optimizing supply-chain resilience, positioning for regulatory change, or capturing aftermarket revenue in a market growing at ~5.6% CAGR over the next several years, this study provides the analytic backbone and the practical tools to act with confidence.
For detailed analysis of this topic, please visit the official page: Semitrailer (Semi-Trailer) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Solder Market 2026: A Strategic Preview for Enterprise Decision-Makers
As companies prepare budgets, sourcing strategies, and product roadmaps for 2026, the solder market sits at an inflection point. Our latest PW Consulting Solder Market study — built on a base year of 2025 and a robust historical series from 2020–2025, with a forecast window through 2026–2032 — translates raw market movements into decision-ready intelligence. The global market has expanded steadily over the past half-decade (from a multi-billion-dollar base in 2020 to a larger multi-billion-dollar market in 2025) and is projected to continue growing through 2032 at a compound annual growth rate (CAGR) of roughly 4.2%. This preview outlines why that trajectory matters for sourcing, product planning, M&A, and risk management in 2026 — while intentionally withholding the granular segmented figures that our full report unlocks.
Solder Market
Market trajectory and what it signals to executives
Two features define the current market movement. First, steady top-line expansion reflects a combination of recovering electronics demand, incremental content growth in electrified vehicles and industrial electronics, and substitution dynamics driven by regulatory change. Second, growth is uneven across product forms and end-use contexts, creating both concentrated pockets of supplier power and open spaces where innovation can reshape economics.
Solder Market
For executives, the macro numbers matter because they set the perimeter of strategic choices. A market that is expanding mid-single digits annually supports capacity investments and targeted vertical integration — but only when those investments are matched to resilient end-markets and defensible technology positions. Conversely, modest growth amplifies the importance of operational excellence, cost pass-through mechanisms, and nimble product development to capture higher-margin niches.
Solder Market
Why supply-side dynamics will dominate 2026 decisions
- Raw material sensitivity: Tin-based chemistries remain the backbone of solder demand and therefore a key determinant of cost and availability. Volatility in tin and specialty alloy inputs transmits directly to finished-solder pricing and contract terms for electronics assemblers.
- Regulatory drivers: Global restrictions on hazardous substances have accelerated lead-free adoption. That transition increases the technical bar for materials and raises both procurement complexity and quality-assurance requirements across the value chain.
- Cost structure shifts: Lead-free materials carry a material-cost premium relative to traditional solders. Procurement teams, OEMs, and contract manufacturers must reconcile product reliability mandates with margin pressures and, in some cases, redesign opportunities to reduce solder consumption.
These forces combine to elevate the value of integrated supply strategies in 2026: long-term purchase agreements with indexed clauses, supplier development partnerships focused on yield and reliability, and hedging approaches for raw-material exposure will all be on the table.
Segmentation and where the hidden opportunities sit
The full market contains multiple intersecting segmentation lenses — by geography, product type, and end-use application — each with distinct growth dynamics. In this preview we highlight directional conclusions without disclosing the underlying split tables, which are reserved for the full report.
- Application dynamics: Consumer electronics continues to anchor demand, but rising content intensity in automotive and industrial electronics is reshaping growth profiles. For firms evaluating product roadmaps, the implication is clear: engineering requirements for reliability, thermal cycling, and miniaturization must be tailored to these high-growth, high-value end uses.
- Product form evolution: Paste, wire, powder, and emerging preforms each present different margin and technology pathways. Process automation, miniaturization, and semiconductor packaging trends are increasing the strategic relevance of high-reliability pastes and solder balls — creating white spaces for specialist suppliers that can combine material science with manufacturing-scale consistency.
- Regional nuance: Supply-chain resilience strategies should be segmented by sourcing risk and proximity to key assembly clusters. The full report includes modeled scenarios for trade disruption, tariff volatility, and transportation constraints; preview readers should note that regional market behavior will materially affect tactical procurement and inventory strategies.
Competitive landscape: from global leaders to specialized challengers
The solder industry’s structure combines significant global players with technically focused specialists. Market concentration at the top is meaningful but not monopolistic: the three largest suppliers account for roughly 45% of global volumes, while the top five reach around 55%. That concentration implies that while major suppliers set industry standards for certifications, service levels, and supply continuity, there remains room for focused players to win on niche performance attributes, technical service, or proximity to customers.
Key incumbent behaviors to watch in 2026:
- Technology leadership and certification: Leading manufacturers continue to invest in high-reliability formulations and process certifications that unlock premium OEM contracts. Recent trade-show showcases and product awards signal an ongoing race to demonstrate reliability in accelerated thermal and electrical stress contexts.
- Portfolio consolidation and M&A: Strategic acquisitions are being used to expand lead-free capabilities or to acquire complementary product forms. Such moves not only broaden technical offerings but also provide immediate access to regional customers and supply contracts.
- Customer intimacy at scale: Suppliers with deep field application engineering capabilities tend to capture higher lifetime value; expect increased investments in co-development, failure analysis centers, and on-site process optimization services.
Representative company dynamics illustrate these trends. Several established suppliers — specialists in high-reliability solder pastes, alloys, and assembly materials — continue to advance product portfolios and client credentials through public awards, trade-show launches, and targeted acquisitions. Meanwhile, specialized manufacturers focused on semiconductor packaging components are consolidating their positions by strengthening relationships with foundries and OSATs. These moves reflect a market in which technical differentiation, certified reliability, and supply certainty are primary competitive levers.
Recent developments shaping the near-term competitive field
- Leading suppliers are using industry forums and expos to launch next-generation high-reliability alloys and pastes, signaling their intent to capture higher-value assembly segments.
- Recognition programs and supplier awards from major OEMs underline the importance of quality systems and responsiveness; such credentials increasingly act as gatekeepers for strategic sourcing lists.
- Acquisitions by regional and niche players have accelerated consolidation in targeted product lines, particularly those enabling lead-free transitions and semiconductor packaging.
What the full PW Consulting Solder Market report delivers
The complete study is designed as an operational playbook for procurement, engineering, and corporate strategy teams. Key contents include:
- Industry-level historical reconstruction (2020–2025) and a transparent forecast (2026–2032) aligned to market drivers and scenario stress tests.
- Demand-model frameworks that translate end-market trends into material and form-level consumption — with sensitivity runs for raw-material volatility and regulatory tightening.
- Supplier benchmarking: capability heat maps, service-level evaluations, and an assessment of customer-lock factors across major global providers.
- Practical go-to-market and sourcing playbooks: contract templates, hedging and inventory strategies, and co-development frameworks tailored to lead-free and high-reliability segments.
- Deal flow and M&A diagnostic tools, including acquisition target scoring, integration risk checklists, and valuation comparators informed by market concentration metrics.
Note: this introductory article intentionally omits the detailed regional, type, and application split tables and the granular revenue breakdowns that are included in the full paid report. Those granular data outputs are critical for transaction diligence, capex allocation, and product-line P&L planning — and they are available on the report landing page.
Strategic recommendations for 2026 planning cycles
- Prioritize supplier qualification for lead-free reliability: Given regulatory momentum and technical complexity, OEMs should fast-track validation programs with suppliers that demonstrate reproducible yields under automotive and industrial stress conditions.
- Design procurement contracts for transparency: Include cost-pass mechanisms tied to raw-material indices, service-level KPIs for lot traceability, and flexible volume clauses to manage demand variability.
- Targeted investments over broad expansion: With mid-single-digit market growth at the macro level, capital allocation should favor niche capacity that delivers higher margins (e.g., high-reliability pastes, advanced preforms) rather than general-purpose scale alone.
- Use M&A selectively to acquire capability, not just capacity: Look for targets that add differentiated chemistries, advanced packaging assets, or on-site engineering services that accelerate customer conversion and margin expansion.
- Embed scenario planning into supply-chain decisions: Model tin supply shocks, regulatory accelerations, and regional assembly shifts to stress-test sourcing choices and inventory policies.
Final perspective
For 2026, the solder market is not defined by runaway expansion but by a reallocation of value toward reliability, technical differentiation, and supply resilience. The headline CAGR of approximately 4.2% through 2032 frames the macro opportunity, while concentration metrics — near-term supplier dominance combined with specialist challenger momentum — shape the competitive battlefield.
PW Consulting’s full Solder Market report translates these macro trends into executable plans: quantified demand models, supplier scorecards, scenario-ready procurement playbooks, and M&A diagnostics. If your 2026 decisions hinge on sourcing certainty, product-reliability differentiation, or targeted M&A, the full dataset and diagnostic modules provide the selective granularity required for high-confidence execution.
Next steps
- Access the full report to retrieve the detailed regional, type, and application splits, along with downloadable model files and supplier scorecards.
- Engage PW Consulting for a tailored briefing: scenario workshops and bespoke stress-testing of your supply and product strategies are available as advisory add-ons.
For decision-makers seeking to convert market visibility into operational advantage in 2026, the pathway is clear: combine rigorous supplier selection with targeted technical investment and contract structures that internalize the supply risks and reliability premiums now shaping the solder market. Our full study provides the data and the playbook; this preview outlines why acting now will determine who captures the premium in the years ahead.
For detailed analysis of this topic, please visit the official page: Solder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Metal Injection Molding Materials to reach USD 7,623 Million by 2032 at 9.5% CAGR
By pmarketresearch, 2026-07-13
Metal Injection Molding Materials Market: Strategic Briefing for 2026 Decision-Makers
Executive snapshot
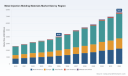
As PW Consulting’s chief industry analyst, I present a strategic primer designed to translate our Metal Injection Molding (MIM) Materials Market study into immediate, board-level action in 2026. The market has transitioned from niche engineering volumes into a structurally growing market: total industry revenues expanded from roughly USD 2.64 billion in 2020 to about USD 4.05 billion in 2025, and our forecast projects continued expansion to approximately USD 7.62 billion by 2032 at a compounded annual growth rate (CAGR) of 9.5% through the 2026–2032 horizon. Market concentration remains moderate (CR3 ~35%; CR5 ~55%), indicating a mix of established suppliers and specialist challengers—an environment ripe for strategic M&A, vertical integration, and value-chain repositioning.
Metal Injection Molding Materials Market
Why this research matters for 2026 planning
Companies facing 2026 planning cycles must move beyond conventional market-sizing and towards operational playbooks that convert growth into margin and resilience. The MIM materials market is being reshaped by three concurrent forces: accelerating end-market demand for complex, high-performance metallic components; intensifying supply-side specialization around powders and feedstocks; and non-negotiable sustainability and domestic-sourcing policies in key jurisdictions. Our report synthesizes these drivers into decision-ready frameworks—enabling executives to prioritize CAPEX, procurement strategies, partnership models, and regulatory investments with a clear view of timing and return.
Metal Injection Molding Materials Market
Key strategic implications
- Sourcing and supply resilience: Feedstock and powder availability are tactical constraints that can determine production uptime and unit economics. Senior procurement teams should treat powder suppliers not as commodity vendors but as strategic partners—locking multi-year offtakes, co-investing in qualification testing, and building alternative supply lanes to mitigate single-supplier exposure.
- Make-vs-buy recalibration: With demand growing near double digits annually, several component makers are reconsidering vertical integration into feedstock compounding or powder handling. Our scenario analyses quantify break-even horizons and sensitivity to powder pricing and feedstock yields to support capex trade-offs.
- Product and material prioritization: Not all alloys and feedstock chemistries deliver equal margin or strategic value. A prioritized material roadmap—aligned to target applications and manufacturability—reduces development costs and shortens time-to-revenue for high-value components.
- Regulatory and sustainability positioning: Stricter environmental policies in multiple markets increase the cost of non-compliance and create a premium for lower-carbon, low-waste feedstock processes. Companies that can demonstrate lifecycle advantages will gain both procurement preference and price resiliency.
Supply-chain dynamics and feedstock economics
Feedstock cost and powder availability are the operational fulcrum of MIM economics. In 2026, procurement teams will still face price volatility tied to metal powder production capacity and atomization throughput. Our study maps upstream capacity, identifies pinch-points in atomization and feedstock compounding, and models how feedstock price shocks cascade through manufacturing cost models. For strategy teams, the practical takeaway is clear: cost control in MIM is as much about securing powder continuity and quality as it is about downstream processing efficiency.
Metal Injection Molding Materials Market
Innovation and product strategy
Innovation in feedstock chemistry, debinding techniques, and additive hybrid processes is accelerating. Material selection (stainless steels, titanium alloys, copper alloys, magnetic alloys and specialty blends) remains a primary lever for differentiating performance in automotive, medical, aerospace and electronics applications. Our research identifies which material innovations are closest to commercial maturity and where investment in co-development with feedstock specialists will create defensible IP and shortened qualification cycles.
Competitive landscape—what to watch in 2026
The competitive map features global materials giants, specialized powder houses, and regional feedstock manufacturers. Leading players such as BASF and large powder specialists continue to invest in sustainable feedstock solutions and capacity expansions, while advanced powder producers and regional champions drive custom blends for niche applications. Recent industry moves—product launches focused on sustainability, site-level capacity investments, and active industry conference pipelines—signal an escalation in both product and production competition. For corporate strategists, the implications are:
- Prioritize supplier segmentation by capability (e.g., atomization technology, alloy breadth, feedstock compounding) rather than geography alone.
- Evaluate joint-development agreements with suppliers that offer co-funded qualification programs and technology transfer clauses.
- Scan for acquisition or minority-investment targets among mid-sized feedstock producers where integration can capture margin and secure supply.
Recent industry signals to incorporate into plans
Three recent developments crystallize near-term opportunities and risks: (1) established chemical and materials firms releasing new low-impact powder and feedstock lines, signaling a product premium for sustainability; (2) capacity investments by leading powder-metallurgy groups, reflecting anticipated demand for higher-purity and specialty powders; and (3) heightened industry collaboration and knowledge-exchange at technical conferences—accelerating best-practice adoption. These signals inform timing for procurement contracts, R&D alliances, and capacity investments—our report aligns each type of corporate action with an expected impact horizon (short, medium, long).
What the PW Consulting report delivers (practical contents)
This study is designed as an operational toolkit for 2026 decisions. Highlights include:
- Validated market sizing and scenario forecasts (base year 2025; forecast 2026–2032) with sensitivity to price, adoption, and regulatory variables.
- Supply-chain maps and supplier capability heatmaps to prioritize partners for qualifying programs and strategic sourcing.
- Commercial benchmarking: price bands, typical contract structures, quality KPIs and expected qualification timelines for key alloy classes.
- Operational playbooks: make-vs-buy models, CAPEX calculators, and production scale-up checklists tailored to MIM feedstocks and component facilities.
- Technology readiness assessments that rank innovations by commercialization risk and expected margin upside.
- Regulatory impact matrix linking regional policy scenarios to material choices and certification paths.
- Competitive intelligence dossiers and a transaction-ready shortlist for M&A and JV opportunities—scored by strategic fit and integration complexity.
How to use this research across your organization
Decision-use cases we designed the deliverable for:
- Strategy teams: prioritize adjacent growth moves and inorganic targets with quantified payback windows.
- Procurement: construct layered sourcing strategies, contract templates, and hedging options for powder supply.
- Operations and manufacturing: size capital investments, plan capacity ramp sequencing and optimize yield pathways.
- R&D and product teams: select alloy-development targets, structure supplier co-development agreements and compress qualification timelines.
- Investor relations and corporate development: craft growth narratives grounded in market and supplier dynamics that support valuation discussions.
Deliberate withholding: why core segmentation data is reserved
Consistent with the “trailer” principle for this briefing, we present high-confidence macro trends, forecasts, and strategic implications to establish credibility, while reserving granular segmentation matrices and proprietary supplier-level data for the full report. The deep segmentation (by region, alloy type, and application), detailed price curves and supplier scorecards are high-value assets in our product and are available in the full deliverable. Executives evaluating competitive bids, negotiating long-term feedstock contracts, or executing on cross-border capacity plans will find those datasets essential for tactical execution.
Next steps for 2026 planning
If your 2026 strategy cycle includes supply-chain resilience, product differentiation, or potential acquisitions in the MIM materials space, we recommend three immediate actions:
- Commission a 90-day supplier qualification sprint with clearly defined performance gates and co-development milestones.
- Run a targeted make-vs-buy financial model for any planned capacity investments, using conservative powder-price scenarios and the report’s CAPEX multipliers.
- Engage our M&A screening module to identify 3–5 tactical acquisition targets that can accelerate your entry into specialty feedstocks or high-value alloys.
Closing
The MIM materials market offers a rare intersection of sustained demand growth, material-led differentiation and supply-side specialization. For leaders who move decisively in 2026—aligning procurement, R&D and corporate development around validated scenarios—there is substantial upside in margin capture and strategic positioning. For access to the complete segmentation tables, supplier-level dossiers, and our decision-grade financial models, please consult the full PW Consulting Metal Injection Molding Materials Market report on our publication page.
For detailed analysis of this topic, please visit the official page: Metal Injection Molding Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com