

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Solder Market Poised for 4.2% CAGR

Solder Market 2026: A Strategic Preview for Enterprise Decision-Makers
As companies prepare budgets, sourcing strategies, and product roadmaps for 2026, the solder market sits at an inflection point. Our latest PW Consulting Solder Market study — built on a base year of 2025 and a robust historical series from 2020–2025, with a forecast window through 2026–2032 — translates raw market movements into decision-ready intelligence. The global market has expanded steadily over the past half-decade (from a multi-billion-dollar base in 2020 to a larger multi-billion-dollar market in 2025) and is projected to continue growing through 2032 at a compound annual growth rate (CAGR) of roughly 4.2%. This preview outlines why that trajectory matters for sourcing, product planning, M&A, and risk management in 2026 — while intentionally withholding the granular segmented figures that our full report unlocks.
Solder Market
Market trajectory and what it signals to executives
Two features define the current market movement. First, steady top-line expansion reflects a combination of recovering electronics demand, incremental content growth in electrified vehicles and industrial electronics, and substitution dynamics driven by regulatory change. Second, growth is uneven across product forms and end-use contexts, creating both concentrated pockets of supplier power and open spaces where innovation can reshape economics.
Solder Market
For executives, the macro numbers matter because they set the perimeter of strategic choices. A market that is expanding mid-single digits annually supports capacity investments and targeted vertical integration — but only when those investments are matched to resilient end-markets and defensible technology positions. Conversely, modest growth amplifies the importance of operational excellence, cost pass-through mechanisms, and nimble product development to capture higher-margin niches.
Solder Market
Why supply-side dynamics will dominate 2026 decisions
- Raw material sensitivity: Tin-based chemistries remain the backbone of solder demand and therefore a key determinant of cost and availability. Volatility in tin and specialty alloy inputs transmits directly to finished-solder pricing and contract terms for electronics assemblers.
- Regulatory drivers: Global restrictions on hazardous substances have accelerated lead-free adoption. That transition increases the technical bar for materials and raises both procurement complexity and quality-assurance requirements across the value chain.
- Cost structure shifts: Lead-free materials carry a material-cost premium relative to traditional solders. Procurement teams, OEMs, and contract manufacturers must reconcile product reliability mandates with margin pressures and, in some cases, redesign opportunities to reduce solder consumption.
These forces combine to elevate the value of integrated supply strategies in 2026: long-term purchase agreements with indexed clauses, supplier development partnerships focused on yield and reliability, and hedging approaches for raw-material exposure will all be on the table.
Segmentation and where the hidden opportunities sit
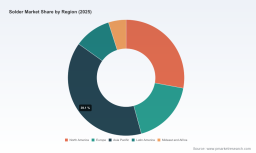
The full market contains multiple intersecting segmentation lenses — by geography, product type, and end-use application — each with distinct growth dynamics. In this preview we highlight directional conclusions without disclosing the underlying split tables, which are reserved for the full report.
- Application dynamics: Consumer electronics continues to anchor demand, but rising content intensity in automotive and industrial electronics is reshaping growth profiles. For firms evaluating product roadmaps, the implication is clear: engineering requirements for reliability, thermal cycling, and miniaturization must be tailored to these high-growth, high-value end uses.
- Product form evolution: Paste, wire, powder, and emerging preforms each present different margin and technology pathways. Process automation, miniaturization, and semiconductor packaging trends are increasing the strategic relevance of high-reliability pastes and solder balls — creating white spaces for specialist suppliers that can combine material science with manufacturing-scale consistency.
- Regional nuance: Supply-chain resilience strategies should be segmented by sourcing risk and proximity to key assembly clusters. The full report includes modeled scenarios for trade disruption, tariff volatility, and transportation constraints; preview readers should note that regional market behavior will materially affect tactical procurement and inventory strategies.
Competitive landscape: from global leaders to specialized challengers
The solder industry’s structure combines significant global players with technically focused specialists. Market concentration at the top is meaningful but not monopolistic: the three largest suppliers account for roughly 45% of global volumes, while the top five reach around 55%. That concentration implies that while major suppliers set industry standards for certifications, service levels, and supply continuity, there remains room for focused players to win on niche performance attributes, technical service, or proximity to customers.
Key incumbent behaviors to watch in 2026:
- Technology leadership and certification: Leading manufacturers continue to invest in high-reliability formulations and process certifications that unlock premium OEM contracts. Recent trade-show showcases and product awards signal an ongoing race to demonstrate reliability in accelerated thermal and electrical stress contexts.
- Portfolio consolidation and M&A: Strategic acquisitions are being used to expand lead-free capabilities or to acquire complementary product forms. Such moves not only broaden technical offerings but also provide immediate access to regional customers and supply contracts.
- Customer intimacy at scale: Suppliers with deep field application engineering capabilities tend to capture higher lifetime value; expect increased investments in co-development, failure analysis centers, and on-site process optimization services.
Representative company dynamics illustrate these trends. Several established suppliers — specialists in high-reliability solder pastes, alloys, and assembly materials — continue to advance product portfolios and client credentials through public awards, trade-show launches, and targeted acquisitions. Meanwhile, specialized manufacturers focused on semiconductor packaging components are consolidating their positions by strengthening relationships with foundries and OSATs. These moves reflect a market in which technical differentiation, certified reliability, and supply certainty are primary competitive levers.
Recent developments shaping the near-term competitive field
- Leading suppliers are using industry forums and expos to launch next-generation high-reliability alloys and pastes, signaling their intent to capture higher-value assembly segments.
- Recognition programs and supplier awards from major OEMs underline the importance of quality systems and responsiveness; such credentials increasingly act as gatekeepers for strategic sourcing lists.
- Acquisitions by regional and niche players have accelerated consolidation in targeted product lines, particularly those enabling lead-free transitions and semiconductor packaging.
What the full PW Consulting Solder Market report delivers
The complete study is designed as an operational playbook for procurement, engineering, and corporate strategy teams. Key contents include:
- Industry-level historical reconstruction (2020–2025) and a transparent forecast (2026–2032) aligned to market drivers and scenario stress tests.
- Demand-model frameworks that translate end-market trends into material and form-level consumption — with sensitivity runs for raw-material volatility and regulatory tightening.
- Supplier benchmarking: capability heat maps, service-level evaluations, and an assessment of customer-lock factors across major global providers.
- Practical go-to-market and sourcing playbooks: contract templates, hedging and inventory strategies, and co-development frameworks tailored to lead-free and high-reliability segments.
- Deal flow and M&A diagnostic tools, including acquisition target scoring, integration risk checklists, and valuation comparators informed by market concentration metrics.
Note: this introductory article intentionally omits the detailed regional, type, and application split tables and the granular revenue breakdowns that are included in the full paid report. Those granular data outputs are critical for transaction diligence, capex allocation, and product-line P&L planning — and they are available on the report landing page.
Strategic recommendations for 2026 planning cycles
- Prioritize supplier qualification for lead-free reliability: Given regulatory momentum and technical complexity, OEMs should fast-track validation programs with suppliers that demonstrate reproducible yields under automotive and industrial stress conditions.
- Design procurement contracts for transparency: Include cost-pass mechanisms tied to raw-material indices, service-level KPIs for lot traceability, and flexible volume clauses to manage demand variability.
- Targeted investments over broad expansion: With mid-single-digit market growth at the macro level, capital allocation should favor niche capacity that delivers higher margins (e.g., high-reliability pastes, advanced preforms) rather than general-purpose scale alone.
- Use M&A selectively to acquire capability, not just capacity: Look for targets that add differentiated chemistries, advanced packaging assets, or on-site engineering services that accelerate customer conversion and margin expansion.
- Embed scenario planning into supply-chain decisions: Model tin supply shocks, regulatory accelerations, and regional assembly shifts to stress-test sourcing choices and inventory policies.
Final perspective
For 2026, the solder market is not defined by runaway expansion but by a reallocation of value toward reliability, technical differentiation, and supply resilience. The headline CAGR of approximately 4.2% through 2032 frames the macro opportunity, while concentration metrics — near-term supplier dominance combined with specialist challenger momentum — shape the competitive battlefield.
PW Consulting’s full Solder Market report translates these macro trends into executable plans: quantified demand models, supplier scorecards, scenario-ready procurement playbooks, and M&A diagnostics. If your 2026 decisions hinge on sourcing certainty, product-reliability differentiation, or targeted M&A, the full dataset and diagnostic modules provide the selective granularity required for high-confidence execution.
Next steps
- Access the full report to retrieve the detailed regional, type, and application splits, along with downloadable model files and supplier scorecards.
- Engage PW Consulting for a tailored briefing: scenario workshops and bespoke stress-testing of your supply and product strategies are available as advisory add-ons.
For decision-makers seeking to convert market visibility into operational advantage in 2026, the pathway is clear: combine rigorous supplier selection with targeted technical investment and contract structures that internalize the supply risks and reliability premiums now shaping the solder market. Our full study provides the data and the playbook; this preview outlines why acting now will determine who captures the premium in the years ahead.
For detailed analysis of this topic, please visit the official page: Solder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com