

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
Lightweight Conveyor Belts Market: USD 215M in 2025, rising to USD 390.5M by 2032 at 8.9% CAGR
By pmarketresearch, 2026-07-13
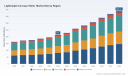
Lightweight Conveyor Belts Market — Strategic Imperatives for 2026 Decision-Making
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a distillation of the strategic intelligence embedded in our new Lightweight Conveyor Belts Market study. Anchored on a 2025 base year and a projected compound annual growth rate (CAGR) of 8.9% over the 2026–2032 forecast window, the market demonstrates robust expansion: from roughly USD 163 million in 2020 to an estimated USD 215 million in 2025, and approaching USD 391 million by 2032. For executives planning capital allocation, product roadmaps, or M&A moves in 2026, the right combination of timing and precision will determine winners and also-rans. This introductory briefing highlights the report’s strategic value while intentionally withholding core segment-level datapoints to guide you to the full study for the detailed models and proprietary spreadsheets.
Lightweight Conveyor Belts Market
Why this research matters in 2026
-
Actionable forecasting: The study converts a multi-year growth trajectory and volatility drivers into scenario-ready forecasts. CFOs and strategy teams can translate these into CAPEX phasing and working-capital models for 2026–2028.
Lightweight Conveyor Belts Market -
Competitive signaling: Our analysis exposes where leading vendors are placing bets—capacity expansion, product extensions, and hygiene-led innovation—enabling timely countermeasures or partnership plays.
Lightweight Conveyor Belts Market -
Risk-to-reward clarity: The report isolates raw-material sensitivity, regulatory risk, and aftermarket service opportunities so procurement and commercial functions can prioritize hedges and premium pricing where feasible.
-
Execution playbooks: For product managers and business development teams, the study translates macro trends into prioritized initiatives (e.g., material selection, modularization, service models) with measurable ROI frameworks.
Market dynamics shaping 2026 decisions
-
Structural demand drivers: Continued automation in food processing, e-commerce-driven logistics, and tighter hygiene regimes are core growth levers. Lightweight belts reduce conveyor energy demand and machine wear, accelerating replacement and retrofit cycles across automation projects.
-
Material & cost pressure: Polyurethane and other engineered thermoplastics remain attractive for hygiene and durability, but producers face cost pressures from feedstock volatility. In 2026 we observed material price upticks in key Asia supply hubs that compress margins for PU-heavy portfolios, prompting manufacturers to reassess pricing and sourcing strategies.
-
Regulatory & standards convergence: Food contact regulations across major markets (FDA, EU) and machine-safety standards such as ISO 22100-4 are tightening spec requirements. Compliance is now a commercial differentiator—buyers increasingly treat certifications and documented hygienic performance as non-negotiable selection criteria.
-
Environmental and process innovation: Water-based polyurethane and other lower-VOC formulations are moving from niche to mainstream as OEMs and end-users seek both hygiene and reduced environmental footprint. This shift is reflected in recent capacity and product investments by major suppliers.
-
Channel & aftermarket economics: Serviceable, retrofit-friendly belt designs and digital condition monitoring are unlocking recurring revenue streams—an important margin lever as product commoditization accelerates.
Competitive landscape — what the incumbents’ moves signal
The market exhibits moderate concentration: the top three players account for a meaningful but not dominant share of global revenues, and the top five consolidate a clear majority of industry scale. This structure creates an environment where global leaders set technology and compliance benchmarks, while focused specialists capture niche premium segments.
-
Habasit (Switzerland) — Strengths: fabric-based hygienic belts and deep food-sector relationships. Strategic relevance: leadership in tailored solutions for hygienic processing lines; watch for moves into integrated service contracts and digital installation aids.
-
Ammeraal Beltech (Netherlands) — Strengths: broad synthetic and modular portfolio plus fabrication capabilities. Strategic relevance: recent investments include a new plant dedicated to water-based polyurethane production—an explicit bet on sustainable, food-grade chemistries and a signal to competitors to de-risk legacy solvent-based supply chains.
-
Chiorino (Italy) — Strengths: precision in process-belt engineering for industrial automation. Strategic relevance: vertical focus on automation OEMs gives it a route to embed belts within machine-package sales, increasing switching costs for end-users.
-
Forbo Siegling (Germany) — Strengths: Transilon fabric-based belts and modular plastics. Strategic relevance: positions itself across fabric and plastic lines—an advantage in mixed-application accounts requiring both solutions.
-
Intralox (United States) — Strengths: modular plastic solutions optimized for food hygiene. Strategic relevance: aggressive product cadence in 2026 (notable belting and installation tool launches) shows a dual track of product performance improvement and installer productivity — a classic penetration strategy.
-
Volta Belting (Netherlands) — Strengths: homogeneous thermoplastic belts focused on hygiene and durability. Strategic relevance: recent introduction of a high-strength hygienic material underscores premiumization and the value of material science differentiation at trade shows and sector events.
-
Derco & Esbelt (Netherlands/Spain) — Strengths: pragmatic portfolios across PVC, PU, and plastic modular belts. Strategic relevance: these players often serve regional channels and act as important partners for OEMs seeking localized supply and fabrication services.
Taken together, these moves show an industry where incumbents deploy a mix of product innovation, capacity expansion, and installation/service tooling to protect margins and capture long-term service revenues. For potential entrants or capital allocators, the message is clear: compete on demonstrable hygiene performance, installer ergonomics, and supply-chain resilience—not just price.
What the full report delivers (actionable scope)
-
Robust market sizing and forecast models (2020–2032) including base-year reconciliation and scenario overlays tuned to material-price shocks and regulatory shifts.
-
Segment-level maps across types, applications and regions with buyer persona profiles that translate technical specifications into procurement decision criteria.
-
Profit-pool analysis identifying where manufacturing scale, customization, and aftermarket service create highest margin opportunities.
-
Supply-chain sensitivity matrix quantifying impact of raw-material swings and regional sourcing constraints on gross margins, with suggested procurement hedge structures.
-
Competitive benchmarking including product-technology matrices, capability heatmaps and a tactical watchlist of near-term strategic moves by key vendors.
-
Regulatory and standards playbook mapping compliance checkpoints by region and application—critical for commercialization timelines in food and pharma segments.
-
Decision-ready playbooks for go-to-market, pricing, channel design and M&A screening (including deal rationale templates and integration checklists).
-
Downloadable excel models and sensitivity dashboards for CFOs to stress-test CAPEX alternatives and investment returns under multiple scenarios.
How to use these insights in your 2026 playbook
-
Prioritize investments where regulatory and hygiene tailwinds create premium pricing power. If you serve food processors or pharma, emphasize certified materials and documented cleaning protocols.
-
Stress-test procurement: run material-price stress scenarios and build alternative sourcing and substitution strategies for polymer feedstocks—particularly polyurethane inputs where feedstock volatility can quickly erode margins.
-
Design product roadmaps that combine material innovation with installer ergonomics and serviceability. Tool launches that improve installation consistency (tensioning tools, clamp sets) amplify product propositions and reduce system downtime — a clear route to aftermarket revenues.
-
Consider targeted capacity moves or partnerships: the market’s concentrated but fragmented nature means strategic joint ventures or bolt-on acquisitions can rapidly scale capabilities in hygiene-certified manufacturing or localized fabrication.
-
Embed service and digital monitoring as part of pricing strategies. Recurring revenue models mitigate cyclical exposure and raise lifetime value per account.
Top-level recommendations
-
Make hygiene- and compliance-led product differentiation a priority rather than an afterthought.
-
Hedge feedstock exposure through diversified procurement and consider investing in water-based chemistries or alternative polymers.
-
Invest in installer productivity and condition-monitoring tools to unlock aftermarket margins.
-
Pursue targeted M&A or partnerships to achieve regional scale quickly where you lack fabrication or service presence.
-
Use scenario modeling to phase CAPEX aligned to 2026 demand inflection points—avoid all-or-nothing expansion bets.
PW Consulting’s full Lightweight Conveyor Belts Market report contains the granular segment models, regional breakdowns and proprietary market-share datasets that underpin these strategic takeaways. This introduction is designed as a tactical “preview”: it maps the terrain and flags where real competitive advantage will be earned in 2026, while preserving the detailed segment outputs and decision tools for the full report. For organizations preparing board-level investment memoranda, supplier negotiations, or acquisition screens this year, the full dataset and executable playbooks provide the difference between informed risk and speculative bets.
Contact the PW Consulting publications desk to access the complete study, the downloadable financial models, and the executive briefing package tailored for your strategic planning cycle.
For detailed analysis of this topic, please visit the official page: Lightweight Conveyor Belts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: VRB Market to Reach USD 2,050.55M by 2032 at 20.07% CAGR
By pmarketresearch, 2026-07-13
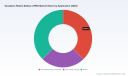
Vanadium Redox Battery (VRB) Market — Strategic Preview for 2026 Decisions
PW Consulting’s Vanadium Redox Battery (VRB) Market preview synthesizes the commercial, technological, and policy forces that will determine winners and losers through 2026 and beyond. Anchored on an independent market model (base year 2025, forecast period 2026–2032), the VRB market is accelerating: our topline model shows a compound annual growth rate (CAGR) of 20.07% across the forecast horizon and a market trajectory from the mid-hundreds of USD million in 2025 to multi-billion scale by 2032. This preview highlights the strategic implications of that growth for corporates, investors, and policymakers while intentionally withholding detailed regional and application splits — readers are invited to consult the full PW Consulting report for the underlying segment tables, interactive models, and primary-source evidence.
Vanadium Redox Battery (VRB) Market
Why this research matters for 2026 decision-makers
-
Capital allocation: The rapid expansion implied by a ~20% CAGR demands early clarity on system-level economics (capex, opex, energy-to-power sizing). Projects approved in 2026 will compete on lifetime cost curves that shift materially as vanadium pricing and policy incentives evolve.
Vanadium Redox Battery (VRB) Market -
Procurement and contracting: Buyers must balance stack suppliers’ roadmaps, electrolyte supply security, and warranty regimes — decisions that lock-in exposure for a decade or more.
Vanadium Redox Battery (VRB) Market -
Supply chain resilience: With the vanadium electrolyte representing a dominant portion of manufacturing cost, procurement strategy (vertical integration, recycling, offtake) becomes a core risk-management lever.
-
Regulatory alignment: Policy signals in 2025–2026 (tax credits, LDES incentives, and battery supply-chain rules) materially change effective project economics and buyer eligibility.
-
Competitive positioning: Active players are scaling projects from utility-grade GWh deployments to community microgrids; discerning partners and M&A targets in 2026 will gain a multi-year advantage.
Topline market dynamics — what is driving the runway
-
Rapid capacity scaling: The market’s growth curve reflects both large utility-scale commissions and an expanding set of commercial & industrial and community use cases where long-duration, non-flammable storage is preferred.
-
Electrolyte cost sensitivity: Vanadium electrolyte is the single-largest cost item in system BOMs — literature and our sector analysis converge on an estimate that ranges from roughly one-third to over one-half of manufacturing cost in typical 1 MW class systems. That concentration creates a direct transmission of vanadium price and production-cost volatility into levelized storage costs.
-
Policy tailwinds and headwinds: The expansion of investment tax credits for standalone storage (e.g., a 30% ITC in some jurisdictions) effectively reduces upfront capital by nearly one-third for eligible projects, supercharging project IRR calculations. Conversely, stricter battery supply-chain due diligence (notably EU battery regulation in force from 2024) imposes compliance costs and sourcing constraints that can disadvantage suppliers reliant on conflict-affected or opaque supply chains.
-
Demand-pull for long-duration services: Governments and system operators are increasingly procuring multi-hour capacity products and renewable integration services. Incentives and procurement frameworks for long-duration energy storage are a primary demand vector supporting VRB adoption.
-
Manufacturing economics and labor: Production cost sensitivity to energy-to-power ratios (E/P) and labor intensity rises with certain design choices; our models show that production costs can increase materially at higher duration configurations, reinforcing the need for design optimization and scale economies.
What the PW Consulting report delivers — practical, actionable contents
-
Proprietary market model (base year 2025, forecast 2026–2032) with scenario toggles: policy sensitivity, vanadium price paths, and technology learning curves. The model is delivered in an interactive spreadsheet so clients can stress-test assumptions for capital planning.
-
Cost and margin breakdowns by system architecture, lifecycle cost curves, and a procurement playbook that translates BOM exposure into contract clauses and hedging strategies.
-
Vendor benchmarking and technology scorecards that assess cycle life, depth-of-discharge, efficiency, modularity, and safety certifications — enabling RFP shortlists aligned to specific use cases (utility, C&I, microgrid).
-
Supply-chain maps and due-diligence checklists tailored to regulatory regimes (e.g., US tax incentives and EU battery sourcing rules), plus practical workflows for securing electrolyte supply and recycling options.
-
Investment and project-structuring templates (financial models, PPA/contract clauses, EPC and O&M considerations) and three representative case studies that demonstrate returns across different market and policy scenarios.
Competitive landscape — leading suppliers and recent developments
The VRB supplier ecosystem combines legacy industrial players, dedicated flow-battery specialists, and regionally focused system integrators. Market concentration is moderate: the top three firms hold roughly one-third of vendor revenue share, and the top five approach around 40% — an environment that supports scale advantages but leaves room for regional champions and differentiated technology plays.
-
Sumitomo Electric Industries (Osaka, Japan): Long-standing development history with large grid deployments and community microgrid projects. Recent product upgrades introduced in 2025 emphasize higher energy density, reduced system cost, and extended lifespan — moves aimed at improving competitiveness versus alternative chemistries.
-
Rongke Power (Dalian, China): A utility-scale player with demonstrated ability to deliver very large projects and high-cycle stacks. In January 2026 Rongke commissioned a landmark 200 MW / 1 GWh project co-located with a major solar farm — a material proof point for VRB’s role in renewable firming at utility scale.
-
Invinity Energy Systems (London, UK): Focused on modular systems with long lifespans and safety advantages; strong fit for multi-hour grid services and commercial deployments where guaranteed cycle life and zero fire risk are procurement priorities.
-
VRB Energy (Vancouver, Canada): Developer of Gen3 utility/C&I systems that secured material capital in 2024 and advanced UL safety certification — positioning itself for North American deployments.
-
CellCube (Enerox), H2 Inc., Thorion Energy, and Prudent Energy: Regional and technical specialists offering differentiated stacks, modular designs, or market-focused go-to-market approaches (mining, remote microgrids, industrial). Buyers should map supplier capabilities against use-case-specific KPIs rather than rely on brand alone.
Strategic moves for corporates and investors in 2026
-
Lock in electrolyte supply or invest in recycling capabilities: Given electrolyte cost concentration, firms should evaluate long-term offtake, tolling arrangements, or downstream recycling partnerships to hedge raw-material risk.
-
Leverage policy windows: Projects that can certify for tax credits and storage incentives in 2026 will see substantially faster payback. Structure procurement and project timelines to capture these benefits where eligible.
-
Prioritize contractual clarity on system degradation and cycle warranties: With multi-decade life claims from vendors, contracts must align payment and performance milestones to measurable degradation metrics and replacement clauses.
-
Choose technology fit by service stack: For long-duration renewable firming and transmission deferral, prioritize designs optimized for high-duration E/P ratios and lifecycle cost efficiency; for C&I use cases, modularity and footprint may dominate.
-
Prepare for supply-chain compliance: For projects targeting EU or similarly regulated markets, embed supply-chain due-diligence and traceability early to avoid disqualification or costly remediation later.
-
Consider staged manufacturing commitments: Investors should evaluate hybrid approaches — contract manufacturing to validate demand, then phased CAPEX to secure scale economies once offtake visibility is established.
How PW Consulting supports your 2026 playbook
-
Deep-dive consulting engagements: site-specific techno-economic modeling, tender support, and vendor negotiation assistance.
-
Custom scenario analysis using our interactive forecast: stress-test your balance sheet under alternative vanadium price curves, policy regimes, and technology learning rates.
-
Due-diligence and supplier audits: supply-chain mapping, compliance checklists for major regulatory frameworks, and electrolyte provenance verification protocols.
-
Investment advisory and deal structuring: from commercial contracts to JV frameworks for local manufacturing or electrolyte recycling initiatives.
Next steps: This preview intentionally surfaces directionally decisive intelligence while withholding granular regional and application splits that are core to procurement and site-level investment decisions. The full PW Consulting Vanadium Redox Battery (VRB) Market report contains the complete segmented tables, vendor scorecards, and the native financial model (base year 2025; forecast 2026–2032) clients need to operationalize these insights. For teams planning capital commitments, procurement cycles, or M&A in 2026, timely access to those details will materially improve execution certainty.
Contact PW Consulting to receive the full report, the interactive forecast model, and a tailored briefing that maps the research to your specific strategic questions for 2026.
For detailed analysis of this topic, please visit the official page: Vanadium Redox Battery (VRB) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: CBD Oil Market Set to Reach USD 3,985M by 2032 (12.03% CAGR)
By pmarketresearch, 2026-07-13
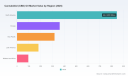
Strategic Preview: Cannabidiol (CBD) Oil Market — What 2026 Decision-Makers Need to Know
Executive summary
As PW Consulting's lead industry analyst, I present a concise strategic briefing designed to orient executive teams and investment committees ahead of the 2026 planning cycle. The Cannabidiol (CBD) oil market is in a sustained expansion phase: using 2025 as the base year, our market model projects a mid-double-digit multiple expansion through the 2026–2032 forecast window driven by a compound annual growth rate of 12.03%. This trajectory reflects both accelerating adoption across wellness, pharmaceutical-adjacent use cases and continued premiumization of formulations and delivery systems.
Cannabidiol (CBD) Oil Market
This preview demonstrates the type of evidence-based, actionable intelligence contained in our full market study. We deliberately withhold granular segment-level figures in this article; clients who require the underlying tables, region- and application-level demand curves, and scenario-model outputs should access the full report via the PW Consulting portal.
Cannabidiol (CBD) Oil Market
Why the market matters for 2026 decisions
-
Strategic inflection: By 2026, the CBD oil market is moving from fragmented early-adopter channels into a phase where regulatory signals, supply dynamics and technology-driven product differentiation will determine winners and losers. Boards should treat 2026 as the year to convert exploratory initiatives into concrete market positions.
Cannabidiol (CBD) Oil Market -
High-growth, concentrated arena: While growth remains robust, market concentration is meaningful — the top three players account for a dominant share and the top five an even larger portion. This concentration creates both defensive risks for smaller players and acquisition opportunities for mid-sized firms seeking scale.
-
Margin and quality pressure: Premiumization and clinical-quality positioning are placing upward pressure on compliance, traceability and manufacturing investments. Firms that invest early in GMP-equivalent capabilities and validated delivery technologies will capture a larger share of premium margins.
Macro trajectory and what it implies
Using a 2025 base, our macro model forecasts steady, compounding expansion through 2032. The implied growth path is consistent with an industry transitioning from nascent consumer experimentation to scaled commercial channels — especially where clinical endorsement, optimized bioavailability and trusted supply chains exist. For 2026 planning, the implication is clear: allocate resources to initiatives that accelerate trust (third-party validation, clinical evidence, supply transparency) and to architectures that enable rapid scaling (contract manufacturing partnerships, vertically integrated sourcing, or selective M&A).
Regulatory and raw-material dynamics — the operational tailwinds and headwinds
-
Regulatory friction: A stream of policy developments between 2024 and 2026 has introduced greater regulatory complexity. Recent federal-level actions have narrowed definitional boundaries for hemp and delayed certain testing enforcement timelines. These changes create both supply risk and short-term arbitrage opportunities for firms that can demonstrate rigorous compliance.
-
Food and veterinary limits: Key agencies maintain conservative stances on the use of hemp-derived cannabinoids in food, supplements, and animal feed, imposing constraints on route-to-market for ingestible products. Companies targeting mainstream packaged-food channels must plan for extended regulatory timelines and workstreams to secure approvals and liability protections.
-
Input-price volatility: Biomass-price indices moved meaningfully higher in the 12 months leading up to mid-2025. This input-cost inflation, combined with quality-driven sourcing demands, means that margin modeling requires scenario analysis that explicitly captures raw-material price shocks and quality-premium acquisition strategies.
-
GRAS navigation: Certain hemp seed derivatives retain established Generally Recognized As Safe (GRAS) pathways for food use, which some manufacturers are leveraging to broaden product portfolios. However, CBD-specific approvals remain constrained, altering portfolio prioritization for firms seeking broad consumer distribution.
Competitive landscape — profiles and strategic implications
The CBD oil competitive set spans purpose-built CBD specialists to legacy cannabis operators branching into wellness. Below I summarize the positioning and strategic signals of core players covered in our full analysis:
-
ENDOCA — Premium oil and extract specialist; strong brand emphasis on purity and formulation transparency. Strategic posture: differentiated high-margin SKUs and selective channel focus to preserve premium positioning.
-
Cannoid, LLC — Focus on full- and broad-spectrum offerings; appeals to consumers seeking holistic profiles. Strategic posture: product breadth and formulation expertise, with opportunity to push into adjacent categories.
-
Medical Marijuana, Inc. — Positions products toward nutraceutical and pharmaceutical-grade segments; leverages scientific validation. Strategic posture: move up the value chain via clinical partnerships and B2B supply agreements.
-
Folium Biosciences — High-purity therapeutic oils; supply and manufacturing capabilities are core strengths. Strategic posture: vertical integration and white-label partnerships to monetize capacity.
-
Canopy Growth Corporation , The Cronos Group , Aurora Cannabis , Tilray Brands — Large-scale cannabis players with capital, distribution and R&D depth; these firms are positioned to accelerate clinical and wellness playbooks, and in several cases are adopting advanced delivery technologies.
-
Elixinol , NuLeaf Naturals , Isodiol , PharmaHemp , CV Sciences — Specialists in full-spectrum, organic and science-backed formulations. Strategic posture: target consumers seeking traceable, organic or clinically-oriented products and capitalize on loyalty and premium pricing.
Notable recent moves underscore strategic themes: a major entrant launched a certified-organic CBD line targeting holistic wellness, while another announced a proprietary nano-emulsification system promising materially higher bioavailability. These developments illustrate the dual axes of premiumization — certification/ingredient quality and delivery-technology differentiation.
What our full report contains — practical, decision-ready modules
-
Comprehensive market model (2020–2032) with base-year validation and scenario outputs for three regulatory pathways — conservative, baseline, and permissive. Note: we present high-resolution demand curves by channel and application in the full report; here we summarize only the macro trajectory.
-
Prioritized go-to-market playbooks for incumbent brands, new entrants, and contract manufacturers, including SKU rationalization, channel sequencing and promotional levers tailored to 2026 constraints.
-
Regulatory tracker and risk heat map aligned to product types, geographies and distribution channels — with explicit mitigations and templated compliance clauses for commercial contracts.
-
Supply-chain and cost-to-serve diagnostics: upstream sourcing options, toll-manufacturing benchmarks, and contingency plans for biomass price stress scenarios.
-
Competitive dossiers: strategic profiles, capability matrices, recent M&A and technology-adoption signals for the leading firms in the space.
2026 tactical playbook — prioritized actions for executive teams
-
Accelerate compliance-grade capacity: Convert pilot GMP lines to full-scale, third-party audited production if you plan to pursue pharmaceutical or clinical adjacencies. The ability to demonstrate validated traceability will be a gating factor for premium channel entry.
-
Pursue targeted M&A or strategic partnerships to close capability gaps — especially in delivery technologies (e.g., nano-emulsion platforms) and clinical validation pathways. Pay premiums for assets that reduce time-to-market in regulated channels.
-
Lock in diversified biomass supply with layered contracts: short-term spot exposure and longer-term, quality-linked off-take agreements to hedge input-cost volatility and preserve formulation standards.
-
Design a regulatory-contingent product roadmap: prioritize SKUs that can be scaled under multiple regulatory outcomes and defer high-risk product introductions until clarity improves.
-
Invest in consumer education and clinical data: differentiated claims backed by validated studies accelerate adoption in wellness and medical-adjacent audiences and deter competitors reliant solely on brand marketing.
Risk register — what keeps boards awake
-
Regulatory reversals or narrowing definitions that restrict product formulations or distribution channels.
-
Input-price inflation and supply bottlenecks that compress margins or force reformulation.
-
Rapid technology shifts (e.g., validated delivery systems) that can render incumbent formulations less competitive without fresh investment.
-
Market consolidation among leading players, increasing barriers for independents and raising acquisition premiums.
What to do next — how to use this intelligence in 2026 planning
For 2026 corporate planning cycles, treat CBD strategy not as a single-project exercise but as a portfolio of bets across technology, compliance and channel-development. Prioritize investments that (a) secure compliant, high-quality supply, (b) capture premium bioavailability or formulation advantages, and (c) reduce time-to-scale into clinical and mainstream retail channels.
PW Consulting’s full report provides the granular inputs, sensitivity tables and competitor scorecards necessary to convert these priorities into executable budgets, KPIs and M&A targets. This preview is intended to frame the strategic landscape and the urgency of decisions; the full dataset and playbooks are available through our client portal for teams preparing capital plans, product roadmaps or M&A pipelines in 2026.
Final note
The CBD oil market presents a compelling growth story with clear winners emerging for firms that unify product integrity, regulatory discipline and technological advantage. Our research demonstrates that, while growth is substantial and sustained, regulatory and supply dynamics will disproportionately reward disciplined operators. For organizations ready to convert strategy into action in 2026, the critical next step is to access the full PW Consulting dossier — where you will find the tables, regional and application splits, and tactical tools that underpin the strategic guidance summarized here.
For detailed analysis of this topic, please visit the official page: Cannabidiol (CBD) Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: LPG Cylinder Market — USD 227M in 2025, to USD 326.19M by 2032 (5.5% CAGR)
By pmarketresearch, 2026-07-13
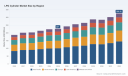
LPG Cylinder Market — 2026 Strategic Preview
As PW Consulting’s lead industry analyst, I present a forward-looking briefing designed to equip executives, investors, procurement leaders and policy teams with the high-level strategic implications of our newly completed LPG Cylinder Market study (base year 2025). The global market has grown from an estimated USD 187.5 Million in 2020 to USD 227.0 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 5.5% across the 2026–2032 forecast window, reaching an estimated USD 326.19 Million by 2032. This briefing synthesizes the macro trajectory, structural dynamics, competitive moves and near-term scenarios that should inform critical decisions in 2026—while intentionally reserving the full segment-level datasets and tactical scorecards for subscribers of the full report.
LPG Cylinder Market
Why this research matters for 2026 decision-makers
-
Timing capital allocation: The market’s steady mid-single-digit CAGR signals an environment where selectively timed investments—capacity additions, modernization of production lines, or strategic acquisitions—can yield outsized returns if aligned with regulatory and trade trajectories.
LPG Cylinder Market -
Procurement and supply security: Shifts in trade policy and supplier footprints are reshaping risk profiles. Procurement teams must balance cost, compliance and continuity; the full report includes supplier-criticality maps and hedging playbooks that operationalize this tradeoff.
LPG Cylinder Market -
Product portfolio decisions: Technological shifts—from traditional steel cylinders to higher-value composite alternatives—and segment-specific demand patterns alter product mixes and margin profiles. Our analysis quantifies the revenue and margin impact under alternate adoption curves.
-
M&A and partnership targeting: Market concentration metrics indicate room for consolidation by regional champions and technology incumbents. The study identifies priority targets and integration archetypes for 2026-active acquirers.
Market dynamics and structural drivers
The LPG cylinder market is simultaneously mature in its core residential applications and dynamic at the edges: alternative fuel transport, leisure and decentralized energy solutions. Demand growth is underpinned by population and urbanization trends in emerging markets, as well as by retrofit and safety upgrade cycles in more developed markets.
On the supply side, three interlocking forces are reshaping competitive economics:
-
Manufacturing scale and localization: Large producers are pursuing capacity scale and regional plant footprints to reduce logistics costs, comply with local regulations, and shorten order lead times. Recent facility launches and export-capable factories in Africa and other regions are evidence of this strategy.
-
Material and technology mix: Steel remains the dominant raw material and cost driver for traditional cylinders, while composite cylinders—offering weight, safety and lifecycle advantages—are expanding in specific use cases. The industry will bifurcate on cost-sensitive steel volumes and higher-margin composite niches.
-
Trade policy and regulatory friction: Duty regimes and safety certification regimes materially influence where cylinders are manufactured and sold. A notable example in the recent policy environment is the continued application of antidumping and countervailing duties on certain imports—this shapes sourcing, cost pass-through and supplier strategy.
Taken together, these dynamics favor players that can combine certified manufacturing capability, nimble geographic presence and product portfolio breadth. Market concentration data indicate a fragmented landscape with significant opportunity for scale and differentiation: the largest three firms account for a modest share of market revenues while the top five expand that share further, underscoring a marketplace where regional leaders coexist with global specialized suppliers.
Competitive landscape — who to watch and why
The competitive map is composed of several distinct cohorts: high-volume Chinese manufacturers with aggressive export strategies; established Western and regional producers focused on diversified end markets; and composite specialists advancing higher-value product propositions.
-
Large-scale Chinese manufacturers: Several manufacturers from China operate high-throughput, automated lines and export-ready factories. These firms are notable for scale-driven cost competitiveness, broad certification portfolios (ISO, DOT, CE), and increasingly globalized footprints, including manufacturing or service presence in Africa. Recent public activity includes trade show participation and responses to trade inquiries—signals indicating both export intent and an active engagement with regulatory processes.
-
Automated and high-capacity producers: Some manufacturers highlight continuous automatic production capabilities and multi-million-piece annual throughput. For buyers, these suppliers promise short lead-times and volume discounts; for competitors, they represent a force for consolidation in high-volume channels.
-
Composite-cylinder specialists and Western manufacturers: European and North American players focus on composite technologies and diversified application segments (residential, leisure, commercial). These suppliers tend to command premium pricing, invest in product differentiation, and pursue certified niche markets where weight, safety and lifecycle considerations justify higher unit economics.
-
Regional champions: Producers headquartered in Asia, the Middle East and Latin America remain critical for market access, local compliance, and last-mile distribution. Their strategic value increases when trade barriers elevate landed costs from distant suppliers.
Recent industry developments reinforce these dynamics: facility launches in Southern Africa underscore regional localization strategies; participation in regional LPG expositions signals intensified export and market-development focus; and regulatory rulings on antidumping duties have hardened the commercial calculus around cross-border sourcing.
Strategic implications and scenario planning for 2026
We recommend executive teams frame 2026 strategy around three plausible scenarios—baseline, protectionist, and accelerated-innovation—and run discrete actions against each.
-
Baseline (CAGR ~5.5%): Continue measured expansion with emphasis on operational excellence. Tactics: invest in capacity utilization improvements, deploy targeted product upgrades, and negotiate multi-year supply agreements to stabilize input costs.
-
Protectionist / trade-disrupted: If duty regimes remain or intensify, landed cost dynamics will favor local manufacturing and regional suppliers. Tactics: accelerate localization or toll-manufacturing partnerships, renegotiate price adjustments, and prioritize suppliers with local certification and on-shore production.
-
Accelerated composite adoption: If composite cylinder adoption accelerates due to regulatory incentives or consumer preference, producers with composite capabilities will capture higher-margin segments. Tactics: invest in composite R&D, form licensing partnerships, or acquire niche composite manufacturers to secure IP and channel access.
Across all scenarios, the following actions are high-value in 2026:
-
Develop a supplier segmentation and dual-sourcing plan that distinguishes strategic partners from transactional vendors, incorporating compliance, delivery performance and geopolitical risk.
-
Stress-test pricing models against raw material volatility and duty scenarios; embed indexation clauses in contracts where feasible.
-
Pursue targeted investments in production automation and certification to shorten the time-to-market for compliance-driven opportunities.
-
Evaluate M&A opportunities that either deepen regional presence or add differentiated product lines (e.g., composite technologies or integrated cylinder-valve assemblies).
What the full PW Consulting report delivers (practical components)
To convert strategic intent into executable plans, the full report provides an integrated toolkit tailored for 2026 action:
-
Granular market sizing and historical reconstruction (2020–2025) and forecast modeling (2026–2032), with scenario-sensitive revenue curves and unit-volume projections.
-
Comprehensive segmentation by type, capacity and application, accompanied by demand drivers, margin archetypes and pricing benchmarks (note: detailed segment tables are in the full report).
-
Supplier and competitor dossiers with certifications, plant footprints, production-line capabilities and publicly disclosed capacities—each scored across strategic relevance, financial health and geo-risk.
-
Trade-policy impact models that quantify landed-cost shock under alternative duty structures and suggest procurement hedges.
-
Operational playbooks: CAPEX comparators, unit-cost breakdowns, OEE improvement roadmaps, and a customizable supplier-tiering template for procurement teams.
-
M&A and partnership screening matrices, including synergy estimates and integration risk checklists for targets across regions and technology types.
-
An executive dashboard summarizing the five highest-impact decisions a leadership team should consider within the next 12 months, prioritized by ROI and implementation lead time.
Closing — how to use this preview
This briefing outlines the strategic contours of the LPG cylinder market as of 2025 and highlights the levers that will matter most through 2026. If your 2026 planning cycle involves capacity investments, supplier restructuring, or M&A activity, the full PW Consulting study contains the critical datasets, supplier scorecards and scenario models you will need to move from strategy to execution. The public snapshot above demonstrates the analytical depth we apply while intentionally reserving detailed subsegment tables and supplier rankings for report subscribers—these are the assets that materially shorten decision cycles and reduce execution risk.
For teams preparing board materials, investment memos, or procurement strategies in 2026, aligning actions to the market scenarios summarized here will materially improve the probability of hitting targets under uncertain trade and material-cost conditions.
For detailed analysis of this topic, please visit the official page: LPG Cylinder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Candle Market — 2026 Strategic Outlook (Introductory Brief)
Executive summary
The global candle market is entering 2026 from a position of steady expansion and structural change. Our base-year reference is 2025, when the market reached approximately USD 898.0 million. Under a mid-case growth trajectory, the market is projected to grow at a compound annual growth rate (CAGR) of roughly 7.06% across the 2026–2032 forecast window, reaching an estimated USD 1.45 billion by 2032. For executives and investors making portfolio, sourcing, and channel decisions this year, these headline numbers quantify more than an expanding addressable market — they flag an inflection zone where supply-chain volatility, product premiumization, and sustainability-driven differentiation converge to reshape competitive advantage.
Candle Market
Why this research matters for 2026 decision cycles
- Timing of strategic moves: A multi-year CAGR above 7% creates a window for investment that still preserves option value; firms that commit to the right capacity, contract terms, or brand partnerships in early 2026 can capture outsized share as consumer demand evolves.
- Risk calibration: The same growth path masks asymmetric downside from raw-material and trade-policy shocks. Boards that treat topline expansion as a given — without integrating tariff- and commodity-driven scenarios — risk margin compression.
- Resource allocation: Tactical choices in manufacturing footprint, private-label versus branded focus, and R&D into plant-based or beeswax formulations are high-leverage items. The full report translates growth percentages into revenue ranges by strategic pathway so leadership teams can prioritize investments with ROI horizons of 12–36 months.
Market trajectory — what the headline numbers tell us
The market grew from a mid‑single‑hundred million base in 2020 to roughly USD 898.0 million in 2025, reflecting steady consumer spending on home fragrance and ritual building. Our forecast envelope — driven by unit demand, price mix, and premium SKU introductions — supports a continuation of healthy growth through 2032 with the report’s base-case CAGR of 7.06%. Practically, this trajectory implies that incremental revenue pools are meaningful to both specialist manufacturers and multisector consumer-goods players seeking margin expansion through brand or category adjacencies.
Candle Market
Structural forces shaping 2026 strategy
- Supply‑chain and trade dynamics: Tariff actions in 2025 created repeated cost adjustments for container imports and jar components, introducing procurement complexity for producers that rely on cross-border glass and metal supplies. Volatility in such inputs compresses short-term margins and shifts negotiating leverage toward suppliers with diversified sourcing.
- Raw‑material volatility: Soybean price swings in 2025, driven by trade policy changes, materially affected soy‑wax cost assumptions. For manufacturers using plant-based waxes, 2026 procurement strategy must include hedging, alternative sourcing pools, or formula redesigns to protect gross margin.
- Consumer premiumization and ritualization: New luxury sub-brands, design collaborations, and higher SKU sophistication indicate a bifurcation: premium lifestyle and experience-led candles vs. value and private‑label offerings. This creates different go‑to‑market playbooks and margin expectations.
- Sustainability as performance enabler: Demand for biodegradable, plant‑based, and natural-wax solutions is not only a brand differentiator but increasingly a commercial necessity as retail partners demand traceability and compliance documentation.
What’s inside the full report — practical, transaction‑ready deliverables
PW Consulting’s Candle Market study is structured as an action toolkit for decision-makers. The presentation available on our site includes:
Candle Market
- Market-sizing methodology and a downloadable model (2020–2032) with scenario toggles for price, packaging cost, and trade-policy impacts.
- Segment and channel maps with growth vectors and an innovation heatmap identifying high‑momentum SKUs (premium decorative, sustainable cores, and convenience formats).
- Supplier and OEM landscape with capability matrices, quality certifications, and suggested sourcing rationales for contract manufacturing partners.
- Competitive scorecards for the leading players, including brand positioning, capacity footprints, and recent strategic moves to inform M&A, JV, or OEM decisions.
- Commercial playbooks for private‑label vs. direct‑to‑consumer strategies, including pricing guidelines, promotional cadence, and packaging optimization checklists.
- Regulatory and policy scenarios with quantified P&L sensitivity runs for tariff and raw‑material shocks that materially affect 2026 budgets.
Competitive landscape — who matters and why
The market shows moderate concentration: roughly one-quarter of the market is captured by the top three firms, and the top-five approach roughly 30%. This structure creates space for specialist contract manufacturers, regional incumbents, and new hybrid entrants that combine design, DTC distribution, and supply-chain control.
- Alene Candles (Milford, NH): An established contract manufacturer producing high volumes for private‑label and branded retail, their scale in paraffin and soy processing gives them cost advantage for national roll‑outs. For retailers seeking to outsource high-volume SKU families, Alene is a near-term strategic counterparty.
- The Yankee Candle Company (South Deerfield, MA): A textbook premium branded player with wide SKU breadth and recent luxury sub-brand activity. Their product innovation and marketing muscle make them an aspirational benchmark for margin expansion via premiumization.
- Newell Brands (Atlanta, GA): As a diversified platform with brand ownership and distribution reach, Newell acts both as consolidator and channel amplifier. Their portfolio strategy demonstrates how candles can be used to extend household assortments.
- Candles Scandinavia AB (Örebro, Sweden): A leader in plant-based, biodegradable formulations — valuable as sustainability becomes a procurement requirement in many retail chains.
- Fontana Candle Co. (Lancaster, PA): A family-owned natural‑wax specialist scaling U.S. manufacturing; expansion plans position them to capture demand for premium natural SKUs.
- Contract Candles & Diffusers Ltd (UK): A hand‑poured luxury contract manufacturer with ISO-level quality controls — attractive to high-end brands requiring small-batch artisanship with certification.
- Napa Home & Garden (Duluth, GA): Notable for product innovation: their Candle Sand brand introduces a plant-based granule system enabling custom, vessel-agnostic candle creation — an example of category adjacencies that unlock new purchase occasions.
Recent strategic moves — what to read as signals
- Premium sub-brand launches and design collaborations (examples include luxury collections and Salone del Mobile presentations) signal that incumbents are monetizing experiential and design-led demand.
- Manufacturing expansions announced by natural‑wax specialists indicate private‑label and natural‑ingredient demand is large enough to support additional capacity investments.
- Novel product concepts that lower barriers to customization (e.g., granule-and-wick systems) are early indicators of adjacent market creation that can siphon demand from traditional jar candles over a multi-year horizon.
Strategic implications and actionable recommendations for 2026
- Prioritize flexible sourcing: Lock in multi-origin supply agreements for critical inputs (glass, wicks, plant-based waxes) and build contingency inventory for jar-heavy SKUs. Negotiate clauses that share tariff risk where possible.
- Segment the portfolio by margin and risk: Allocate capex to premium, brand-led SKUs with higher gross margins while treating low-margin commoditized SKUs as operationally lean private‑label plays.
- Invest in sustainability credentials: Certifications, traceability, and clear ingredient communication materially increase buyer access to premium retail channels and reduce compliance friction.
- Use contract manufacturing strategically: For entrants and retailers, engage with a mix of high‑volume OEMs and artisan contract partners to balance cost and differentiation without overinvesting in proprietary capacity.
- Monitor policy levers continuously: Establish a simple regulatory dashboard that converts tariff or soybean price moves into P&L exposures; update procurement and promotional plans quarterly.
- Explore collaboration pathways: Consider licensing, design partnerships, or limited-edition collaborations to enter premium segments quickly while testing price elasticity and brand resonance.
How PW Consulting’s deliverables support 2026 execution
Our research is designed to convert the macro growth implied by a mid‑single‑digit CAGR into transaction-ready insight. The full deliverable includes a downloadable financial model, supplier contact map, SKU-level innovation prioritization, and a step-by-step checklist for executing a 12-to-24-month expansion or defense plan. Those elements turn strategic intent into measurable milestones: procurement savings, margin protection targets, and go-to-market timelines.
Next step — where to get the full intelligence
This brief outlines the strategic contours and supporting evidence that will matter in 2026. For executives ready to operationalize these insights — including the full segmentation tables, regional and channel breakdowns, SKU-by-SKU price and cost sensitivity matrices, and our detailed competitive scorecards — please access the complete Candle Market report on the PW Consulting site. The full package is intentionally comprehensive: think scenario-ready models, supplier shortlists, and an M&A playbook sized to the market’s concentration dynamics.
PW Consulting — we translate market growth into executable strategy so leaders can act with confidence in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Candle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Astaxanthin (CAS 472-61-7): Strategic Market Outlook — A PW Consulting Industry Briefing for 2026 Decision-Makers
Introduction — Why astaxanthin matters to corporate strategy in 2026
Astaxanthin has graduated from a niche antioxidant to a strategically significant ingredient across nutraceuticals, feed, food & beverage, and personal care. Our market model, calibrated to a 2025 base year, shows the global astaxanthin market expanding from under USD 2 billion five years ago to a multi‑billion dollar industry today — with a projected compound annual growth rate of 10.3% through the 2026–2032 forecast window. By 2026 PW Consulting projects market value north of USD 3 billion, and by 2032 the market is modeled to exceed USD 5.5 billion.
Astaxanthin (CAS 472-61-7) Market
For corporate leaders planning investments, product roadmaps, supply-chain pivots, or M&A activity in 2026, this is a growth story with a clear price and regulatory dimension. Our objective in this briefing is to translate those macro realities into the practical considerations that should shape near‑term decisions, while reserving the granular segment datasets for the full report.
Astaxanthin (CAS 472-61-7) Market
How this research creates strategic value for 2026 planning
-
Capital allocation: Rapid top‑line growth and persistent margin pressure from feedstock costs make the astaxanthin supply chain a capital‑intensive play. Understanding the implied capacity needs and cost curves in 2026 is essential for timing greenfield projects, debottlenecking existing plants, or evaluating acquisition targets.
Astaxanthin (CAS 472-61-7) Market -
Procurement and hedging: Natural astaxanthin is a commodity with wide price dispersion. Our market intelligence synthesizes production cost bands and realized market prices to support procurement strategies and pass‑through mechanisms that protect gross margin.
-
Regulatory risk management: Evolving EU rules and novel‑food opinions are changing the compliance and market access landscape. Companies must align product specifications, labeling strategies, and dossiers to anticipated 2026 regulatory expectations to avoid market exclusion or costly reformulation.
-
Product and route‑to‑market selection: The ingredient’s technical formats and claims (oil, softgel/encapsulation, dried biomass, oleoresins) affect formulation timelines, shelf life, and channel positioning. Our report links format economics to commercial pathways to accelerate launch sequences.
Market dynamics you need on your radar
-
Demand momentum: The market’s high single‑digit to low double‑digit CAGR reflects broadening consumer demand for clinically supported antioxidants, coupled with sustained uptake in aquaculture and functional foods. This is not ephemeral; the structural drivers — ageing populations, preventive health trends, and premiumisation in pet and aquaculture feeds — underpin the forecasted expansion to the mid‑2030s.
-
Supply heterogeneity: Production methods vary by supplier: closed tubular photobioreactors, indoor controlled bioreactors, open ponds, and hybrid systems. These platforms deliver different cost, quality, and scalability trade‑offs. Our analysis maps these trade‑offs to competitive positioning and margin potential.
-
Price and cost landscape: Industry benchmarks show natural astaxanthin production costs spanning a meaningful range depending on location and cultivation method, while market prices exhibit even wider dispersion. That delta creates arbitrage opportunities but also a source of volatility for formulators and downstream brands.
-
Regulatory developments: Recent regulatory actions in Europe, including updates to maximum usage levels and novel‑food assessments for algal meal containing astaxanthin, materially influence product strategies for the EU market. Firms with compliant supply chains and dossier readiness will enjoy first‑mover access to incremental demand.
-
Concentration and competition: The market is moderately concentrated, with leading producers commanding substantial share while a long tail of regional suppliers serves local feed and industrial needs. This structure encourages both partnership models and vertical integration as competitive responses.
Competitive landscape — who matters and why
The competitive set combines specialist algal producers, large ingredient houses, and regional chemical suppliers. Several archetypes emerge:
-
Technology‑led specialists: Companies operating closed photobioreactors or advanced indoor bioreactors emphasize product purity, traceability, and premium positioning. Their playbook is built on clinical substantiation, certification (e.g., Novel Food, finished‑product dossiers), and premium pricing.
-
Scale and vertical integrators: Firms that control farming, extraction, formulation, and packaging in a concentrated geography can compress lead times and achieve backward cost synergies. Recent capacity investments by large integrators illustrate the strategic value of owning the value chain end‑to‑end.
-
Commoditised suppliers: Producers using open ponds or chemical synthesis primarily compete on price and volume, servicing feed and industrial segments where cost thresholds dominate.
Representative companies include producers who epitomize each archetype — from technology‑intensive indoor and closed‑system producers to large vertically integrated groups, to suppliers offering multiple purity grades and formats. PW Consulting’s competitive profiles evaluate each on capabilities such as cultivation platform, extraction technology, clinical evidence base, product formats, and market access. We also track strategic moves: capacity additions, R&D expansion, certification achievements, and go‑to‑market partnerships.
Case in point — strategic signals from recent industry moves
-
Capacity expansion and vertical integration: Public reports of major capacity expansions and the consolidation of farming, extraction and R&D within single sites are examples of how leading producers are responding to both demand growth and the need to control quality and cost.
-
Regulatory platforming: Firms that secure Novel Food clearances and documentation ahead of regulatory changes gain preferential access to regulated markets and can command premium placement in retail and healthcare channels.
-
Evidence‑based differentiation: Producers with a robust portfolio of clinical studies or biosafety certifications are positioned to lead in supplements and therapeutic adjacencies where claims and substantiation matter.
What PW Consulting’s full report contains (practical and actionable)
-
Proprietary demand model and forecast: A transparent, bottom‑up model covering 2020–2025 historicals and 2026–2032 scenarios. The base case aligns with the 10.3% CAGR and the multi‑billion dollar trajectory noted above. (Note: detailed sub‑segment tables and regional splits are available in the full report.)
-
Supplier scorecards: Operational and commercial KPIs for active producers — cultivation methods, extraction routes, format capabilities, certification status, and capacity timelines.
-
Cost‑to‑serve and price sensitivity analysis: Cost benchmarks, break‑even maps by cultivation technology, and scenario testing under different raw material price and regulatory cost regimes.
-
Regulatory tracker and impact matrix: A timeline of recent and anticipated regulatory actions, with commercial implications mapped by market and application.
-
M&A and partnership playbook: A prioritized list of acquisition, JV and partnership targets, plus valuation heuristics and integration risk checklists suitable for private equity and corporate M&A teams.
-
Go‑to‑market strategies: Channel segmentation, product formulation recommendations, and commercialization roadmaps for fast‑moving consumer health brands, aquaculture feed players, and ingredient distributors.
How to translate the analysis into 2026 decisions — tactical recommendations
-
Align supply commitments with scenario‑based demand: Use the report’s scenarios to set staged procurement contracts or call‑off frameworks rather than fixed long‑term off‑takers that lock in exposure to upstream price swings.
-
Prioritise certification and dossier readiness for EU access: The combination of amended EU usage limits and novel‑food assessments makes early dossier investment a differentiator for market share in Europe.
-
Targeted capex vs. buy: For firms seeking scale, evaluate bolt‑on acquisitions of regional producers that provide immediate capacity and local regulatory know‑how versus greenfield projects whose payback may stretch under volatile price conditions.
-
Product format strategy: Match format selection to claim and channel. Premium supplements and medical claims favor high‑purity, clinically validated extracts; high‑volume feed uses tolerate lower‑cost formats and open‑pond‑derived material.
-
Price architecture and premiumisation: Build tiered pricing and formulation strategies that protect margins — reserve premium pricing for clinically substantiated SKUs while creating cost‑competitive blends for volume channels.
Limitations and the value of the full dataset
This briefing is designed to surface the strategic implications of the market’s macro trajectory and competitive dynamics. To execute decisions that require transactional specificity — supplier scorecards, regional application volumes, unit economics by format, and confidential deal comparables — stakeholders will need the full dataset and modeling workbook available in the full PW Consulting report. That material contains the detailed segmentations, supplier financial proxies, and downloadable scenario models we intentionally do not disclose in this preview.
Final note — timing and next steps
2026 presents a pivotal planning window. Investors and operators who act now to secure compliant, cost‑effective supply; who align product development with regulatory timelines; and who calibrate capacity exposure to demand scenarios will capture disproportionate value as the market scales. PW Consulting’s full Astaxanthin (CAS 472‑61‑7) Market report equips executive teams with the granular intelligence and decision tools required to operationalize these strategies. For teams ready to translate this strategic view into executable plans — supplier DD, acquisition screening, or formulation roadmaps — the complete report and our custom advisory engagements deliver the next layer of actionable detail.
For detailed analysis of this topic, please visit the official page: Astaxanthin (CAS 472-61-7) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Human Hair Extensions, USD 5,360M in 2025, 10.75% CAGR to 2032
By pmarketresearch, 2026-07-13
Human Hair Extension Market — Strategic Outlook for 2026 Decisions
PW Consulting’s latest market study on Human Hair Extensions provides senior executives and growth-focused investors with an actionable line of sight into a category that has transitioned from niche salon services to a global consumer and wholesale market shaping downstream beauty ecosystems. This briefing outlines the strategic value of the full report for decisions in 2026, highlights the macro dynamics that will determine winners and losers, and previews the practical playbook contained in our research — while intentionally reserving granular segment tables and segmented forecasts for the full report.
Human Hair Extension Market
Why this market matters in 2026
-
Size and momentum: The human hair extension market has more than doubled in less than a decade, rising from a multi‑billion dollar base in 2020 to an estimated USD 5,360 Million in our 2025 base year. Under our central scenario the category is forecast to continue robust growth across 2026–2032 at a compound annual growth rate (CAGR) of 10.75%, with the market approaching USD 10,970 Million by 2032.
Human Hair Extension Market -
Structural consolidation yet fragmentation: Market concentration metrics indicate a sector where leading players retain meaningful share (top‑three and top‑five concentration are material), but sizable whitespace exists for scale specialists, private‑label manufacturers, and digitally native brands to carve differentiated positions.
Human Hair Extension Market -
Strategic inflection points: 2025–2026 is a pivotal window for recalibrating supply chains, pricing models, and channel strategies because of concurrent regulatory, trade, and sustainability shifts that materially affect cost bases and brand equity.
Top‑line dynamics you must model in 2026
-
Supply and raw‑material concentration: India remains the dominant origin for Remy and temple‑sourced hair, supplying a large share of premium raw material globally. At the same time, Vietnam has emerged as an important manufacturing and consolidation hub that feeds North American and European markets with factory‑grade volumes and private‑label opportunities.
-
Trade policy shock risk: Recent tariff actions in the United States (initial 20% tariffs introduced in March 2025, with significantly higher measures applied to certain origins subsequently) introduce asymmetric cost pressure — particularly on imports from China, which experienced sharply higher punitive rates. These developments mandate scenario planning: pricing pass‑through, sourcing pivot to tariff‑advantaged suppliers, and reshoring/nearshoring options.
-
Product and service innovation: New systems and product lines (e.g., lightweight solutions for fine hair, advanced bonding technologies) introduced in 2025 are raising consumer expectations for comfort, longevity, and natural appearance. Salon protocols are evolving alongside product innovation, creating differentiated value for brands that align product R&D with service partner training.
-
Sustainability and packaging: Leading premium brands are already delivering measurable waste reductions through packaging redesigns (one high‑profile example reported a 24% reduction in packaging waste after transitioning to fully biodegradable options). Sustainability credentials are becoming table stakes for premium positioning and institutional buyers.
Practical implications for 2026 corporate strategy
-
Supply‑chain diversification is urgent. Companies should stress‑test supply portfolios across India, Vietnam, and alternative origins, build flexible contracts with tier‑one suppliers, and plan contingency inventory buffers for tariff shocks.
-
Price architecture and margin protection. With raw material and tariff volatility, firms must adopt dynamic pricing frameworks, contract hedges where available, and segmented margin management across private‑label, salon‑exclusive, and DTC channels.
-
Channel playbooks. The category rewards hybrid models: salon‑exclusive high‑touch services for premium margins; DTC and retail bundles for scale and direct consumer data; and B2B wholesale for volume and private‑label growth. Strategic partnerships or minority investments in salon networks can accelerate distribution and brand fidelity.
-
M&A and consolidation. Given the concentration metrics, acquisitive roll‑ups of regional players, private‑label factories, or specialty R&D firms will remain viable strategies to secure raw material, manufacturing, or channel control.
-
Product differentiation through tech and services. Investment in lightweight systems, advanced bonding techniques, and salon training programs can create durable competitive moats if coupled with IP protection and go‑to‑market exclusivity.
-
Sustainability as a commercial lever. Quantifiable sustainability interventions (e.g., biodegradable packaging; traceability of temple‑sourced hair) should be prioritized not only for compliance and ESG reporting but as premium marketing claims that convert buyers in key segments.
What the PW Consulting report delivers — a practical inventory
-
Bottom‑up market sizing (2020–2025 historicals; 2026–2032 forecasts) with scenario analysis and sensitivity to tariff and raw‑material shocks.
-
Channel and route‑to‑market playbooks, including profitability matrices for salon‑exclusive, retail, DTC bundle, and wholesale/private‑label models.
-
Supplier ecosystem mapping and a factory‑tier assessment to evaluate quality, capacity, compliance, and lead‑time risks.
-
Regulatory and trade impact assessment, including modelling of recent tariff actions and mitigation options for importers and manufacturers.
-
Go‑to‑market digital strategies and direct‑to‑consumer growth levers, with conversion metrics and benchmark acquisition economics for 2025–2026.
-
Sustainability playbooks: packaging redesign, traceability systems, and comms frameworks that translate ESG into price premium capture.
-
M&A and partnership pipeline analysis with valuation multiples, integration risks, and value‑creation levers tailored to strategic acquirers.
-
Competitive intelligence dossiers on leading firms, plus an anonymized benchmarking matrix for product, price, and channel positioning.
Competitive landscape — strategic profiles and implications
Our competitive analysis synthesizes public disclosures, sector intelligence, and recent product activity to distil positioning, route‑to‑market orthodoxies, and strategic options for each player. The report includes full profiles and recommended plays for the following representative companies:
-
Great Lengths — a salon‑exclusive premium player focused on ethically sourced Remy hair and high‑end service channels. Their recent product development emphasizes lightweight systems targeting fine hair, a response to changing consumer comfort expectations.
-
Mayvenn — a venture‑backed model that scales through bundles and ready‑to‑wear styles, operating at the intersection of retail and DTC volume playbooks.
-
Indique Hair — premium virgin collections leveraging temple‑sourced supply chains; brand equity is rooted in origin storytelling and high‑quality virgin product lines.
-
Perfect Locks — stylist and professional channel specialist with focus on Remy-based weft, tape‑in, and fusion methodologies, emphasizing B2B relationships and service training.
-
HALY HAIR and K‑Hair — Vietnam‑based manufacturers optimized for wholesale, private‑label, and export; these suppliers matter to any cost‑sensitive scaling strategy.
-
Alice Hair Products — China‑based supplier targeting professional salon orders with custom capabilities; relevant for firms seeking rapid turnarounds and bespoke assortments.
Beyond these profiles, our dossier captures recent product launches and industry moves across 2025 — including advanced bonding systems and biodergradable packaging initiatives — and translates them into competitive implications for market entrants and incumbents alike.
Risk framework and decision triggers for 2026
-
Tariff escalation threshold: identify the import duty level at which retail pricing elasticity will force significant volume shifts to alternative origins or domestic manufacturing. The 2025 tariff sequence demonstrates how rapidly cost structures can change.
-
Raw‑material concentration trigger: monitor single‑origin dependence for Remy supplies; an operational trigger should be set to move to multi‑origin contracts when single‑vendor share exceeds a pre‑defined threshold.
-
Sustainability compliance trigger: major customers and retailers will enforce packaging and traceability requirements; readiness for these demands should be a gating criterion for new contract wins in premium channels.
-
M&A runway trigger: use concentration and margin compression scenarios to define the threshold at which bolt‑on acquisitions become more accretive than organic investment in capacity or R&D.
How to use the report in your 2026 planning cycle
-
Executive briefings: extract the scenario tables and supplier risk matrices to brief boards and investment committees with clear downside outcomes and mitigation pathways.
-
Commercial planning: adapt the channel profitability models to set pricing corridors and promotional budgets for the first half of 2026.
-
M&A diligence: use our supplier mapping, margin archetypes, and concentration analytics to prioritize targets and structure contingent consideration aligned to tariff and raw‑material sensitivities.
-
Product roadmap alignment: prioritize R&D projects that materially improve user comfort, reduce service time, or lower manufacturing complexity — these yield the highest ROI under our demand scenarios.
Next steps — accessing the full intelligence
This introduction is designed as a strategic “trailer”: we reveal the macro runway, the top risks, and the playbook, while reserving detailed regional/type/application splits, competitor share matrices, and the full scenario tables for subscribers to the complete PW Consulting report. The full analysis contains the granular datasets, excel model, and implementation checklists that senior leaders will need to operationalize 2026 plays across procurement, pricing, and go‑to‑market execution.
For boards, corporate strategy teams, private equity investors, and C‑level executives preparing 2026 budgets and M&A pipelines, the full report is the decision‑grade asset that converts category insight into executable plans. Contact PW Consulting to obtain the full dossier, the quantitative models, and a tailored briefing for your leadership team.
For detailed analysis of this topic, please visit the official page: Human Hair Extension Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Workwear Market to Reach USD 127,140M by 2032 at 5.0% CAGR
By pmarketresearch, 2026-07-13
Workwear & Uniforms Market: Strategic Imperatives for 2026
As organizations recalibrate procurement, risk, and go-to-market strategies in 2026, the workwear and uniforms sector demands renewed executive attention. PW Consulting’s latest market study—grounded in five years of historical analysis and a seven-year forecast—translates industry dynamics into decision-ready intelligence. The global market, which stood at roughly USD 90.5 billion in our 2025 base year, is set to expand at a steady compound annual growth rate of about 5.0% through the 2026–2032 forecast window, reaching an estimated USD 127.1 billion by 2032. This brief distills the strategic value of that research for commercial, procurement, and operational leaders while preserving the granular segmentation and datasets that subscribers will find in the full report.
Workwear and Uniforms Market
Market snapshot and trajectory
Between 2020 and 2025 the market demonstrated resilient volume and value expansion driven by a mix of regulatory tightening, rising workplace safety standards, and shifts in employer-provided clothing models (rental, subscription, and managed services). Post-2025 growth is expected to be sustained by: ongoing professionalization of safety apparel, adoption of technical textiles for comfort and protection, the growing role of outsourced uniform programs, and corporate ESG commitments that push suppliers toward sustainable fibers and circular-service offerings.
Workwear and Uniforms Market
- Macro momentum: With a 5% CAGR projected across the forecast period, the sector offers predictable baseline growth suitable for capex planning and multi-year supplier contracts.
- Structural accelerants: Regulatory uplifts in uniform allowances and minimum wage shifts create both demand and cost pressure, influencing contract design and pricing strategies.
- Volatility vectors: Trade policy and tariff changes introduced in recent years have created episodic cost shocks that reverberate through sourcing and margin models.
Regulatory and cost shocks shaping 2026 decisions
Two regulatory dynamics require immediate incorporation into 2026 planning. First, new tariff frameworks adopted in 2025 materially raised short-term import costs for professional clothing—our modeling scenario bank includes instances where import-related cost pressure rises substantially, with direct pass-through and margin compression trade-offs. Second, changes to employer allowance policies and labor regulations (including regional minimum wage adjustments and uniform allowance caps) are altering the economics of supplier-managed programs versus employee reimbursement models. These shifts mean procurement and finance teams must re-run supplier TCO models under new cost regimes rather than relying on historical unit costs.
Workwear and Uniforms Market
Competitive landscape — what incumbents and challengers are doing
The market is meaningfully concentrated at the top while retaining space for regional specialists and niche innovators. Our concentration analysis indicates that the three largest incumbents command close to half of industry revenue, and the five largest capture a notable majority—reflecting an environment where scale matters for managed-service delivery, laundering logistics, and large enterprise contracts.
- Service integrators (rental & laundering): Large-scale providers emphasize network density, logistics optimization, and bundled services to lock in enterprise customers and drive recurring revenue.
- Branded manufacturers: Heritage apparel brands leverage product durability, channel relationships, and brand equity to secure specification-level preferences in industrial and trade segments.
- European and niche specialists: Players focused on high-performance workwear and PPE differentiate through product engineering, certification, and sustainability credentials.
Representative firms highlighted in our competitive profiles include established rental and service specialists; durable-workwear manufacturers with deep channel reach; and European technical apparel firms focused on high-spec applications. Each profile assesses scale, route-to-market, vertical integration, R&D capability, and service footprint—elements that determine partnership suitability or acquisition attractiveness.
What PW Consulting’s full report delivers for 2026 action plans
This study was developed to be operational from day one. Clients will receive:
- Market sizing and forward-looking forecasts by type, major application segments, and region—presented alongside interactive sensitivity models that let you test tariff shocks, wage increases, and service-penetration scenarios.
- Competitor and capability maps including supplier scorecards, service archetypes, and a five‑year strategic posture assessment for market leaders and challengers.
- Procurement-ready tools: total cost of ownership (TCO) calculators, RFP templates tailored to rental vs. buy scenarios, supplier transition playbooks, and contract clauses for pass-through and service-level protections.
- Operational diagnostics: laundromat and logistics cost benchmarks, unit economics for subscription/rental models, and capex/opex templates for in-house versus outsourced laundry capabilities.
- Sustainability and compliance frameworks: a maturity matrix for fiber sourcing, end‑of‑life strategies, and audit protocols that align with corporate ESG reporting requirements.
- Scenario planning and stress tests: pre-built scenarios that quantify impact from trade measures, allowance policy changes, and localized wage increases—enabling executives to set hedging and procurement contingencies with confidence.
- M&A and partnership playbooks: screening criteria, acquisition valuation heuristics, and integration checklists for buyers seeking scale, distribution, or technical capability.
Each module pairs quantitative outputs with pragmatic next steps—so commercial teams get not just numbers, but the playbook to convert insights into contracts, sourcing changes, and product roadmaps.
Strategic actions to prioritize in 2026
Based on our analysis, organizations should concentrate efforts across three horizons: protect, pivot, and position.
- Protect (0–90 days) : Re-run supplier TCOs with updated tariff and wage inputs; secure short-term inventory hedges where import exposure is high; apply contract clauses to protect margins from sudden cost escalation.
- Pivot (90–180 days) : Test dual-sourcing and nearshoring options for critical SKUs; pilot rental and circular-service models in high-use segments; renegotiate logistics and laundry tariffs leveraging network density or consortium buying.
- Position (180–360 days) : Invest in supplier partnerships that deliver product innovation, certification for safety/ESG credentials, and digital platforms for program management; explore M&A to consolidate regional supply chains where scale drives service economics.
Why this matters to procurement, commercial, and operations leaders
The workwear and uniforms sector sits at the intersection of labor economics, safety compliance, and corporate branding—meaning decisions here touch HR, legal, finance, and frontline operations. For procurement, the levers are cost, service continuity, and supplier risk. For commercial teams, choices on product quality, customization, and service bundling are competitive differentiators. For operations, laundry capacity, logistics agility, and supplier integration can materially affect on‑the‑ground uptime and employee satisfaction.
Our analysis demonstrates that modest changes in unit costs—driven by tariffs, wages, or input-price inflation—can materially reshape contract P&L and the relative attractiveness of capex‑heavy in-house solutions versus outsourced managed services. In short: the right mix of sourcing strategy, contractual protections, and selective investment can both protect margin and enable premium product and service propositions.
Next steps and how to access the full dataset
This brief is a strategic “trailer”: it highlights what we consider the most consequential forces shaping 2026 decisions, and it surfaces the practical instruments executives will need. The full PW Consulting workwear and uniforms market study contains the detailed regional, type, and application splits, interactive models, supplier scorecards, and downloadable procurement templates that operationalize the recommendations above.
Clients and subscribers who require expedited advisory support—scenario stress tests customized to your supplier portfolio, commercial diligence on acquisition targets, or a tailored supplier transition playbook—can engage our consulting team directly to convert the research into executable programs.
Conclusion
For 2026, the strategic imperative is clear: treat the workwear and uniforms market not as a steady commodity purchase but as a multi-dimensional sourcing and service strategy. With a predictable baseline growth trajectory and meaningful structural change driven by regulation, sustainability, and service innovation, firms that proactively adapt procurement models, invest selectively in resilience, and align product portfolios with safety and ESG demands will secure durable competitive advantage. The full PW Consulting report equips leaders with the models, tools, and tactical playbooks to do exactly that.
For detailed analysis of this topic, please visit the official page: Workwear and Uniforms Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com