

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: VRB Market to Reach USD 2,050.55M by 2032 at 20.07% CAGR

Vanadium Redox Battery (VRB) Market — Strategic Preview for 2026 Decisions
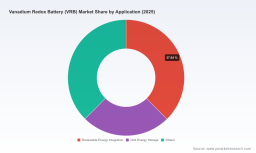
PW Consulting’s Vanadium Redox Battery (VRB) Market preview synthesizes the commercial, technological, and policy forces that will determine winners and losers through 2026 and beyond. Anchored on an independent market model (base year 2025, forecast period 2026–2032), the VRB market is accelerating: our topline model shows a compound annual growth rate (CAGR) of 20.07% across the forecast horizon and a market trajectory from the mid-hundreds of USD million in 2025 to multi-billion scale by 2032. This preview highlights the strategic implications of that growth for corporates, investors, and policymakers while intentionally withholding detailed regional and application splits — readers are invited to consult the full PW Consulting report for the underlying segment tables, interactive models, and primary-source evidence.
Vanadium Redox Battery (VRB) Market
Why this research matters for 2026 decision-makers
-
Capital allocation: The rapid expansion implied by a ~20% CAGR demands early clarity on system-level economics (capex, opex, energy-to-power sizing). Projects approved in 2026 will compete on lifetime cost curves that shift materially as vanadium pricing and policy incentives evolve.
Vanadium Redox Battery (VRB) Market -
Procurement and contracting: Buyers must balance stack suppliers’ roadmaps, electrolyte supply security, and warranty regimes — decisions that lock-in exposure for a decade or more.
Vanadium Redox Battery (VRB) Market -
Supply chain resilience: With the vanadium electrolyte representing a dominant portion of manufacturing cost, procurement strategy (vertical integration, recycling, offtake) becomes a core risk-management lever.
-
Regulatory alignment: Policy signals in 2025–2026 (tax credits, LDES incentives, and battery supply-chain rules) materially change effective project economics and buyer eligibility.
-
Competitive positioning: Active players are scaling projects from utility-grade GWh deployments to community microgrids; discerning partners and M&A targets in 2026 will gain a multi-year advantage.
Topline market dynamics — what is driving the runway
-
Rapid capacity scaling: The market’s growth curve reflects both large utility-scale commissions and an expanding set of commercial & industrial and community use cases where long-duration, non-flammable storage is preferred.
-
Electrolyte cost sensitivity: Vanadium electrolyte is the single-largest cost item in system BOMs — literature and our sector analysis converge on an estimate that ranges from roughly one-third to over one-half of manufacturing cost in typical 1 MW class systems. That concentration creates a direct transmission of vanadium price and production-cost volatility into levelized storage costs.
-
Policy tailwinds and headwinds: The expansion of investment tax credits for standalone storage (e.g., a 30% ITC in some jurisdictions) effectively reduces upfront capital by nearly one-third for eligible projects, supercharging project IRR calculations. Conversely, stricter battery supply-chain due diligence (notably EU battery regulation in force from 2024) imposes compliance costs and sourcing constraints that can disadvantage suppliers reliant on conflict-affected or opaque supply chains.
-
Demand-pull for long-duration services: Governments and system operators are increasingly procuring multi-hour capacity products and renewable integration services. Incentives and procurement frameworks for long-duration energy storage are a primary demand vector supporting VRB adoption.
-
Manufacturing economics and labor: Production cost sensitivity to energy-to-power ratios (E/P) and labor intensity rises with certain design choices; our models show that production costs can increase materially at higher duration configurations, reinforcing the need for design optimization and scale economies.
What the PW Consulting report delivers — practical, actionable contents
-
Proprietary market model (base year 2025, forecast 2026–2032) with scenario toggles: policy sensitivity, vanadium price paths, and technology learning curves. The model is delivered in an interactive spreadsheet so clients can stress-test assumptions for capital planning.
-
Cost and margin breakdowns by system architecture, lifecycle cost curves, and a procurement playbook that translates BOM exposure into contract clauses and hedging strategies.
-
Vendor benchmarking and technology scorecards that assess cycle life, depth-of-discharge, efficiency, modularity, and safety certifications — enabling RFP shortlists aligned to specific use cases (utility, C&I, microgrid).
-
Supply-chain maps and due-diligence checklists tailored to regulatory regimes (e.g., US tax incentives and EU battery sourcing rules), plus practical workflows for securing electrolyte supply and recycling options.
-
Investment and project-structuring templates (financial models, PPA/contract clauses, EPC and O&M considerations) and three representative case studies that demonstrate returns across different market and policy scenarios.
Competitive landscape — leading suppliers and recent developments
The VRB supplier ecosystem combines legacy industrial players, dedicated flow-battery specialists, and regionally focused system integrators. Market concentration is moderate: the top three firms hold roughly one-third of vendor revenue share, and the top five approach around 40% — an environment that supports scale advantages but leaves room for regional champions and differentiated technology plays.
-
Sumitomo Electric Industries (Osaka, Japan): Long-standing development history with large grid deployments and community microgrid projects. Recent product upgrades introduced in 2025 emphasize higher energy density, reduced system cost, and extended lifespan — moves aimed at improving competitiveness versus alternative chemistries.
-
Rongke Power (Dalian, China): A utility-scale player with demonstrated ability to deliver very large projects and high-cycle stacks. In January 2026 Rongke commissioned a landmark 200 MW / 1 GWh project co-located with a major solar farm — a material proof point for VRB’s role in renewable firming at utility scale.
-
Invinity Energy Systems (London, UK): Focused on modular systems with long lifespans and safety advantages; strong fit for multi-hour grid services and commercial deployments where guaranteed cycle life and zero fire risk are procurement priorities.
-
VRB Energy (Vancouver, Canada): Developer of Gen3 utility/C&I systems that secured material capital in 2024 and advanced UL safety certification — positioning itself for North American deployments.
-
CellCube (Enerox), H2 Inc., Thorion Energy, and Prudent Energy: Regional and technical specialists offering differentiated stacks, modular designs, or market-focused go-to-market approaches (mining, remote microgrids, industrial). Buyers should map supplier capabilities against use-case-specific KPIs rather than rely on brand alone.
Strategic moves for corporates and investors in 2026
-
Lock in electrolyte supply or invest in recycling capabilities: Given electrolyte cost concentration, firms should evaluate long-term offtake, tolling arrangements, or downstream recycling partnerships to hedge raw-material risk.
-
Leverage policy windows: Projects that can certify for tax credits and storage incentives in 2026 will see substantially faster payback. Structure procurement and project timelines to capture these benefits where eligible.
-
Prioritize contractual clarity on system degradation and cycle warranties: With multi-decade life claims from vendors, contracts must align payment and performance milestones to measurable degradation metrics and replacement clauses.
-
Choose technology fit by service stack: For long-duration renewable firming and transmission deferral, prioritize designs optimized for high-duration E/P ratios and lifecycle cost efficiency; for C&I use cases, modularity and footprint may dominate.
-
Prepare for supply-chain compliance: For projects targeting EU or similarly regulated markets, embed supply-chain due-diligence and traceability early to avoid disqualification or costly remediation later.
-
Consider staged manufacturing commitments: Investors should evaluate hybrid approaches — contract manufacturing to validate demand, then phased CAPEX to secure scale economies once offtake visibility is established.
How PW Consulting supports your 2026 playbook
-
Deep-dive consulting engagements: site-specific techno-economic modeling, tender support, and vendor negotiation assistance.
-
Custom scenario analysis using our interactive forecast: stress-test your balance sheet under alternative vanadium price curves, policy regimes, and technology learning rates.
-
Due-diligence and supplier audits: supply-chain mapping, compliance checklists for major regulatory frameworks, and electrolyte provenance verification protocols.
-
Investment advisory and deal structuring: from commercial contracts to JV frameworks for local manufacturing or electrolyte recycling initiatives.
Next steps: This preview intentionally surfaces directionally decisive intelligence while withholding granular regional and application splits that are core to procurement and site-level investment decisions. The full PW Consulting Vanadium Redox Battery (VRB) Market report contains the complete segmented tables, vendor scorecards, and the native financial model (base year 2025; forecast 2026–2032) clients need to operationalize these insights. For teams planning capital commitments, procurement cycles, or M&A in 2026, timely access to those details will materially improve execution certainty.
Contact PW Consulting to receive the full report, the interactive forecast model, and a tailored briefing that maps the research to your specific strategic questions for 2026.
For detailed analysis of this topic, please visit the official page: Vanadium Redox Battery (VRB) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com