

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Workwear Market to Reach USD 127,140M by 2032 at 5.0% CAGR

Workwear & Uniforms Market: Strategic Imperatives for 2026
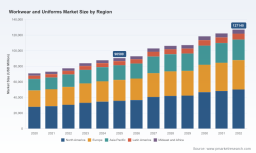
As organizations recalibrate procurement, risk, and go-to-market strategies in 2026, the workwear and uniforms sector demands renewed executive attention. PW Consulting’s latest market study—grounded in five years of historical analysis and a seven-year forecast—translates industry dynamics into decision-ready intelligence. The global market, which stood at roughly USD 90.5 billion in our 2025 base year, is set to expand at a steady compound annual growth rate of about 5.0% through the 2026–2032 forecast window, reaching an estimated USD 127.1 billion by 2032. This brief distills the strategic value of that research for commercial, procurement, and operational leaders while preserving the granular segmentation and datasets that subscribers will find in the full report.
Workwear and Uniforms Market
Market snapshot and trajectory
Between 2020 and 2025 the market demonstrated resilient volume and value expansion driven by a mix of regulatory tightening, rising workplace safety standards, and shifts in employer-provided clothing models (rental, subscription, and managed services). Post-2025 growth is expected to be sustained by: ongoing professionalization of safety apparel, adoption of technical textiles for comfort and protection, the growing role of outsourced uniform programs, and corporate ESG commitments that push suppliers toward sustainable fibers and circular-service offerings.
Workwear and Uniforms Market
- Macro momentum: With a 5% CAGR projected across the forecast period, the sector offers predictable baseline growth suitable for capex planning and multi-year supplier contracts.
- Structural accelerants: Regulatory uplifts in uniform allowances and minimum wage shifts create both demand and cost pressure, influencing contract design and pricing strategies.
- Volatility vectors: Trade policy and tariff changes introduced in recent years have created episodic cost shocks that reverberate through sourcing and margin models.
Regulatory and cost shocks shaping 2026 decisions
Two regulatory dynamics require immediate incorporation into 2026 planning. First, new tariff frameworks adopted in 2025 materially raised short-term import costs for professional clothing—our modeling scenario bank includes instances where import-related cost pressure rises substantially, with direct pass-through and margin compression trade-offs. Second, changes to employer allowance policies and labor regulations (including regional minimum wage adjustments and uniform allowance caps) are altering the economics of supplier-managed programs versus employee reimbursement models. These shifts mean procurement and finance teams must re-run supplier TCO models under new cost regimes rather than relying on historical unit costs.
Workwear and Uniforms Market
Competitive landscape — what incumbents and challengers are doing
The market is meaningfully concentrated at the top while retaining space for regional specialists and niche innovators. Our concentration analysis indicates that the three largest incumbents command close to half of industry revenue, and the five largest capture a notable majority—reflecting an environment where scale matters for managed-service delivery, laundering logistics, and large enterprise contracts.
- Service integrators (rental & laundering): Large-scale providers emphasize network density, logistics optimization, and bundled services to lock in enterprise customers and drive recurring revenue.
- Branded manufacturers: Heritage apparel brands leverage product durability, channel relationships, and brand equity to secure specification-level preferences in industrial and trade segments.
- European and niche specialists: Players focused on high-performance workwear and PPE differentiate through product engineering, certification, and sustainability credentials.
Representative firms highlighted in our competitive profiles include established rental and service specialists; durable-workwear manufacturers with deep channel reach; and European technical apparel firms focused on high-spec applications. Each profile assesses scale, route-to-market, vertical integration, R&D capability, and service footprint—elements that determine partnership suitability or acquisition attractiveness.
What PW Consulting’s full report delivers for 2026 action plans
This study was developed to be operational from day one. Clients will receive:
- Market sizing and forward-looking forecasts by type, major application segments, and region—presented alongside interactive sensitivity models that let you test tariff shocks, wage increases, and service-penetration scenarios.
- Competitor and capability maps including supplier scorecards, service archetypes, and a five‑year strategic posture assessment for market leaders and challengers.
- Procurement-ready tools: total cost of ownership (TCO) calculators, RFP templates tailored to rental vs. buy scenarios, supplier transition playbooks, and contract clauses for pass-through and service-level protections.
- Operational diagnostics: laundromat and logistics cost benchmarks, unit economics for subscription/rental models, and capex/opex templates for in-house versus outsourced laundry capabilities.
- Sustainability and compliance frameworks: a maturity matrix for fiber sourcing, end‑of‑life strategies, and audit protocols that align with corporate ESG reporting requirements.
- Scenario planning and stress tests: pre-built scenarios that quantify impact from trade measures, allowance policy changes, and localized wage increases—enabling executives to set hedging and procurement contingencies with confidence.
- M&A and partnership playbooks: screening criteria, acquisition valuation heuristics, and integration checklists for buyers seeking scale, distribution, or technical capability.
Each module pairs quantitative outputs with pragmatic next steps—so commercial teams get not just numbers, but the playbook to convert insights into contracts, sourcing changes, and product roadmaps.
Strategic actions to prioritize in 2026
Based on our analysis, organizations should concentrate efforts across three horizons: protect, pivot, and position.
- Protect (0–90 days) : Re-run supplier TCOs with updated tariff and wage inputs; secure short-term inventory hedges where import exposure is high; apply contract clauses to protect margins from sudden cost escalation.
- Pivot (90–180 days) : Test dual-sourcing and nearshoring options for critical SKUs; pilot rental and circular-service models in high-use segments; renegotiate logistics and laundry tariffs leveraging network density or consortium buying.
- Position (180–360 days) : Invest in supplier partnerships that deliver product innovation, certification for safety/ESG credentials, and digital platforms for program management; explore M&A to consolidate regional supply chains where scale drives service economics.
Why this matters to procurement, commercial, and operations leaders
The workwear and uniforms sector sits at the intersection of labor economics, safety compliance, and corporate branding—meaning decisions here touch HR, legal, finance, and frontline operations. For procurement, the levers are cost, service continuity, and supplier risk. For commercial teams, choices on product quality, customization, and service bundling are competitive differentiators. For operations, laundry capacity, logistics agility, and supplier integration can materially affect on‑the‑ground uptime and employee satisfaction.
Our analysis demonstrates that modest changes in unit costs—driven by tariffs, wages, or input-price inflation—can materially reshape contract P&L and the relative attractiveness of capex‑heavy in-house solutions versus outsourced managed services. In short: the right mix of sourcing strategy, contractual protections, and selective investment can both protect margin and enable premium product and service propositions.
Next steps and how to access the full dataset
This brief is a strategic “trailer”: it highlights what we consider the most consequential forces shaping 2026 decisions, and it surfaces the practical instruments executives will need. The full PW Consulting workwear and uniforms market study contains the detailed regional, type, and application splits, interactive models, supplier scorecards, and downloadable procurement templates that operationalize the recommendations above.
Clients and subscribers who require expedited advisory support—scenario stress tests customized to your supplier portfolio, commercial diligence on acquisition targets, or a tailored supplier transition playbook—can engage our consulting team directly to convert the research into executable programs.
Conclusion
For 2026, the strategic imperative is clear: treat the workwear and uniforms market not as a steady commodity purchase but as a multi-dimensional sourcing and service strategy. With a predictable baseline growth trajectory and meaningful structural change driven by regulation, sustainability, and service innovation, firms that proactively adapt procurement models, invest selectively in resilience, and align product portfolios with safety and ESG demands will secure durable competitive advantage. The full PW Consulting report equips leaders with the models, tools, and tactical playbooks to do exactly that.
For detailed analysis of this topic, please visit the official page: Workwear and Uniforms Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com