

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Astaxanthin Market Poised for 10.3% CAGR Through 2032

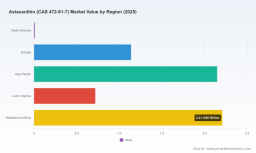
Astaxanthin (CAS 472-61-7): Strategic Market Outlook — A PW Consulting Industry Briefing for 2026 Decision-Makers
Introduction — Why astaxanthin matters to corporate strategy in 2026
Astaxanthin has graduated from a niche antioxidant to a strategically significant ingredient across nutraceuticals, feed, food & beverage, and personal care. Our market model, calibrated to a 2025 base year, shows the global astaxanthin market expanding from under USD 2 billion five years ago to a multi‑billion dollar industry today — with a projected compound annual growth rate of 10.3% through the 2026–2032 forecast window. By 2026 PW Consulting projects market value north of USD 3 billion, and by 2032 the market is modeled to exceed USD 5.5 billion.
Astaxanthin (CAS 472-61-7) Market
For corporate leaders planning investments, product roadmaps, supply-chain pivots, or M&A activity in 2026, this is a growth story with a clear price and regulatory dimension. Our objective in this briefing is to translate those macro realities into the practical considerations that should shape near‑term decisions, while reserving the granular segment datasets for the full report.
Astaxanthin (CAS 472-61-7) Market
How this research creates strategic value for 2026 planning
-
Capital allocation: Rapid top‑line growth and persistent margin pressure from feedstock costs make the astaxanthin supply chain a capital‑intensive play. Understanding the implied capacity needs and cost curves in 2026 is essential for timing greenfield projects, debottlenecking existing plants, or evaluating acquisition targets.
Astaxanthin (CAS 472-61-7) Market -
Procurement and hedging: Natural astaxanthin is a commodity with wide price dispersion. Our market intelligence synthesizes production cost bands and realized market prices to support procurement strategies and pass‑through mechanisms that protect gross margin.
-
Regulatory risk management: Evolving EU rules and novel‑food opinions are changing the compliance and market access landscape. Companies must align product specifications, labeling strategies, and dossiers to anticipated 2026 regulatory expectations to avoid market exclusion or costly reformulation.
-
Product and route‑to‑market selection: The ingredient’s technical formats and claims (oil, softgel/encapsulation, dried biomass, oleoresins) affect formulation timelines, shelf life, and channel positioning. Our report links format economics to commercial pathways to accelerate launch sequences.
Market dynamics you need on your radar
-
Demand momentum: The market’s high single‑digit to low double‑digit CAGR reflects broadening consumer demand for clinically supported antioxidants, coupled with sustained uptake in aquaculture and functional foods. This is not ephemeral; the structural drivers — ageing populations, preventive health trends, and premiumisation in pet and aquaculture feeds — underpin the forecasted expansion to the mid‑2030s.
-
Supply heterogeneity: Production methods vary by supplier: closed tubular photobioreactors, indoor controlled bioreactors, open ponds, and hybrid systems. These platforms deliver different cost, quality, and scalability trade‑offs. Our analysis maps these trade‑offs to competitive positioning and margin potential.
-
Price and cost landscape: Industry benchmarks show natural astaxanthin production costs spanning a meaningful range depending on location and cultivation method, while market prices exhibit even wider dispersion. That delta creates arbitrage opportunities but also a source of volatility for formulators and downstream brands.
-
Regulatory developments: Recent regulatory actions in Europe, including updates to maximum usage levels and novel‑food assessments for algal meal containing astaxanthin, materially influence product strategies for the EU market. Firms with compliant supply chains and dossier readiness will enjoy first‑mover access to incremental demand.
-
Concentration and competition: The market is moderately concentrated, with leading producers commanding substantial share while a long tail of regional suppliers serves local feed and industrial needs. This structure encourages both partnership models and vertical integration as competitive responses.
Competitive landscape — who matters and why
The competitive set combines specialist algal producers, large ingredient houses, and regional chemical suppliers. Several archetypes emerge:
-
Technology‑led specialists: Companies operating closed photobioreactors or advanced indoor bioreactors emphasize product purity, traceability, and premium positioning. Their playbook is built on clinical substantiation, certification (e.g., Novel Food, finished‑product dossiers), and premium pricing.
-
Scale and vertical integrators: Firms that control farming, extraction, formulation, and packaging in a concentrated geography can compress lead times and achieve backward cost synergies. Recent capacity investments by large integrators illustrate the strategic value of owning the value chain end‑to‑end.
-
Commoditised suppliers: Producers using open ponds or chemical synthesis primarily compete on price and volume, servicing feed and industrial segments where cost thresholds dominate.
Representative companies include producers who epitomize each archetype — from technology‑intensive indoor and closed‑system producers to large vertically integrated groups, to suppliers offering multiple purity grades and formats. PW Consulting’s competitive profiles evaluate each on capabilities such as cultivation platform, extraction technology, clinical evidence base, product formats, and market access. We also track strategic moves: capacity additions, R&D expansion, certification achievements, and go‑to‑market partnerships.
Case in point — strategic signals from recent industry moves
-
Capacity expansion and vertical integration: Public reports of major capacity expansions and the consolidation of farming, extraction and R&D within single sites are examples of how leading producers are responding to both demand growth and the need to control quality and cost.
-
Regulatory platforming: Firms that secure Novel Food clearances and documentation ahead of regulatory changes gain preferential access to regulated markets and can command premium placement in retail and healthcare channels.
-
Evidence‑based differentiation: Producers with a robust portfolio of clinical studies or biosafety certifications are positioned to lead in supplements and therapeutic adjacencies where claims and substantiation matter.
What PW Consulting’s full report contains (practical and actionable)
-
Proprietary demand model and forecast: A transparent, bottom‑up model covering 2020–2025 historicals and 2026–2032 scenarios. The base case aligns with the 10.3% CAGR and the multi‑billion dollar trajectory noted above. (Note: detailed sub‑segment tables and regional splits are available in the full report.)
-
Supplier scorecards: Operational and commercial KPIs for active producers — cultivation methods, extraction routes, format capabilities, certification status, and capacity timelines.
-
Cost‑to‑serve and price sensitivity analysis: Cost benchmarks, break‑even maps by cultivation technology, and scenario testing under different raw material price and regulatory cost regimes.
-
Regulatory tracker and impact matrix: A timeline of recent and anticipated regulatory actions, with commercial implications mapped by market and application.
-
M&A and partnership playbook: A prioritized list of acquisition, JV and partnership targets, plus valuation heuristics and integration risk checklists suitable for private equity and corporate M&A teams.
-
Go‑to‑market strategies: Channel segmentation, product formulation recommendations, and commercialization roadmaps for fast‑moving consumer health brands, aquaculture feed players, and ingredient distributors.
How to translate the analysis into 2026 decisions — tactical recommendations
-
Align supply commitments with scenario‑based demand: Use the report’s scenarios to set staged procurement contracts or call‑off frameworks rather than fixed long‑term off‑takers that lock in exposure to upstream price swings.
-
Prioritise certification and dossier readiness for EU access: The combination of amended EU usage limits and novel‑food assessments makes early dossier investment a differentiator for market share in Europe.
-
Targeted capex vs. buy: For firms seeking scale, evaluate bolt‑on acquisitions of regional producers that provide immediate capacity and local regulatory know‑how versus greenfield projects whose payback may stretch under volatile price conditions.
-
Product format strategy: Match format selection to claim and channel. Premium supplements and medical claims favor high‑purity, clinically validated extracts; high‑volume feed uses tolerate lower‑cost formats and open‑pond‑derived material.
-
Price architecture and premiumisation: Build tiered pricing and formulation strategies that protect margins — reserve premium pricing for clinically substantiated SKUs while creating cost‑competitive blends for volume channels.
Limitations and the value of the full dataset
This briefing is designed to surface the strategic implications of the market’s macro trajectory and competitive dynamics. To execute decisions that require transactional specificity — supplier scorecards, regional application volumes, unit economics by format, and confidential deal comparables — stakeholders will need the full dataset and modeling workbook available in the full PW Consulting report. That material contains the detailed segmentations, supplier financial proxies, and downloadable scenario models we intentionally do not disclose in this preview.
Final note — timing and next steps
2026 presents a pivotal planning window. Investors and operators who act now to secure compliant, cost‑effective supply; who align product development with regulatory timelines; and who calibrate capacity exposure to demand scenarios will capture disproportionate value as the market scales. PW Consulting’s full Astaxanthin (CAS 472‑61‑7) Market report equips executive teams with the granular intelligence and decision tools required to operationalize these strategies. For teams ready to translate this strategic view into executable plans — supplier DD, acquisition screening, or formulation roadmaps — the complete report and our custom advisory engagements deliver the next layer of actionable detail.
For detailed analysis of this topic, please visit the official page: Astaxanthin (CAS 472-61-7) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com