

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: LPG Cylinder Market — USD 227M in 2025, to USD 326.19M by 2032 (5.5% CAGR)

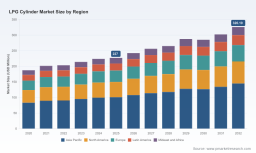
LPG Cylinder Market — 2026 Strategic Preview
As PW Consulting’s lead industry analyst, I present a forward-looking briefing designed to equip executives, investors, procurement leaders and policy teams with the high-level strategic implications of our newly completed LPG Cylinder Market study (base year 2025). The global market has grown from an estimated USD 187.5 Million in 2020 to USD 227.0 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 5.5% across the 2026–2032 forecast window, reaching an estimated USD 326.19 Million by 2032. This briefing synthesizes the macro trajectory, structural dynamics, competitive moves and near-term scenarios that should inform critical decisions in 2026—while intentionally reserving the full segment-level datasets and tactical scorecards for subscribers of the full report.
LPG Cylinder Market
Why this research matters for 2026 decision-makers
-
Timing capital allocation: The market’s steady mid-single-digit CAGR signals an environment where selectively timed investments—capacity additions, modernization of production lines, or strategic acquisitions—can yield outsized returns if aligned with regulatory and trade trajectories.
LPG Cylinder Market -
Procurement and supply security: Shifts in trade policy and supplier footprints are reshaping risk profiles. Procurement teams must balance cost, compliance and continuity; the full report includes supplier-criticality maps and hedging playbooks that operationalize this tradeoff.
LPG Cylinder Market -
Product portfolio decisions: Technological shifts—from traditional steel cylinders to higher-value composite alternatives—and segment-specific demand patterns alter product mixes and margin profiles. Our analysis quantifies the revenue and margin impact under alternate adoption curves.
-
M&A and partnership targeting: Market concentration metrics indicate room for consolidation by regional champions and technology incumbents. The study identifies priority targets and integration archetypes for 2026-active acquirers.
Market dynamics and structural drivers
The LPG cylinder market is simultaneously mature in its core residential applications and dynamic at the edges: alternative fuel transport, leisure and decentralized energy solutions. Demand growth is underpinned by population and urbanization trends in emerging markets, as well as by retrofit and safety upgrade cycles in more developed markets.
On the supply side, three interlocking forces are reshaping competitive economics:
-
Manufacturing scale and localization: Large producers are pursuing capacity scale and regional plant footprints to reduce logistics costs, comply with local regulations, and shorten order lead times. Recent facility launches and export-capable factories in Africa and other regions are evidence of this strategy.
-
Material and technology mix: Steel remains the dominant raw material and cost driver for traditional cylinders, while composite cylinders—offering weight, safety and lifecycle advantages—are expanding in specific use cases. The industry will bifurcate on cost-sensitive steel volumes and higher-margin composite niches.
-
Trade policy and regulatory friction: Duty regimes and safety certification regimes materially influence where cylinders are manufactured and sold. A notable example in the recent policy environment is the continued application of antidumping and countervailing duties on certain imports—this shapes sourcing, cost pass-through and supplier strategy.
Taken together, these dynamics favor players that can combine certified manufacturing capability, nimble geographic presence and product portfolio breadth. Market concentration data indicate a fragmented landscape with significant opportunity for scale and differentiation: the largest three firms account for a modest share of market revenues while the top five expand that share further, underscoring a marketplace where regional leaders coexist with global specialized suppliers.
Competitive landscape — who to watch and why
The competitive map is composed of several distinct cohorts: high-volume Chinese manufacturers with aggressive export strategies; established Western and regional producers focused on diversified end markets; and composite specialists advancing higher-value product propositions.
-
Large-scale Chinese manufacturers: Several manufacturers from China operate high-throughput, automated lines and export-ready factories. These firms are notable for scale-driven cost competitiveness, broad certification portfolios (ISO, DOT, CE), and increasingly globalized footprints, including manufacturing or service presence in Africa. Recent public activity includes trade show participation and responses to trade inquiries—signals indicating both export intent and an active engagement with regulatory processes.
-
Automated and high-capacity producers: Some manufacturers highlight continuous automatic production capabilities and multi-million-piece annual throughput. For buyers, these suppliers promise short lead-times and volume discounts; for competitors, they represent a force for consolidation in high-volume channels.
-
Composite-cylinder specialists and Western manufacturers: European and North American players focus on composite technologies and diversified application segments (residential, leisure, commercial). These suppliers tend to command premium pricing, invest in product differentiation, and pursue certified niche markets where weight, safety and lifecycle considerations justify higher unit economics.
-
Regional champions: Producers headquartered in Asia, the Middle East and Latin America remain critical for market access, local compliance, and last-mile distribution. Their strategic value increases when trade barriers elevate landed costs from distant suppliers.
Recent industry developments reinforce these dynamics: facility launches in Southern Africa underscore regional localization strategies; participation in regional LPG expositions signals intensified export and market-development focus; and regulatory rulings on antidumping duties have hardened the commercial calculus around cross-border sourcing.
Strategic implications and scenario planning for 2026
We recommend executive teams frame 2026 strategy around three plausible scenarios—baseline, protectionist, and accelerated-innovation—and run discrete actions against each.
-
Baseline (CAGR ~5.5%): Continue measured expansion with emphasis on operational excellence. Tactics: invest in capacity utilization improvements, deploy targeted product upgrades, and negotiate multi-year supply agreements to stabilize input costs.
-
Protectionist / trade-disrupted: If duty regimes remain or intensify, landed cost dynamics will favor local manufacturing and regional suppliers. Tactics: accelerate localization or toll-manufacturing partnerships, renegotiate price adjustments, and prioritize suppliers with local certification and on-shore production.
-
Accelerated composite adoption: If composite cylinder adoption accelerates due to regulatory incentives or consumer preference, producers with composite capabilities will capture higher-margin segments. Tactics: invest in composite R&D, form licensing partnerships, or acquire niche composite manufacturers to secure IP and channel access.
Across all scenarios, the following actions are high-value in 2026:
-
Develop a supplier segmentation and dual-sourcing plan that distinguishes strategic partners from transactional vendors, incorporating compliance, delivery performance and geopolitical risk.
-
Stress-test pricing models against raw material volatility and duty scenarios; embed indexation clauses in contracts where feasible.
-
Pursue targeted investments in production automation and certification to shorten the time-to-market for compliance-driven opportunities.
-
Evaluate M&A opportunities that either deepen regional presence or add differentiated product lines (e.g., composite technologies or integrated cylinder-valve assemblies).
What the full PW Consulting report delivers (practical components)
To convert strategic intent into executable plans, the full report provides an integrated toolkit tailored for 2026 action:
-
Granular market sizing and historical reconstruction (2020–2025) and forecast modeling (2026–2032), with scenario-sensitive revenue curves and unit-volume projections.
-
Comprehensive segmentation by type, capacity and application, accompanied by demand drivers, margin archetypes and pricing benchmarks (note: detailed segment tables are in the full report).
-
Supplier and competitor dossiers with certifications, plant footprints, production-line capabilities and publicly disclosed capacities—each scored across strategic relevance, financial health and geo-risk.
-
Trade-policy impact models that quantify landed-cost shock under alternative duty structures and suggest procurement hedges.
-
Operational playbooks: CAPEX comparators, unit-cost breakdowns, OEE improvement roadmaps, and a customizable supplier-tiering template for procurement teams.
-
M&A and partnership screening matrices, including synergy estimates and integration risk checklists for targets across regions and technology types.
-
An executive dashboard summarizing the five highest-impact decisions a leadership team should consider within the next 12 months, prioritized by ROI and implementation lead time.
Closing — how to use this preview
This briefing outlines the strategic contours of the LPG cylinder market as of 2025 and highlights the levers that will matter most through 2026. If your 2026 planning cycle involves capacity investments, supplier restructuring, or M&A activity, the full PW Consulting study contains the critical datasets, supplier scorecards and scenario models you will need to move from strategy to execution. The public snapshot above demonstrates the analytical depth we apply while intentionally reserving detailed subsegment tables and supplier rankings for report subscribers—these are the assets that materially shorten decision cycles and reduce execution risk.
For teams preparing board materials, investment memos, or procurement strategies in 2026, aligning actions to the market scenarios summarized here will materially improve the probability of hitting targets under uncertain trade and material-cost conditions.
For detailed analysis of this topic, please visit the official page: LPG Cylinder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com