

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Metal Injection Molding Materials to reach USD 7,623 Million by 2032 at 9.5% CAGR

Metal Injection Molding Materials Market: Strategic Briefing for 2026 Decision-Makers
Executive snapshot
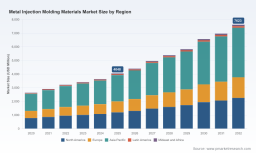
As PW Consulting’s chief industry analyst, I present a strategic primer designed to translate our Metal Injection Molding (MIM) Materials Market study into immediate, board-level action in 2026. The market has transitioned from niche engineering volumes into a structurally growing market: total industry revenues expanded from roughly USD 2.64 billion in 2020 to about USD 4.05 billion in 2025, and our forecast projects continued expansion to approximately USD 7.62 billion by 2032 at a compounded annual growth rate (CAGR) of 9.5% through the 2026–2032 horizon. Market concentration remains moderate (CR3 ~35%; CR5 ~55%), indicating a mix of established suppliers and specialist challengers—an environment ripe for strategic M&A, vertical integration, and value-chain repositioning.
Metal Injection Molding Materials Market
Why this research matters for 2026 planning
Companies facing 2026 planning cycles must move beyond conventional market-sizing and towards operational playbooks that convert growth into margin and resilience. The MIM materials market is being reshaped by three concurrent forces: accelerating end-market demand for complex, high-performance metallic components; intensifying supply-side specialization around powders and feedstocks; and non-negotiable sustainability and domestic-sourcing policies in key jurisdictions. Our report synthesizes these drivers into decision-ready frameworks—enabling executives to prioritize CAPEX, procurement strategies, partnership models, and regulatory investments with a clear view of timing and return.
Metal Injection Molding Materials Market
Key strategic implications
- Sourcing and supply resilience: Feedstock and powder availability are tactical constraints that can determine production uptime and unit economics. Senior procurement teams should treat powder suppliers not as commodity vendors but as strategic partners—locking multi-year offtakes, co-investing in qualification testing, and building alternative supply lanes to mitigate single-supplier exposure.
- Make-vs-buy recalibration: With demand growing near double digits annually, several component makers are reconsidering vertical integration into feedstock compounding or powder handling. Our scenario analyses quantify break-even horizons and sensitivity to powder pricing and feedstock yields to support capex trade-offs.
- Product and material prioritization: Not all alloys and feedstock chemistries deliver equal margin or strategic value. A prioritized material roadmap—aligned to target applications and manufacturability—reduces development costs and shortens time-to-revenue for high-value components.
- Regulatory and sustainability positioning: Stricter environmental policies in multiple markets increase the cost of non-compliance and create a premium for lower-carbon, low-waste feedstock processes. Companies that can demonstrate lifecycle advantages will gain both procurement preference and price resiliency.
Supply-chain dynamics and feedstock economics
Feedstock cost and powder availability are the operational fulcrum of MIM economics. In 2026, procurement teams will still face price volatility tied to metal powder production capacity and atomization throughput. Our study maps upstream capacity, identifies pinch-points in atomization and feedstock compounding, and models how feedstock price shocks cascade through manufacturing cost models. For strategy teams, the practical takeaway is clear: cost control in MIM is as much about securing powder continuity and quality as it is about downstream processing efficiency.
Metal Injection Molding Materials Market
Innovation and product strategy
Innovation in feedstock chemistry, debinding techniques, and additive hybrid processes is accelerating. Material selection (stainless steels, titanium alloys, copper alloys, magnetic alloys and specialty blends) remains a primary lever for differentiating performance in automotive, medical, aerospace and electronics applications. Our research identifies which material innovations are closest to commercial maturity and where investment in co-development with feedstock specialists will create defensible IP and shortened qualification cycles.
Competitive landscape—what to watch in 2026
The competitive map features global materials giants, specialized powder houses, and regional feedstock manufacturers. Leading players such as BASF and large powder specialists continue to invest in sustainable feedstock solutions and capacity expansions, while advanced powder producers and regional champions drive custom blends for niche applications. Recent industry moves—product launches focused on sustainability, site-level capacity investments, and active industry conference pipelines—signal an escalation in both product and production competition. For corporate strategists, the implications are:
- Prioritize supplier segmentation by capability (e.g., atomization technology, alloy breadth, feedstock compounding) rather than geography alone.
- Evaluate joint-development agreements with suppliers that offer co-funded qualification programs and technology transfer clauses.
- Scan for acquisition or minority-investment targets among mid-sized feedstock producers where integration can capture margin and secure supply.
Recent industry signals to incorporate into plans
Three recent developments crystallize near-term opportunities and risks: (1) established chemical and materials firms releasing new low-impact powder and feedstock lines, signaling a product premium for sustainability; (2) capacity investments by leading powder-metallurgy groups, reflecting anticipated demand for higher-purity and specialty powders; and (3) heightened industry collaboration and knowledge-exchange at technical conferences—accelerating best-practice adoption. These signals inform timing for procurement contracts, R&D alliances, and capacity investments—our report aligns each type of corporate action with an expected impact horizon (short, medium, long).
What the PW Consulting report delivers (practical contents)
This study is designed as an operational toolkit for 2026 decisions. Highlights include:
- Validated market sizing and scenario forecasts (base year 2025; forecast 2026–2032) with sensitivity to price, adoption, and regulatory variables.
- Supply-chain maps and supplier capability heatmaps to prioritize partners for qualifying programs and strategic sourcing.
- Commercial benchmarking: price bands, typical contract structures, quality KPIs and expected qualification timelines for key alloy classes.
- Operational playbooks: make-vs-buy models, CAPEX calculators, and production scale-up checklists tailored to MIM feedstocks and component facilities.
- Technology readiness assessments that rank innovations by commercialization risk and expected margin upside.
- Regulatory impact matrix linking regional policy scenarios to material choices and certification paths.
- Competitive intelligence dossiers and a transaction-ready shortlist for M&A and JV opportunities—scored by strategic fit and integration complexity.
How to use this research across your organization
Decision-use cases we designed the deliverable for:
- Strategy teams: prioritize adjacent growth moves and inorganic targets with quantified payback windows.
- Procurement: construct layered sourcing strategies, contract templates, and hedging options for powder supply.
- Operations and manufacturing: size capital investments, plan capacity ramp sequencing and optimize yield pathways.
- R&D and product teams: select alloy-development targets, structure supplier co-development agreements and compress qualification timelines.
- Investor relations and corporate development: craft growth narratives grounded in market and supplier dynamics that support valuation discussions.
Deliberate withholding: why core segmentation data is reserved
Consistent with the “trailer” principle for this briefing, we present high-confidence macro trends, forecasts, and strategic implications to establish credibility, while reserving granular segmentation matrices and proprietary supplier-level data for the full report. The deep segmentation (by region, alloy type, and application), detailed price curves and supplier scorecards are high-value assets in our product and are available in the full deliverable. Executives evaluating competitive bids, negotiating long-term feedstock contracts, or executing on cross-border capacity plans will find those datasets essential for tactical execution.
Next steps for 2026 planning
If your 2026 strategy cycle includes supply-chain resilience, product differentiation, or potential acquisitions in the MIM materials space, we recommend three immediate actions:
- Commission a 90-day supplier qualification sprint with clearly defined performance gates and co-development milestones.
- Run a targeted make-vs-buy financial model for any planned capacity investments, using conservative powder-price scenarios and the report’s CAPEX multipliers.
- Engage our M&A screening module to identify 3–5 tactical acquisition targets that can accelerate your entry into specialty feedstocks or high-value alloys.
Closing
The MIM materials market offers a rare intersection of sustained demand growth, material-led differentiation and supply-side specialization. For leaders who move decisively in 2026—aligning procurement, R&D and corporate development around validated scenarios—there is substantial upside in margin capture and strategic positioning. For access to the complete segmentation tables, supplier-level dossiers, and our decision-grade financial models, please consult the full PW Consulting Metal Injection Molding Materials Market report on our publication page.
For detailed analysis of this topic, please visit the official page: Metal Injection Molding Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com