

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Semitrailer Market to Expand at 5.6% CAGR (2026–2032)

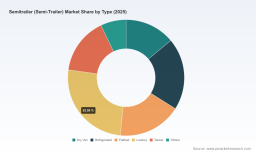
Semitrailer Market 2026: Strategic Imperatives from PW Consulting’s Market Outlook
As fleets, OEMs, suppliers and private equity investors prepare strategic plans in 2026, the semitrailer market presents a mix of steady expansion, technological disruption and input-cost volatility. PW Consulting’s latest Semitrailer Market study (base year 2025; historical coverage 2020–2025; forecast 2026–2032) synthesizes the right combination of macros, competitive benchmarking and operational toolkits that decision-makers need to convert ambiguity into decisive action. The study calculates a compound annual growth rate (CAGR) of 5.6% through the forecast window and models multiple scenarios that take the market from USD 213.0 Million in 2025 to an illustrative mid-range outcome of roughly USD 312 Million by 2032.
Semitrailer (Semi-Trailer) Market
Why this study matters for 2026 decision cycles
-
Timing of capital allocation: With fleet replacement and factory-capacity investments being long‑lived, choices made in 2026 will determine cost position and market share for much of the next decade. Our forecast and scenario modules convert macro drivers into year-by-year demand curves engineers and CFOs can plug into capex plans.
Semitrailer (Semi-Trailer) Market -
Input-cost and margin management: Raw-material volatility and trade policy have materially altered cost structures. The report quantifies the margin sensitivity of common vehicle architectures to steel and aluminum price moves and helps prioritize design choices that protect gross margins.
Semitrailer (Semi-Trailer) Market -
Regulatory and safety roadmaps: Anticipated regulatory shifts—ranging from rear-impact guard certification rules to standardization of automatic emergency braking and automated driving system guidance—require product and compliance roadmaps. The study maps plausible regulatory milestones and the required engineering and testing investments.
-
Competitive positioning: The market remains fragmented (CR3 ~24.6%, CR5 ~26.2%), so focused consolidation, differentiated product strategy, or service-led models can all succeed. Our profiles and strategic playbook specify which go-to-market models work against each competitive archetype.
Market trajectory at a glance
The semitrailer market has shown resilient expansion through the early 2020s. PW Consulting’s historical reconstruction highlights a progression from a mid‑single‑hundred million USD market in 2020 to USD 213.0 Million in 2025. Under our central scenario—reflecting baseline macro growth, continued freight demand and incremental fleet modernization—market value reaches approximately USD 311.7 Million by 2032. The 5.6% CAGR embedded in our forecast reflects moderate fleet renewal rates, continued modal demand for road freight, and increasing value per trailer as electrification, telematics and safety features become standard.
Key dynamics shaping the market
-
Raw-material inflation: Steel prices climbed strongly in 2024–2025 (industry data shows a ~21% YoY increase as of April 2025), compressing margins and prompting design re‑optimization. Manufacturers face a trade-off: maintain legacy bill-of-materials to preserve pricing parity, or accelerate lightweight-material adoption—aluminum and composites—to offset fuel and emissions advantages for customers.
-
Trade and input protection: Continued tariffs on steel and aluminum imports materially raise component costs and favor regionalized sourcing or vertical integration strategies. The report models tariff pass-through under multiple pricing regimes and offers hedging and sourcing playbooks.
-
Safety and automation regulation: U.S. regulatory authorities signaled changes to certification labeling for rear-impact guards and are moving toward standardized automatic emergency braking requirements and updated automated driving system regulations. These shifts create both compliance costs and product differentiation opportunities for early adopters.
-
Product and technological evolution: Across OEMs we identify three complementary technology vectors—lightweight structures (aluminum/composite), telematics/connectivity, and safety automation integration. Success will depend on modular architectures that allow incremental upgrades rather than full redesigns.
-
Market fragmentation and channel economics: The relatively low market concentration means national champions coexist with specialty and regional producers. Pricing power varies by segment and application; aftermarket and service contracts are an increasingly attractive margin pool.
Competitive landscape—what incumbents are doing
Our report profiles over a dozen core manufacturers and maps their strategic posture along product breadth, manufacturing scale, material strategy and go-to-market model. Highlights include:
-
Platform and material leadership: Several established OEMs are doubling down on lightweight aluminum and composite assemblies to capture total cost of ownership (TCO) benefits—improving fuel economy and complying with tighter emissions expectations.
-
Connectivity and integrated chassis solutions: Major manufacturers are embedding telematics and advanced chassis designs, creating incremental recurring-revenue opportunities through data and fleet-management services.
-
Specialist and custom builders: Companies focusing on tankers, lowbeds, heavy‑haul and forestry applications are defending niche positions through patented designs and deep aftermarket service capabilities.
-
Scale players vs. nimble innovators: High-volume producers are leveraging production economics and distribution reach, while smaller manufacturers compete on custom engineering, speed-to-market and specialty configurations.
Recent industry moves illustrate these dynamics. In April 2026, one OEM completed a high‑speed rear impact guard crash validation test, setting a new safety benchmark for rear guards and signaling product differentiation through safety validation. Earlier, in 2025, several manufacturers rolled out eco‑focused product lines to align with emissions and sustainability expectations. These developments highlight how safety certification and green credentials are becoming competitive levers.
What the report contains (practical deliverables)
-
Market sizing and high‑frequency trend tables (base year 2025; historical 2020–2025; forecast 2026–2032) with scenario sensitivity to fuel, GDP and trade shocks.
-
Scenario analytics and stress tests: upside, baseline and downside demand paths linked to fleet-replacement timing and regulatory adoption curves.
-
Supply-chain cost models capturing material, labor and logistics drivers; tariff and hedging playbooks; and break-even analyses for alternative material use (steel vs. aluminum vs. composites).
-
Competitive profiles and capability maps for the leading manufacturers, including innovation posture, channel strength and M&A targets matched to strategic objectives.
-
Commercial playbooks: pricing strategy templates, aftermarket and service monetization frameworks, and sales-channel optimization recommendations.
-
Implementation tools: a downloadable Excel model (plug-and-play) to test investment options, and a prioritized 90‑day action plan for 2026 executives.
-
Regulatory impact assessments, including compliance timelines, testing cost estimates and implications of pending agency guidance on safety and automation.
Strategic recommendations for executives (2026 priorities)
-
Hedge material exposure and regionalize sourcing: Mitigate tariff and price risk by diversifying suppliers, pursuing longer-term contracts for critical grades of steel and exploring near-shore manufacturing options where economics permit.
-
Invest selectively in lightweight architectures: Target modular designs that allow incremental conversion to aluminum/composite skins and subframes, focusing first where fuel and emissions gains yield measurable customer TCO improvements.
-
Monetize telematics: Shift from one-time hardware sales to recurring revenue through fleet analytics, uptime guarantees and predictive-maintenance services, which enhance customer stickiness and stabilize margins.
-
Prepare for safety and automation mandates: Prioritize engineering capacity for automatic emergency braking integration and validate rear‑guard designs to capture early-adopter demand and avoid retrofit costs.
-
Evaluate M&A and partnership pathways: Use M&A to acquire specialty capabilities (e.g., tankers, lowbeds, refrigerated tech) or to scale manufacturing footprints in high-growth corridors identified by our regional demand overlays.
-
Expand service networks and parts availability: With aftermarket services representing an outsized margin opportunity, invest in dealer training, parts logistics and digital spare-part channels.
-
Embed scenario planning in capital allocation: Use the report’s scenario models to stress test factory utilization and working capital under alternative demand and raw-material price trajectories before finalizing 2026–2027 capex commitments.
How to use the report in your 2026 playbook
Use the study as a living decision-support asset: integrate the model into monthly planning; run bespoke “what-if” cases for your product families; and deploy the competitor capability maps to prioritize strategic partnerships or defensive moves. For private equity and corporate development teams, the report accelerates target screening and valuation sensitivity to material-price and regulatory outcomes. For OEM product leaders, the engineering impact matrices and validation-cost estimates make explicit the trade-offs between early compliance and potential first-mover advantage.
Closing—what we’re intentionally withholding here
To honor the “preview” principle and drive value to the full study, we have deliberately withheld the granular split tables and raw segment-by-region/application dollar values in this public summary. The full PW Consulting Semitrailer Market report contains detailed segmented forecasts, unit-volume assumptions, dealer-channel economics and proprietary demand maps that translate the high-level picture above into executable plans. Subscribers and clients gain access to the downloadable models, supplier-scorecards and the complete competitive databook.
If your 2026 priorities include optimizing supply-chain resilience, positioning for regulatory change, or capturing aftermarket revenue in a market growing at ~5.6% CAGR over the next several years, this study provides the analytic backbone and the practical tools to act with confidence.
For detailed analysis of this topic, please visit the official page: Semitrailer (Semi-Trailer) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com