

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automotive Wheel Bearing Market Set for 6.5% CAGR (2026-2032)

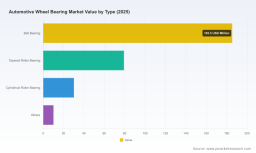
Automotive Wheel Bearing Market — A Strategic Preview for 2026 Decision-Makers
Executive summary
As OEMs, tier‑1 suppliers and aftermarket specialists plan their 2026 playbooks, understanding the trajectory of the automotive wheel bearing market is mission‑critical. PW Consulting’s latest study (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes market sizing, competitive positioning, technology inflections and regulatory drivers into an actionable intelligence set. The market is growing at a steady compound annual growth rate (CAGR) of 6.5% across the 2026–2032 forecast window, building on a 2025 baseline and reaching materially larger scale by 2032. Importantly, the market exhibits moderate concentration — the top three global players account for a clear majority of industry revenues, and the top five extend that dominance further — a structural reality that shapes pricing power, technology diffusion and M&A dynamics.
Automotive Wheel Bearing Market
Why this analysis matters for 2026 strategy
-
Product roadmap calibration: wheel bearing design is no longer a commodity decision. Integrated sensors, pre‑lubricated hub units, advanced sealing and drag‑torque optimization are differentiators for both OEM spec and aftermarket preference. Firms that align R&D and manufacturing investments to these vectors will secure specification slots and aftermarket mindshare.
Automotive Wheel Bearing Market -
Vehicle powertrain shifts: electrification is changing duty cycles and thermal characteristics of wheel bearings. While EV penetration impacts absolute unit and revenue mixes differently across segments, the technical requirements for sealing, lubrication and sensor integration are shifting — creating both risk and opportunity for incumbents and new entrants.
Automotive Wheel Bearing Market -
Supply chain resilience and raw materials: fluctuations in steel, specialty alloys and grease base stocks, combined with tighter performance and environmental standards, necessitate upstream engagement. Buyers and suppliers must revisit sourcing strategies and qualification protocols in 2026 to avoid margin erosion and disruption.
-
Aftermarket and service models: extended service intervals and predictive‑maintenance adoption change replacement patterns — an opportunity for suppliers who can bundle hardware with diagnostics, repacking services or value‑added kits.
Market dynamics — forces you cannot ignore
-
Standards and testing: ASTM D1263 remains a reference for grease leakage tendencies, a critical performance parameter for high‑speed, high‑temperature wheel bearing applications. Expect OEM and aftermarket specifiers to increasingly reference standardized test regimes when qualifying lubricants and sealed units.
-
Predictive reliability: new methodologies — notably those articulated in recent SAE research — enable life and damage forecasting using real‑time load analytics. Suppliers embedding sensing and data pipelines into hub units can move from component vendors to service partners with recurring revenue models.
-
Seal and torque engineering: academic and industry research is refining our understanding of drag torque behavior and interference optimization in assemblies. Improvements here translate directly into lower energy losses, improved NVH and longer service life — attributes that feed back into OEM vehicle efficiency targets.
-
Maintenance innovation: documented developments in grease repacking devices and maintenance tools point to a renaissance in aftermarket serviceability. Companies that support professional service channels with certified repacking and refurbishment solutions will capture incremental aftermarket share.
Competitive landscape — what the leaders are doing
The wheel bearing market is shaped by several global engineering leaders whose strategic choices set the agenda for the ecosystem. Key firms include SKF Group, Schaeffler AG (FAG), NSK Ltd., NTN Corporation, JTEKT Corporation and The Timken Company. These incumbents combine deep mechanical expertise with system‑level offerings — hub assemblies, pre‑lubricated units, integrated sensors and aftermarket kits — and are actively positioning to win both OEM and replacement business.
-
SKF Group (Gothenburg, Sweden; https://www.skf.com) leverages a strong history in hub bearing units and sensor integration. Its emphasis on pre‑lubricated units and full kits is designed to reduce failure modes while simplifying installation for OEMs and workshops.
-
Schaeffler AG (Herzogenaurach, Germany; https://www.schaeffler.com) continues to push complete hub solutions under established brand umbrellas, focusing on repairability and aftermarket kits that match OEM specifications — a lucrative play given warranty and service economics.
-
NSK Ltd. (Tokyo, Japan; https://www.nsk.com) has invested in advanced sealing and mounting technologies, addressing the thermal and geometric challenges presented by higher torque, lower‑noise applications common in modern vehicles.
-
NTN Corporation (Osaka, Japan; https://www.ntnglobal.com) develops integrated hub assemblies for passenger and light commercial vehicles with an eye to manufacturability and ease of installation, appealing to cost‑conscious OEM programs.
-
JTEKT Corporation (Osaka, Japan; https://www.jtekt.co.jp) emphasizes reliability through integrated sensor covers and robust sealing, targeting vehicle programs where long life and low maintenance are priority selling points.
-
The Timken Company (North Canton, Ohio, USA; https://www.timken.com) focuses on engineered rolling element solutions and aftermarket availability, with a reputation for performance in demanding applications.
These players collectively account for a significant share of the market (the three largest capture a majority, and the top five an even larger portion), producing a landscape where strategic collaboration, selective vertical integration and targeted acquisitions are used to defend share or enter adjacencies.
What the PW Consulting report delivers (practical, actionable contents)
Designed for strategy teams, business development leaders and M&A practitioners, the report is structured to enable immediate decision-making in 2026:
- Market sizing and forecast model (base year 2025; historical 2020–2025; forecast 2026–2032) — including sensitivity scenarios around EV adoption and servicing paradigms.
- Competitive benchmarking — capability maps for leading suppliers, product portfolios and go‑to‑market models.
- Technology heatmap — sealing, lubrication, sensor integration, and NVH/drag torque advancements, with implications for BOM and testing protocols.
- Regulatory and standards impact assessment — translating ASTM, SAE and specialist tribology findings into supplier and OEM actions.
- Supply chain risk matrix — raw material exposure, qualification lead times and contingency strategies for critical components.
- Aftermarket and service strategies — refurbishment, repacking and diagnostic service opportunities with revenue models and partner options.
- M&A and partnership playbook — target profiles, valuation approaches and integration considerations tailored to 2026 market realities.
How leading companies should act in 2026 — tactical recommendations
-
Prioritize sensorized hub platforms where lifecycle analytics create recurring revenue. The convergence of SAE‑level predictive methodologies and practical sensing hardware means early adopters can transition from one‑time component sales to subscription or service contracts.
-
Invest in validated grease formulations and sealing tech that meet standardized leakage and drag‑torque criteria. Reference to ASTM and tribology research will be a procurement differentiator for programs targeting efficiency and durability.
-
Re‑examine supply contracts for specialty alloys and grease precursors. Given the concentration of market power and potential supply disruptions, secure multi‑tier sourcing and pursue design changes that reduce dependence on high‑volatility inputs where feasible.
-
Build aftermarket ecosystems around certified repacking, refurbishment and diagnostics. This not only extends lifetime value but also preserves brand control in a market that increasingly values professional servicing.
-
Use M&A selectively to acquire sensing capabilities, advanced sealing IP or regional aftermarket distribution. The industry’s concentration profile favors bolt‑on consolidation in targeted geographies or technology niches.
Limitations of this preview and where to find the full intelligence
This article is a strategic preview designed to surface the most salient trends and recommended actions for 2026. To preserve proprietary value and to drive decisive client engagements, detailed segment tables (regional, type and application splits), company revenue breakdowns and the full-year-by-year forecast model are intentionally omitted from this summary. The full dataset — including granular segmentation, downloadable models and company scorecards — is available through PW Consulting’s full report and client portal.
Next steps
For executives preparing 2026 budgets, product roadmaps or M&A pipelines, PW Consulting can provide bespoke briefings, a workshop to stress‑test strategy against our forecast scenarios, or a carve‑out diligence pack for specific acquisition targets. Contact our automotive practice to schedule an executive session and obtain the complete data package that informs procurement, product and corporate development decisions in this increasingly strategic component market.
For detailed analysis of this topic, please visit the official page: Automotive Wheel Bearing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com