

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
XOS Market to Reach USD 97.5 Million by 2032 at 6.5% CAGR — PW Consulting

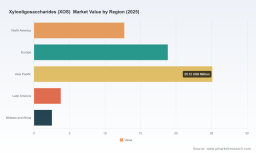
Xylooligosaccharides (XOS) Market — Strategic Imperatives for 2026
As PW Consulting’s lead industry analyst, I present a concise, decision‑focused preview of our comprehensive Xylooligosaccharides (XOS) Market study. This briefing is written to inform C‑suite and strategy teams as they define 2026 priorities: where to invest, which capabilities to accelerate, and how to approach regulatory and supply risks. The language below demonstrates the analytical depth you can expect from the full study while deliberately preserving core segmented datasets — a purposeful “trailer” designed to prompt direct access to the full intelligence package for transaction‑grade planning.
Xylooligosaccharides (XOS) Market
Market snapshot: measurable momentum and structural context
XOS has moved from a niche ingredient to a commercially meaningful category over the last half‑decade. Our model shows the global market expanded from approximately USD 50 million in 2020 to about USD 63 million in 2025, and is forecast to reach roughly USD 66.7 million in 2026 on the way to about USD 97.5 million by 2032 — driven by an average compound annual growth rate (CAGR) of 6.5% for the 2026–2032 forecast window. These headline figures reflect steady adoption across food & beverage, animal nutrition and nutraceutical channels, and they quantify an investible opportunity for vertically integrated producers, ingredient formulators, and branded product owners.
Xylooligosaccharides (XOS) Market
Market structure matters: the XOS industry exhibits moderate concentration, with the top three suppliers accounting for more than half of reported commercial supply and the top five controlling roughly two‑thirds of capacity. This concentration creates a dual dynamic: scale advantages for incumbents (cost, distribution, quality assurance) and meaningful windows for differentiated entrants that can offer unmatched purity, formulation support or regulatory readiness.
Xylooligosaccharides (XOS) Market
Why this research matters for 2026 decisions
- Investment prioritization. The 6.5% medium‑term CAGR and the proven 2020–2025 growth trajectory provide a defensible baseline for capital allocation. Investors should calibrate expansion capex and brownfield greenfield decisions to realistic volume ramp profiles we detail in the full report.
- Regulatory strategy as a competitive moat. Regulatory status is a binary gate in several markets. The United States currently benefits from GRAS acceptance for many XOS uses, while Canada has issued non‑novel determinations for certain feedstocks. In contrast, the European Union treats XOS as a novel food under Regulation (EU) 2015/2283, creating a pre‑market authorization requirement that materially affects time‑to‑market and go‑to‑market sequencing. Our study provides a practical roadmap to convert regulatory workstreams into commercial advantage.
- Supply chain and raw material playbook. XOS manufacturers commonly rely on corn cobs — a low‑cost, widely available agricultural by‑product containing high xylan content — as the primary upstream feedstock. Understanding feedstock sourcing economics, seasonal variability, and logistics is essential; the report includes a sensitivity model linking feedstock price swings to producer margins and finished‑goods pricing.
- Commercial segmentation and channel focus. Adoption dynamics differ markedly by end‑use: beverage formulators demand liquid grades and stringent solubility/clarity metrics, nutraceutical customers prioritize high‑purity powders and certified analytics, while animal nutrition buyers emphasize cost/performance and supply reliability. Our go‑to‑market playbook translates those differences into prioritized product roadmaps and channel KPIs.
Competitive landscape — what to watch in 2026
The competitive picture is dominated by a cluster of established Chinese producers alongside a few legacy developers with deep IP and long commercial track records. Leading Chinese manufacturers have scaled aggressively: several report multi‑thousand‑ton production footprints geared to dietary supplement and functional food applications, while others have recently commissioned liquid‑grade lines to address beverage demand. Japan’s Suntory remains noteworthy as the original commercial pioneer, retaining technical know‑how in enzymatic production routes and longstanding customer relationships.
- Scale and cost leadership. Major Chinese producers benefit from integrated feedstock sourcing, low manufacturing cost bases and proximity to large domestic demand pools — factors that underpin competitive pricing and rapid capacity deployment.
- Product differentiation. Market winners will be those that segment on quality and formulation support: high‑purity powders for nutraceutical brands, spray‑dried formulations for consumer goods, and beverage‑grade liquids tailored for ready‑to‑drink applications. Recent capital projects have targeted these niches, and we expect further tiering of supplier value propositions in 2026.
- Recent market development. Capacity shifts continue to occur: for example, a leading powder producer expanded liquid‑grade capacity in early 2026 to serve beverage formulators — a signal that producers are chasing higher‑value, application‑specific demand as the category matures.
Operational considerations for buyers and producers
- Feedstock management. Corn cobs are abundant and cost‑effective due to high xylan content, but buyers should insist on contracted volumes, quality specs and traceability clauses to avoid seasonal variability and quality drift. Our report contains supplier scorecards and contracting templates for feedstock offtake.
- Process selection and quality assurance. Enzymatic routes and purification stages determine product purity, degree of polymerization, and impurity profiles — attributes that directly affect allowable applications and shelf stability. We benchmark process technologies versus commercial outcomes in a dedicated technical appendix.
- Regulatory and claims strategy. For jurisdictions where XOS is novel, producers must budget for pre‑market dossiers and post‑authorization surveillance. Where GRAS status or non‑novel determinations exist, companies should still maintain strong documentation to support claims and to expedite customer adoption. The full study includes a regulatory matrix and a templated authorization timeline for each target geography.
- Quality & sustainability narratives. Buyers and brands will increasingly demand robust supply chain transparency and low‑carbon claims. Traceability from cob to capsule, and demonstrable yield improvements that reduce waste, are becoming commercial differentiators.
Go‑to‑market playbook for 2026
- Phase entry by regulatory clarity. Prioritize markets with clear and permissive regulatory regimes to establish volume and reference customers quickly; simultaneously invest in EU authorization for strategic longer‑term presence.
- Tailor product architecture. Maintain a triage of product grades: high‑purity powder for nutraceuticals, beverage‑grade liquids for formulators, and cost‑optimized grades for animal nutrition. Invest in analytics and formulation support to accelerate OEM adoption.
- Secure feedstock and manufacturing capacity. Negotiate multi‑year offtake agreements with agricultural cooperatives, and consider contract manufacturing partnerships in regions that provide logistics or regulatory advantages.
- Use M&A and JV selectively. Where market access or technical IP is the bottleneck, targeted partnerships (minority stakes, exclusives, tolling contracts) can unlock rapid scale without carrying full greenfield risk.
- Commercial risk management. Build flexible pricing clauses tied to feedstock indices, and structure supply agreements with clear quality dispute resolution pathways.
What the full PW Consulting report delivers (high‑value, operational outputs)
- Detailed demand model and scenario analysis (2020–2032) with sensitivity to feedstock and macroeconomic shocks.
- Regulatory matrix and stepwise authorization roadmaps for key markets, including estimated timelines and dossier requirements.
- Supplier scorecards and a prioritized shortlist for offtake or strategic partnership candidates, including technical capabilities and estimated commercial capacities.
- Product grade taxonomy with application match‑matrix and pricing bands, plus formulation playbooks for beverage, supplement and feed customers.
- Investment case templates, capex/opex models and payback scenarios for brownfield expansions, greenfield sites and tolling arrangements.
- M&A and partnership playbook: red flags, valuation multipliers and integration checklists specific to XOS producers and ingredient formulators.
Our preview above uses headline market sizing and structural signals to establish the commercial case for action in 2026. For teams structuring investment memoranda, negotiating supply agreements, or defining entry strategies, the full PW Consulting XOS Market report provides the granular segmentation, regional and application breakdowns, and unit‑level economics required to execute with conviction. If your 2026 strategy depends on rigorous, transaction‑grade intelligence — including the fine‑grained segmentation we intentionally withheld here — contact PW Consulting or visit our XOS Market page to access the complete dataset, modeling files and advisory engagement options.
For detailed analysis of this topic, please visit the official page: Xylooligosaccharides (XOS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com