

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Programmable Power Supply Market to Reach USD 344.8M by 2032 at 6.98% CAGR
By pmarketresearch, 2026-07-13
Programmable Power Supply Devices: Strategic Intelligence for 2026 Decision-Making
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a forward-looking synthesis of the Programmable Power Supply Device market designed to inform executive choices in 2026. This analysis combines macro growth signaling, competitive motion, regulatory and supply-side dynamics, and the practical, executable insights that senior leaders and product strategists require—without divulging the granular segmentation that is preserved for the full report.
Programmable Power Supply Device Market
Why this market matters in 2026
The programmable power supply market is no longer a niche instrumentation category: it sits at the intersection of industrial automation, battery validation, semiconductor capital equipment, and advanced test & measurement. Our industry modeling (base year 2025) shows a resilient expansion path, with the total market scaling notably through the historical period and continuing at a compound annual growth rate of 6.98% across the 2026–2032 forecast window. That trajectory reflects both rising unit complexity (multi‑function digital platforms) and stronger average selling prices where high-voltage, bidirectional, and digitally integrated supplies are required.
Programmable Power Supply Device Market
Market trajectory: what the headline numbers tell you
- Momentum: The market demonstrated steady recovery and growth through the early 2020s and reached a clear inflection by 2025. The growth profile implied in our forecasts favors technology-differentiated offerings (digital control, higher power density, bidirectionality) and sectors undertaking large-scale electrification projects.
- Outlook: Near‑term demand drivers are pragmatic—battery gigafactory validation, semiconductor fab expansions, and automotive electrification testing. Longer‑term upside is tied to increasingly software-defined test workflows and on‑site power systems for new energy infrastructures.
- Concentration: Competitive structure remains fragmented relative to classic power electronics incumbencies; the top few firms together account for a modest share of the market, leaving substantial runway for innovation, specialization, and M&A-driven consolidation.
Strategic implications for 2026 corporate decision-makers
Executives planning product roadmaps, procurement strategies, or M&A activity should treat the programmable power segment as a strategic enabler rather than a cost center. The clear implications we draw from the data are:
Programmable Power Supply Device Market
- Prioritize software and systems integration. Buyers increasingly prize platforms that integrate power control, data telemetry, and automated test sequencing. Suppliers that expose APIs and support edge-to-cloud telemetry will win larger, longer contracts.
- Differentiate on safety and standards compliance. IEC compliance and RoHS 3 alignment are table stakes for industrial and laboratory deployments; plans that bake regulatory certainty into product lifecycles see faster adoption among OEMs and test labs.
- Assess supply-chain resilience beyond commodity pricing. Raw material sourcing—especially semiconductors and key passive components—remains geographically concentrated. Strategic sourcing, multi-supplier qualification, and localized manufacturing footprints are credible hedges against disruption.
- Monitor cost‑competition while defending high-value niches. Competitive pressure from lower-cost suppliers has intensified in commodity power ranges. Western suppliers can offset margin erosion by leaning into high-voltage, high-reliability, and custom-system segments or by pursuing strategic partnerships and selective consolidation.
What our report delivers: actionable, operational intelligence
This research is crafted for executives who must convert market insight into actions in 2026. The full deliverable contains:
- Validated market sizing and trend models (historical analysis 2020–2025; forecast 2026–2032) to stress-test business plans and revenue scenarios.
- Use-case led demand matrices that map platform capabilities (e.g., bidirectionality, high-voltage, density, digital controls) to buyer personas in battery testing, semiconductor fabs, industrial automation, and lab procurement.
- Go-to-market playbooks for suppliers, including channel models, pricing sweet spots, and after-sales service design that capture lifetime value in capital equipment deployments.
- A disciplined M&A screen that identifies targets by capability gaps (digital controls, high-voltage design, localized manufacturing) rather than by headline revenues, reducing integration risk and accelerating cross-sell potential.
- Risk and mitigation frameworks tied to raw-material concentration, compliance timelines, and competitive pricing dynamics—structured for immediate board-level decision-making.
Note: the full report includes detailed regional and application splits and the granular quantitative tables that underwrite the conclusions above. Those segmentation tables are intentionally withheld here to encourage access to the full intelligence package.
Competitive landscape — who to watch and why
The market’s competitive topology is an interplay of global incumbents, specialized system integrators, and nimble innovators. The following profiles capture players whose recent moves are shaping buying criteria and market structure:
- TDK-Lambda Americas Inc. (New York, USA): Known for high-power GENESYS DC programmable supplies and the newer GENESYS AC series, TDK‑Lambda is strengthening its industrial and automotive test bench relevance through modular, high‑power solutions suitable for aerospace and renewable testing.
- AMETEK Programmable Power (United States): With precision AC/DC programmable supplies, electronic loads, and systems (Asterion, Mi‑BEAM, i‑BEAM), AMETEK is deepening its position in battery testing and compliance services—evidenced by recent partnerships that broaden calibration and distribution reach.
- Magna‑Power Electronics (Flemington, NJ, USA): Distinguished by rugged DC supplies and vertically integrated U.S. manufacturing, Magna‑Power continues to move upstream in high-voltage and mission‑critical applications, supported by recent product launches and strategic contract awards.
- XP Power (United Kingdom): XP’s digitally configurable HP and HPA series target semiconductor manufacturing and robotics, reflecting a deliberate play into high-uptime, digitally controlled factory floors.
- Phihong USA, Acopian Power Supplies, Pico Electronics, Applied Power Systems: Each of these players occupies focused niches—Industry 4.0 automation OEM solutions, high-voltage platforms, miniaturized converters, and bespoke high-performance systems respectively—creating a diversified competitive field where specialization matters.
Recent market activity underscores these dynamics: product announcements and strategic awards in early‑mid 2026 highlight a race toward higher voltage, denser packaging, and system-level offerings. Examples include a new high‑voltage 1U DC model class and selection to power a hypersonic wind tunnel, plus partnerships to expand distribution and calibration services—all of which shift buyer expectations.
Market dynamics and regulatory realities
- Regulation and compliance: Expect IEC conformity and RoHS 3 compliance to strongly influence procurement cycles, particularly in regulated industries and export-sensitive supply chains. Designing for compliance up-front reduces technical debt and shortens approval timelines.
- Raw-material and supply-chain signals: The programmable power market depends on a specialized ecosystem of electronic components; sourcing concentration in certain regions increases geopolitical and logistical risk. Manufacturers pursuing nearshoring or dual-sourcing strategies will reduce lead-time variability.
- Macro trends: Battery gigafactory growth and semiconductor capex surges create predictable pockets of demand for programmable power systems. Simultaneously, cost competition from lower-cost suppliers is reshaping go-to-market economics for commodity ranges—accelerating consolidation among suppliers who cannot sustain margin contraction.
Risks, mitigants, and recommended near-term moves
For executives preparing budgets and strategic plans in 2026, the recommended priority list is pragmatic and short-cycle:
- Short-term (0–12 months): Lock down supply agreements for critical components; prioritize product configurations that demonstrate IEC/RoHS compliance; accelerate API and telemetry development for new platforms to meet buyer integration requirements.
- Medium-term (12–36 months): Invest in modular architectures that enable field-upgradable features (e.g., firmware-enabled bidirectionality); evaluate strategic alliances with calibration and distribution partners; consider bolt-on acquisitions to acquire high-voltage IP or localized manufacturing capabilities.
- Strategic (36+ months): Build an end-to-end services proposition (test software, predictive maintenance, calibration networks) to move beyond hardware commoditization and capture annuity-style revenue streams.
How to use this report in boardroom decisions
This PW Consulting research is intentionally structured to be directly actionable in board presentations and investment memos. It provides scenario-modeled revenue impacts, capex-to-ROI analysis for new product investments, and an M&A prioritization framework mapped to integration complexity and value capture. Use it to validate budgets, prioritize R&D spend, and set acquisition filters that align with your strategic horizon.
Conclusion and next step
The programmable power supply market in 2026 is a growth arena with clear winners for companies that combine technical differentiation, standards-first design, and resilient supply strategies. Our analysis quantifies the opportunity and prescribes pragmatic moves—while the full report contains the proprietary segmentation, granular regional and application tables, and vendor scorecards necessary to convert insight into signed contracts and launched products.
Access the comprehensive dataset and executable annexes on our site to unlock the detailed splits and vendor-level metrics that senior teams will use to finalize 2026 commitments.
For detailed analysis of this topic, please visit the official page: Programmable Power Supply Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hookah Market to Reach USD 560.9M by 2032 at 6.98% CAGR
By pmarketresearch, 2026-07-13
Hookah Market 2026: Strategic Preview for Decision-Makers
Executive preview
This briefing provides a high-level yet practice-oriented preview of PW Consulting’s full Hookah Market study (base year 2025, historical 2020–2025, forecast 2026–2032). Our research maps the sector’s macro trajectory, competitive architecture, innovation vectors and regulatory inflection points—then translates those into actionable decision frameworks for 2026 investment, product and market-entry choices. The global market, measured in USD (Million), expanded markedly from the early 2020s and is projected to continue growing through the forecast window at a compound annual growth rate of 6.98%—with market sizing and scenarios anchored on 2025 as the base year and forecasts out to 2032.
Hookah Market
Why this study matters for 2026
- Timing: 2026 is the first full year after significant product and corporate realignments in the sector; early movers that integrate new product formats, regulatory hedges and resilient supply chains will capture disproportionate share.
- Decision focus: whether to pursue premium-lounge channels, scale household/e-commerce formats, enter adjacent consumable categories (herbal, flavor-free, electronic systems), or prioritize M&A for rapid capability build.
- Risk landscape: flavor regulation, cross-border trade friction on key inputs, and changing social-consumption patterns require scenario-tested strategies rather than one-off plays.
Market trajectory and macro context
Over the historical window (2020–2025) the market moved from modest baseline levels into a renewed phase of expansion, reflecting recovery dynamics, product innovation and renewed lounge and at-home consumption. Using 2025 as the base year, our forecast to 2032 models a continuation of steady growth at a mid-single-digit CAGR, informed by demand elasticity, product substitution trends and planned new product pipelines from industry leaders.
Hookah Market
For corporate strategists, the headline implications are twofold: first, the market is large and durable enough to sustain multi-year investments in product development and brand building; second, growth is not homogeneous—structural winners will be those who read regulatory signals, diversify channel exposure and lock in resilient raw-material pathways.
Hookah Market
Key growth drivers and headwinds
- Product innovation: rapid adoption of electronic and hybrid hookah systems, modular devices and pod formats is expanding addressable use-cases—particularly in consumer segments that prefer portability, lower profile consumption and perceived harm-reduction attributes.
- Channel reconfiguration: lounges and specialty cafés remain important discovery channels, while digital commerce and specialty retailers are scaling faster for household and gifting use-cases.
- Regulatory pressure: escalating flavor restrictions and tighter product definitions for non-cigarette inhalation products are shifting R&D spend toward flavor-free, herbal and nicotine-free alternatives; firms that preempt regulatory design requirements gain first-mover advantage.
- Supply-chain sensitivity: certain artisanal inputs and charcoal feedstocks are subject to export duties, transport cost volatility and origin-specific constraints—raising the premium on multi-sourcing and local production flexibility.
- Socio-cultural dynamics: generational differences in social consumption mean branding and experience design must be tailored—what resonates in premium lounges differs materially from successful household packs sold online.
Segment and product evolution (strategic view)
Our segment analysis tracks device types (conventional, electronic, pod-based), consumables (tobacco, herbal, nicotine alternatives) and channels (on-premise social venues, household/e-commerce). Instead of reiterating raw splits, the report synthesizes which segments are structurally advantaged under three regulatory scenarios and quantifies unit economics across distribution pathways.
- Innovation pockets: electronic systems and pod-based consumables show disproportionately higher margin expansion potential, though they require upfront engineering and regulatory diligence.
- Value migration: premium device upgrades and experiential services in on-premise venues represent a durable source of differentiation for brands focused on B2B relationships with lounges and hospitality partners.
- Substitution risk: flavor-restrictive policies accelerate consumer migration to herbal and flavor-free consumables; firms with ready-to-market alternatives secure demand continuity.
Competitive landscape—what the leaders are doing
The market presents a mix of global platform players, specialized OEMs and regional craft producers. Leading companies are pursuing divergent but complementary strategies: scale and brand aggregation, OEM specialization, premium craft positioning and geographic cost arbitrage. Key strategic profiles covered in the report include:
- Large branded integrators: global players that combine strong consumable brands with device roll-outs and broad distribution networks. Their recent moves include corporate reorganization, public-market transactions and targeted acquisitions to shore up premium portfolios and accelerate device-consumable integration.
- Specialist OEMs: manufacturers focused on complex, premium and OEM device production, leveraging advanced manufacturing clusters and contract-manufacturing flexibility to serve B2B clients and private-label programs.
- Technology-forward premium makers: firms designing modern, lounge-grade devices using new materials and production technologies—addressing premium venues and discerning at-home users.
- Traditional artisanal producers: suppliers concentrated in lower-cost manufacturing hubs, supplying classic materials and decorative craftsmanship for segment-specific demand.
Notable recent corporate events reinforce these dynamics: a major branded integrator completed a business combination to access public markets and announced strategic acquisitions to broaden its premium consumables range; it also expanded its device portfolio with new pod variants and CBD-infused offerings targeted at specific export markets. These actions highlight a broader industry push to own both hardware and consumable ecosystems—an integration that materially changes channel economics and loyalty dynamics.
Supply chain, trade and manufacturing considerations
- Input concentration: specific natural feedstocks and charcoal formats remain geographically concentrated, exposing manufacturers to origin-specific tariffs and logistics cost variability. The report maps alternative sourcing routes and near-shore manufacturing trade-offs.
- Design and materials: around one-third of recent launches emphasize eco-friendly materials and another tranche focuses on electronic systems—forcing OEMs to invest in new tooling and supply partnerships.
- Inventory and lead times: device-component lead times have lengthened with multi-regional sourcing; our inventory stress tests in the report indicate the minimum buffer ranges required to sustain uninterrupted B2B supply during trade shocks.
What’s inside the full PW Consulting report (actionable components)
The published study combines quantitative forecasts with practical playbooks. Highlights include:
- Robust market model: base-year (2025) calibrated market sizing with historical validation (2020–2025) and scenario-driven forecasts to 2032—presented in downloadable tables and dashboard views for financial planning.
- Go-to-market playbooks: differentiated strategies for premium lounge channels, household/e-commerce scaling and B2B private-label programs; tactical recommendations on pricing, bundling and promotional timing.
- Regulatory impact matrix: jurisdictional heatmaps, likely policy trajectories and product re-engineering checklists to preserve market access under flavor and ingredient restrictions.
- Supply-chain resilience toolkit: alternative sourcing pathways, cost/lead-time trade-offs, and contract language templates to secure critical feedstocks and components.
- Competitive intelligence dossiers: strategic profiles of leading manufacturers and brand owners, capability matrices, and M&A target shortlists with integration playbooks.
- Investment and M&A playbook: valuation approaches tailored to device vs consumable businesses, integration risk checklists and synergies roadmap for bolt-on acquisitions.
- Five investment scenarios: stress, baseline and upside cases with P&L and cash-flow implications for product-line and geographic investments.
Strategic implications for 2026 planning
For corporate executives, the report delivers three immediately applicable decision levers for 2026:
- Portfolio prioritization: allocate R&D and commercial resources toward device-consumable bundles and electronic/pod formats that widen margins and increase switching costs.
- Channel mix optimization: balance investments between on-premise experiential partnerships and direct-to-consumer channels to manage discovery and lifetime value economics.
- M&A and partnerships: pursue bolt-on acquisitions that fill technology or distribution gaps, but use the report’s integration templates to accelerate time-to-money and reduce execution drag.
How to use this preview—and the next step
This article intentionally previews the most material findings and frameworks while withholding the full segmentation tables and granular regional/application splits that underpin our investment models. That granular detail—market-size breakouts by segment, regional demand matrices and unit-economics tables—is available in the full report and its associated data pack, and is what enables precise ROI and capital allocation modeling for 2026 initiatives.
If your team is preparing a 2026 strategic plan, cross-border launch or acquisition thesis, the full PW Consulting Hookah Market report provides the calibrated inputs, scenario-tested playbooks and execution templates you need to translate strategic intent into measurable outcomes. Visit the report page to access the complete dataset, downloadable financial models and the bespoke advisory options for implementation support.
Closing note
The hookah market in 2026 is not a singular opportunity but a mosaic of distinct plays—device innovation, consumable reformulation, channel re-engineering and supply-chain resilience. Companies that combine disciplined market economics with nimble regulatory and sourcing strategies will set the pace. Our full study equips leaders with the evidence, scenarios and operational templates to move decisively; this preview is an invitation to deepen the analysis with the full dataset and bespoke advisory we offer.
For detailed analysis of this topic, please visit the official page: Hookah Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: NMR Spectrometer Market to reach USD 1,712M by 2032 at 5.35% CAGR
By pmarketresearch, 2026-07-13
Nuclear Magnetic Resonance (NMR) Spectrometer Market — Strategic Briefing for 2026 Decisions
Executive summary
The NMR spectrometer market is transitioning from an instrument-centric, research-dominated landscape to a digitally integrated, application-driven industry that directly supports regulated manufacturing and distributed analytical workflows. Our PW Consulting baseline analysis (base year 2025) sizes the global market at USD 1,203 Million and projects steady expansion at a compound annual growth rate (CAGR) of 5.35% across the 2026–2032 forecast window, reaching an anticipated market value in the early 1700s (USD Million) by the end of the period. That trajectory reflects a dual trend: continued investment in ultra-high-field research instruments and rapid adoption of benchtop, cryogen-free, and AI-enabled platforms across pharma, industry QC, and applied research.
Nuclear Magnetic Resonance (NMR) Spectrometer Market
Why this report matters for 2026 strategic planning
-
Investment timing and sizing — The market’s mid-single-digit CAGR signals a stable growth environment where well-timed CapEx and R&D bets can secure disproportionate advantage. Organizations deciding now on lab refresh cycles, manufacturing analytics investments, or vendor consolidation need data-driven scenario framing to avoid both under- and over-investment.
Nuclear Magnetic Resonance (NMR) Spectrometer Market -
Regulatory alignment — Accelerating regulatory acceptance of NMR for identity and purity, and frameworks that favor in-line and at-line analytics in continuous manufacturing, transform NMR from a “nice-to-have” research tool into a core process control technology for life sciences manufacturers.
Nuclear Magnetic Resonance (NMR) Spectrometer Market -
Vendor and technology bifurcation — The market is increasingly segmented by capability: very-high-field systems serving frontier research and structure elucidation, versus compact, integrated solutions for QC, PAT, and decentralized laboratories. Strategic buyers must balance performance needs, total cost of ownership (TCO), and lifecycle service architecture.
-
Concentration dynamics — Market concentration data indicate that leading vendors hold a material share of revenues, but the industry remains contestable for innovative entrants focused on cryogen-free magnets, portability, AI-assisted interpretation, and LIMS/ERP integration.
Core market movements and regulatory drivers
A confluence of technical and regulatory forces is reshaping demand patterns. Pharmaceutical regulators are increasingly comfortable with NMR-based identity and purity testing and are building frameworks that nudge manufacturers toward PAT-enabled continuous operations. Simultaneously, instrument manufacturers are delivering innovations—higher accessible fields, room-temperature shimming, cryogen-free permanent magnets, and AI-assisted spectral interpretation—that lower operational barriers for non-specialist users.
Consequence for buyers: procurement decisions must now be evaluated along three axes simultaneously—analytical performance, integration-readiness (digital and process), and regulatory evidence. Benchtop systems that once targeted teaching labs are now being validated for GMP environments; conversely, ultra-high-field players are differentiating on capability to support increasingly complex molecular characterization challenges.
What the PW Consulting report delivers (practical, decision-ready content)
-
Market sizing and forecast model (2020–2032): a transparent, testable model with scenario toggles for adoption velocity, pricing pressure, and service margins. High-level historical figures and forward curves anchor board-level investment planning.
-
Buyer’s decision framework: TCO calculators, procurement scorecards, and a decision matrix that maps use-cases (R&D, QC, PAT, education) to appropriate instrument classes and service models.
-
Vendor benchmarking and strategic profiles: qualitative and quantitative assessments of major vendors’ strengths, product roadmaps, go-to-market models, and service footprints—sufficient to shortlist suppliers and structure RFPs without revealing detailed vendor financials.
-
Regulatory and validation playbook: a risk matrix linking regulatory trends (including controller frameworks for continuous manufacturing) to validation requirements, audit readiness, and documentation templates.
-
Integration blueprints: practical templates for LIMS/ERP connectivity, edge data capture for PAT, and sample case studies showing how benchtop NMR deployments were staged into multi-site manufacturing networks.
-
Commercial levers and negotiation toolkit: guidance on service bundling, cryogen-management clauses, spare-parts strategies, and maintenance SLAs tailored to different operating models.
-
Deal and M&A intelligence: a shortlist of capability gaps where bolt-on acquisitions make sense (e.g., AI spectral interpretation, cryogen-free magnet platforms, or supply-chain-critical component suppliers) including integration playbooks for buyers.
Competitive landscape — who matters and why
The competitive map includes well-established high-field leaders and a set of agile specialists commercializing compact, low-maintenance platforms. Key firms covered in the report include:
-
Bruker Corporation — a market leader with deep offerings across high-field and benchtop lines; continues to push field boundaries with commercial delivery of flagships that extend research capability.
-
JEOL Ltd. — a high-performance instrument vendor advancing strategies around reduced cryogen dependency and room-temperature shim technologies to lower operating cost for research customers.
-
Magritek Ltd. — a focused innovator in benchtop systems delivering high sensitivity and cryogen-free operation, appealing to decentralised labs and education environments.
-
Oxford Instruments plc — positions itself at the intersection of benchtop convenience and research-level quality, adding AI-assisted workflows to broaden user bases.
-
Anasazi Instruments, Inc. — targets educational and industrial users with permanent-magnet offerings and simplified operational footprints.
-
Nanalysis Scientific Corp. — a portable and benchtop specialist enabling immediate availability and operational simplicity without cryogens.
-
Thermo Fisher Scientific Inc. — leverages broad commercial reach to place routine benchtop platforms in teaching and standard analytical roles.
Recent product and installation moves—ranging from the commercial delivery of unprecedented high-field instruments to launches of AI-assisted benchtop systems and room-temperature shimming platforms—underscore a two-front competitive dynamic: performance-led differentiation at the high end, and operational simplicity + integration at the benchtop/field end.
Strategic implications and recommended actions for 2026
-
Adopt a use-case-first procurement posture. For QC and PAT, prioritize compact, integrated systems with validated digital pipelines and lower TCO; for frontier R&D, map required spectral performance and reserve budget for higher-field instruments.
-
Embed regulatory-readiness into vendor selection. Insist on validated workflows, audit-trail capabilities, and demonstrable evidence of regulatory acceptance for intended use (identity/purity or PAT).
-
Design for multi-vendor resilience. Given the mix of dominant suppliers and nimble specialists, structure supply agreements to protect uptime and spare-parts availability while preserving optionality for future innovation adoption.
-
Invest in digital integration early. Prioritise systems with native LIMS/ERP connectors and cloud/edge architectures to accelerate PAT implementations and consolidate analytical datasets for lifecycle analytics.
-
Quantify cryogen exposure in total cost models. Cryogen-free innovations materially shift operating economics—buyers should model scenarios that include cryogen supply disruption and service variability.
-
Pursue targeted M&A or partner strategies to fill capability gaps—particularly in AI-assisted interpretation, portable magnet technology, and field-service networks.
-
Run a staged deployment: pilot benchtop platforms in QC labs and scale to manufacturing lines once integration and validation lessons are assimilated—this limits program risk while accelerating benefit realization.
How to use the full PW Consulting report
This article previews the strategic framing and top-line market trajectory for executives making 2026 decisions. The full PW Consulting NMR market research suite provides the granular intelligence required to act: downloadable forecast models, vendor scorecards, procurement templates, regulatory validation checklists, and installation case studies that disclose lessons learned and measurable KPIs. Those materials are designed to turn strategy into executable programs—without exposing sensitive segmentation tables in this teaser.
If your organization is planning lab modernizations, PAT rollouts, or acquisition screening in 2026, use this briefing as the framing document for internal alignment, then consult the full report for the detailed inputs and models required to finalize budgets, RFPs, and integration plans.
For detailed analysis of this topic, please visit the official page: Nuclear Magnetic Resonance (NMR) Spectrometer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
High Speed Doors Market to Reach USD 1,889.4M by 2032 with 6.7% CAGR — PW Consulting
By pmarketresearch, 2026-07-13
High Speed Doors Market: A Strategic Preview for 2026 Decision-Makers
As global industrial flows accelerate and hygiene, energy efficiency, and throughput expectations tighten, high speed doors have moved from commoditized accessories to strategic assets across logistics, cold chain, manufacturing, and regulated food and pharmaceutical environments. This preview introduces PW Consulting’s 2026 market study (base year 2025), summarizing the rigorous analysis and practical toolsets that senior executives, M&A teams, product leaders, and procurement heads need to convert market signals into defensible decisions.
High Speed Doors Market
Snapshot — Why this research matters in 2026
-
Market scale and trajectory: The high speed doors market reached a material size in our 2025 base year and is forecast to expand at a mid-single-digit CAGR through the 2026–2032 horizon. That growth reflects a combination of logistics modernization, regulatory-driven replacement cycles, and incremental automation investments.
High Speed Doors Market -
Decision cadence: For 2026 planning cycles—capital allocation, product roadmaps, plant upgrades, and M&A diligence—granular, forward-looking market intelligence is no longer optional. It is the foundation for prioritizing bets and sizing opportunities.
High Speed Doors Market -
Operational impact: High speed door choices influence energy budgets, throughput metrics, safety incidents, and hygiene compliance; the right specification reduces operating expenditure and operational risk, the wrong one multiplies retrofit costs and service headaches.
What PW Consulting’s report delivers (practical, executable)
-
Market sizing & forecast model (base year 2025, outlook through 2032) with scenario variants and sensitivity toggles for macroeconomic and raw-material shocks.
-
Segmentation architecture (by product type, application, and region) linked to buyer personas and procurement decision rules. Note: this preview highlights directionality and drivers; detailed split tables and downloadable datasets are included in the full report.
-
Regulatory and standards matrix mapping compliance triggers (safety, hygiene, lift-systems) to spec sheets and validation checklists usable by engineering teams and third-party certifiers.
-
Supplier and competitor playbooks — capabilities mapping, go-to-market footprints, and service-network overlays to accelerate partner selection or M&A screening.
-
TCO and ROI toolkits: energy, throughput, maintenance, and downtime models that quantify payback under different operating regimes.
-
M&A and inorganic growth frameworks: target archetypes, valuation touchpoints, integration checklists, and post-deal value-capture roadmaps.
-
Commercial annexes: RFP templates, technical acceptance criteria, aftermarket SLAs, and implementation checklists for pilot-to-scale rollouts.
Market dynamics — the data-driven story
Between 2020 and 2025 the market expanded meaningfully as warehouse automation and refrigerated logistics continued to push demand for faster, tighter-sealing door systems. Our modeling, built from a combination of public disclosures, company filings, primary interviews, and installer intelligence, shows sustained expansion into 2032, with the market expected to approach roughly one-and-a-half times its 2025 scale under the base case. The implied compounded annual growth is in the mid-single digits, driven by both retrofit cycles and new-build demand.
Growth is not uniform. Three structural trends explain where and why demand concentrates: (1) throughput and energy economics — faster door cycles and better seals materially shrink heat transfer and pressure differentials, directly improving operational efficiency; (2) regulatory and product safety requirements — evolving standards compel upgrades or replacement, particularly in food, pharma, and cold-chain locations; and (3) automation and connectivity — integration with WMS/ASRS systems raises the value of doors that offer predictable, fast, and safe operation.
Material and standards dynamics are shaping product roadmaps. Fabric curtains—increasingly reinforced polyester and PVC blends—are now the primary curtain materials, selected to reduce energy loss and simplify maintenance. Steel and aluminum subcomponents remain broadly available, albeit with higher emphasis on corrosion-resistant coatings for exterior use. From a compliance standpoint, manufacturers and end users must navigate a denser standards environment: recent updates to DASMA specifications and lifting-cable guidance, European TÜV SÜD / DGUV safety regimes that mandate frequent automatic checks and collision compensation measures, and sector-specific mandates (e.g., FDA-compatible materials for food processing). These regulations convert into purchase drivers and upgrade obligations for facility owners and facility engineering teams.
Competitive landscape — capabilities, not just logos
The market remains moderately fragmented—leading players capture a meaningful share but a long tail of regional specialists and installers persist. The top-three and top-five concentration metrics indicate room for consolidation alongside healthy regional competition. Understanding capability clusters is more important than headline names when evaluating partners or acquisition targets.
-
North American specialists: Several U.S.-based firms excel in engineered roll-up and fabric high-speed systems optimized for cold storage and high-throughput logistics. These vendors typically differentiate through advanced sealing, automation integration, and extensive service networks—critical for customers prioritizing uptime.
-
European engineering leaders: Select European manufacturers combine high mechanical speeds with stringent safety and cycle-life guarantees, appealing to logistics operators and OEMs demanding long service life and compliance with strict local safety rules.
-
Chinese OEMs and exporters: Cost-competitive solutions for large-volume warehouses and standard applications, increasingly offering CE/UL-certified options and emphasizing low-maintenance spiral systems for logistics parks and third-party logistics providers.
-
Product innovation vectors: Patented reinsert technologies, soft-edge safety features, auto re-feed systems, and spiral door architectures provide functional differentiation. Producers who couple mechanical reliability with digital telematics for predictive maintenance will extract higher aftermarket revenue per installed door.
Recent market moves underscore these dynamics: a leading North American manufacturer staged live spiral-door demonstrations at major 2026 trade events to showcase integration capabilities, while an Asian supplier published updated product guides emphasizing “zero-maintenance” spiral architectures and smart logistics integrations. These activities reflect the dual priorities of demonstrable operational superiority and an accelerated push into system-level offerings.
Strategic implications — a 2026 playbook
-
For incumbents: Prioritize modular platforms that support rapid field configurability and telematics-enabled aftermarket services. Invest selectively in compliance-testing and certification labs to shorten sales cycles with regulated buyers.
-
For challengers and new entrants: Target vertical niches (e.g., food-grade environments, cold-chain micro-distribution) where technical spec complexity raises barriers to low-cost competitors. Offer bundled service agreements to lock in recurring revenue.
-
For private equity and corporate M&A teams: Screening should emphasize service footprints, digital aftermarket capabilities, and regional channel strength. Small bolt-ons that add installer networks or certification competencies often deliver outsized integration synergies.
-
For procurement and supply chain leaders: Hedge fabric and polymer exposure and qualify multiple steel-coating suppliers to reduce retrofit lead times. Incorporate regulatory-compliance clauses and test-acceptance milestones into contracts.
-
For operations and engineering teams: Run targeted pilots that measure energy savings, seal performance, and cycle reliability in live conditions. Use TCO models to compare replacement vs. retrofit across the installation population.
Risk radar — what to monitor in 2026–2028
-
Regulatory tightening in safety and hygiene standards that could accelerate replacement cycles and raise compliance costs.
-
Raw material price volatility for polymers and coatings that impacts margins for standard models.
-
Service-network shortages in tight labor markets, raising aftermarket SLA fulfillment risk.
-
Cyber and connectivity risks as doors become integrated with building and logistics control systems—security must be a specification item, not an afterthought.
-
Trade policy shifts that affect cross-border supply of certified doors and components.
How PW Consulting’s study unlocks commercial value
This research blends a quantitative forecasting engine with qualitative, practitioner-focused guidance. Subscribers receive: interactive forecast models, a prioritized list of actionable initiatives tied to near-term ROI, detailed supplier capability matrices, regulatory compliance playbooks, and commercially ready annexes (RFP templates, acceptance tests, and TCO calculators). Crucially, the report balances top-down market sizing with bottom-up installer and OEM intelligence so decision-makers can align capital allocation with measurable operational benefit.
We intentionally hold back the detailed, tabulated segment splits in this preview. That granular intelligence—region-by-region and application-by-application sizing, competitive shares at product-family level, and downloadable datasets—is included in the full PW Consulting deliverable and is designed to plug directly into your financial models and procurement pipelines.
Next steps for leaders
-
Use the preview to align executive hypotheses for 2026 planning; then deploy the full dataset to stress-test capex, product, and M&A scenarios.
-
Commission a short, custom workshop with PW Consulting to map the report’s findings to your portfolio and to co-create a 6–12 month prioritized implementation plan.
-
Adopt a staged pilot approach: validate energy and throughput claims on two representative sites before committing to multi-site rollouts—use our TCO templates to quantify payback.
In sum, the high speed doors market in 2026 sits at the intersection of operational efficiency, safety regulation, and digitally-enabled service economics. Strategic clarity—grounded in reliable forecasts, standards-aware product specifications, and realistic aftermarket assumptions—turns opportunities embedded in a growing market into durable advantage. PW Consulting’s full report supplies the granular intelligence and executable toolkits you will need to make those decisions with confidence.
For detailed analysis of this topic, please visit the official page: High Speed Doors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Avocado Market to Hit USD 29,400M by 2032 at 8.33% CAGR
By pmarketresearch, 2026-07-13
Avocado Market 2026: Strategic Imperatives from PW Consulting’s Forward-Looking Analysis
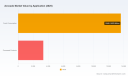
As buyers, suppliers, investors and policy-makers plan for 2026, the avocado value chain is at an inflection point. PW Consulting’s new Avocado Market study (base year 2025; forecast 2026–2032) synthesizes a data-rich view of market size, growth trajectories and structural forces that will determine who captures value over the coming cycle. The headline: global avocado market momentum remains robust — our modeling shows an overall market expanding from a 2025 baseline to materially larger volumes and revenues by 2032, at a compound annual growth rate (CAGR) of 8.33%. For executives who must make sourcing, pricing, investment or sustainability commitments in 2026, this report turns high-level growth into operational priorities and risk-managed options.
Avocado Market
Why 2026 is a Strategic Pivot Year
-
Transition from seasonal volatility to structural growth. Between 2020 and 2025 the market demonstrated resilient expansion; the near-term forecast through 2032 assumes continued demand growth, evolving consumer patterns and rising processed-avocado applications. That trajectory creates attractive upside for scale players while increasing competition among mid-tier producers and processors.
Avocado Market -
Sustainability regulations are becoming binding commercial conditions. The Mexican export ecosystem — a dominant source for global supply — has moved from voluntary pledges to contractual eligibility rules that affect market access. The practical consequence for buyers and financiers is simple: traceability, land-origin verification and defensible deforestation metrics are now procurement conditions, not just PR objectives.
Avocado Market -
Price dynamics are shifting with fruit sizing and supply composition. Recent months have seen increased availability of larger-size Hass fruit from key producing regions, materially affecting FOB pricing and compressing premiums historically paid for large fruit. Margin sensitivity now hinges on packing, sizing and logistics efficiency.
What PW Consulting’s 2026 Brief Delivers (Operationally Applicable)
-
Transparent market architecture: clear vintage-to-forecast market sizing (2020–2032), growth drivers, and sensitivity scenarios keyed to yield, trade policy and price shocks.
-
Actionable go-to-market playbooks for buyers and brands: sourcing optimization (size-by-demand), contract language to embed sustainability clauses, and inventory strategies for seasonal swings.
-
Supply-chain diagnostic tools: mapping of cold chain exposures, packing capacity constraints, and a checklist to prioritize investments in sorting and size-differentiation technology that preserve margins under changing price structures.
-
Regulatory and ESG compliance templates: supplier on-boarding workflows that satisfy zero-deforestation verification, traceability roadmaps and audit-ready documentation requirements for 2026 procurement cycles.
-
Investment and M&A decision frameworks: valuation multipliers that account for concentration risks, vertical-integration upside and the earnings impact of sustainability capital expenditures.
-
Model-ready datasets and downloadable dashboards for scenario analysis (price, yield, regulatory shock) that senior teams can integrate with their ERP/FP&A systems.
Market Structure and Competitive Dynamics
The market’s concentration profile matters for negotiation strategy. Our market concentration analysis indicates meaningful consolidation at the top (CR3 ~48%; CR5 ~68%), creating a landscape where a handful of large players and producer associations exert significant influence over export flows, quality standards and industry-level initiatives. For corporate decision-makers, that concentration translates into both supply security and counterparty dependence: securing preferred access to large-volume channels often requires alignment with association-led programs and certification schemes.
Four industry actors warrant focused attention in 2026:
-
Association of Avocado Producers and Packers Exporters of Mexico (APEAM) — APEAM is a pivotal coordination node for Mexican supply. It represents tens of thousands of producers and numerous packers, organizes export logistics and increasingly operates at the interface of sustainability verification. The Association’s April 2026 formalization of a Zero Deforestation Agreement accelerates the timeline for fully traceable exports and will be a gating factor for buyers who rely on Mexican origin fruit.
-
Mexican Hass Avocado Importers Association (MHAIA) — MHAIA plays a central role in North American retail distribution through brand and trade promotion. Retail buyers should view MHAIA as both a barometer of retail demand and a partner for point-of-sale programs that can absorb production surges, particularly where size distributions change.
-
Avocado Institute of Mexico — As an industry research and promotion arm, the Institute’s economic impact studies and sustainability programming increasingly shape exporter eligibility and messaging. Corporates planning co-funded promotion or R&D partnerships will find expedited stakeholder engagement via the Institute.
-
Peruvian Avocado Commission (PAC) — Peru continues to be a strategic alternative supplier, pursuing market diversification with targeted promotion overseas. For buyers hedging single-origin risk, PAC-led initiatives and varietal differentiation (Hass/Fuerte) create portfolio options around seasonality and quality specifications.
Regulatory and Pricing Signals That Should Shape 2026 Decisions
-
Deforestation rules are now operational. Since January 2026, exports of avocados grown on illegally deforested land are ineligible under the rules codified by Mexican industry alliances and government policy. Additionally, recent commitments indicate a broader produce-export requirement to be deforestation-free by 2030. Procurement teams must embed chain-of-custody and land-use verification into supplier contracts immediately.
-
Price compression from size availability. In March 2026, larger-size Hass fruit from principal origins traded at roughly one dollar per pound FOB — a level materially below the prior-year average. The cause is a supply-side shift toward larger-calibre fruit that narrows the premium for size. Commercial teams should reassess pricing ladders and contract metrics (size mixes, quality premiums, rejection thresholds) to protect margins.
-
High eligibility for compliance, but administrative friction exists. Industry statements indicate a high percentage of existing orchards can comply with zero-deforestation rules immediately; however, the administrative burden of verification and compensation mechanisms for prior land-use change requires operational investment. Firms that invest early in supplier digitization and verification will gain first-mover advantages in secured volumes and cost of compliance.
Strategic Playbook for 2026 (Prioritized Actions)
-
Embed sustainability as a commercial KPI. Make zero-deforestation verification a contractual prerequisite for 2026 purchase orders. Where suppliers require investment to comply, structure shared-cost remediation or certification programs to lock in supply.
-
Re-engineer pricing and sizing strategies. Update commercial terms to reflect current pricing volatility and size-composition shifts. Consider dynamic pricing corridors tied to FOB price indices and implement size-tiered contracting to protect margins on premium-size fruit.
-
Diversify supply-season portfolios. Use cross-origin sourcing (e.g., partnering with Peruvian exporters) to smooth seasonality risk while retaining preferential access to peak Mexican supply through association partnerships.
-
Invest in post-harvest differentiation. Capital allocation to grading/sorting technologies and cold-chain improvements will pay back quickly in an environment where size and quality premiums are compressed.
-
Negotiate with association-level stakeholders. Engage APEAM/MHAIA/industry institutes proactively to influence implementation timelines, co-fund traceability pilots and access aggregated export capacity.
-
Stress-test scenarios for 2026 procurement plans. Run three-point scenarios (base/growth/shock) using the report’s downloadable model to quantify working-capital needs, margin sensitivity and potential substitution effects.
What We Deliberately Withhold Here — And Why
To maintain the “trailer” ethos of this introduction, we have demonstrated the analytical depth and practical takeaways available in the full PW Consulting Avocado Market study while intentionally omitting granular, table-level segmentation and region/application-specific financials from this preview. The report contains exhaustive segmentation by region, variety and application, with downloadable datasets, price-series, and a full list of assumptions behind our 8.33% CAGR projection. Those segment-level numbers are the core IP of the study and are presented in interactive form in the full report and dashboard.
Next Steps for Leaders Deciding in 2026
-
Procurement and sustainability leads should request the traceability checklist and supplier audit matrices immediately to align 2026 sourcing cycles with deforestation eligibility windows.
-
Commercial and finance teams should utilize the model scenarios to reprice contract renewals and to evaluate hedging strategies against FOB indices and size-driven price moves.
-
Strategic investors and acquirers should run the report’s sector valuation module to assess accretive M&A targets in packing, cold storage and certified-origin brands that can capture the premium for verified, deforestation-free supply.
PW Consulting’s Avocado Market study is engineered to convert macro growth trends into executable 90–180 day plans and longer-term investment roadmaps. For the full dataset, segmentation tables, supplier lists and model files that support the 2026 decisions summarized here, access the complete report and interactive dashboard on our client portal.
For detailed analysis of this topic, please visit the official page: Avocado Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Aluminum Composite Panels Market Poised for 6.16% CAGR (2026–2032) — PW Consulting
By pmarketresearch, 2026-07-13
Aluminum Composite Panels Market: Strategic Outlook for 2026 Decision‑Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise, decision‑focused introduction to our latest Aluminum Composite Panels (ACP) market study. This briefing surfaces the macro trends, competitive moves, and actionable implications that should inform capital allocation, commercial strategy, and supply‑chain planning in 2026 — while preserving the detailed segment‑level intelligence for the full report. Consider this a strategic trailer: rigorous, evidence‑based, and oriented to near‑term action, but intentionally high‑level on proprietary breakdowns so that stakeholders must access the full dataset for transactional implementation.
Aluminum Composite Panels Market
Market pulse and forecast framing
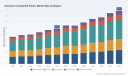
Our market modelling (base year 2025, historical window 2020–2025, forecast 2026–2032) shows the ACP market continuing a steady expansion driven by regulatory tightening, product innovation, and retrofit demand. Measured in USD (Billion), the industry expanded from approximately 4.5 in 2020 to about 5.8 in 2025 and — under the central forecast — reaches the mid‑single‑digit range in 2026 before progressing toward an expected market size of roughly 8.8 billion by 2032. The compound annual growth rate (CAGR) for the forecast horizon is 6.16%.
Aluminum Composite Panels Market
Why this matters for 2026: the market is large enough to sustain multiple business models (premium, compliance‑led, and cost‑competitive manufacturing), yet dynamic enough that a single regulatory or product innovation can re‑rate competitive positions quickly. The 6.16% CAGR and the distribution of growth across construction, retrofit, and specialty transport applications underline opportunities for manufacturers and material suppliers to capture structural margin improvement — provided they align product, certification, and channel strategies before demand shifts accelerate.
Aluminum Composite Panels Market
What the PW Consulting report delivers (practical tools inside)
- Market sizing and an auditable methodology spanning 2020–2032, with scenario variants tied to regulatory and raw‑material shocks.
- Demand driver mapping and a three‑scenario demand model (conservative, base, accelerated) that translates macro inputs to addressable revenue by product family.
- Supplier risk matrix and procurement playbook: aluminum exposure modelling, hedging levers, and recommended contract structures to protect margins.
- Regulatory compliance playbook: certification timelines, regional code comparators, and a go‑to‑certification roadmap for A2 and non‑combustible classifications.
- Commercial playbooks for OEMs and cladding contractors: channel economics, specification tactics, and conversion cost models.
- M&A and JV decision framework: valuation sensitivities, integration scorecards, and five archetypal consolidation targets.
- Implementation roadmaps with 6–18 month KPIs for product launches, certification sequencing, and supply‑chain reconfiguration.
Core dynamics shaping 2026 strategy
- Regulatory acceleration: Fire‑safety standards and product certifications are the single biggest short‑term commercial lever. Recent regulatory moves — including the extended compulsory certification for ACP in some markets and the emergence of A2 fire‑retardant cores — have shifted procurement specifications toward certified, non‑combustible solutions. Companies without rapid certification pathways face specification exclusion on major projects.
- Input cost volatility and pass‑through mechanics: Primary aluminum prices averaged near USD 2,600 per ton in early 2025, exhibiting intra‑year swings linked to production policy and geopolitical risk. In our cost model, metal content accounts for the majority share of panel input cost, making raw‑material strategy (hedging, local sourcing, value‑added alloy management) essential to margin protection.
- Product innovation and differentiation: Lightweight panels for transportation, higher performance fire‑resistant cores, and eco‑certified product lines (CE‑certified entrants enabling EU market access) are reshaping value propositions. Innovations that reduce weight or improve fire performance materially affect specification decisions in both infrastructure and mobile applications.
- Channel bifurcation: Project‑specification buyers (architects, large contractors) are increasingly driven by compliance and lifecycle cost, while signage and smaller contractors compete on lead time and price. The implication: companies need dual go‑to‑market capabilities — a compliance/systems approach for large projects and a fast‑turn commodity channel for signage and advertising segments.
Competitive landscape — strategic implications (what top players are signaling)
The market structure is neither atomized nor monopolistic: it supports national champions, specialized regional suppliers, and nimble innovators. Below are high‑level strategic reads on representative vendors based on public profiles and recent moves.
- Alucobond (United States) — a pioneer in metal facades that is increasingly leveraging product innovation (for example, ultra‑lightweight panels aimed at transportation) to create cross‑sector mobility opportunities. Strategy implication: incumbency in architecture combined with targeted product differentiation positions firms like Alucobond to capture premium margins when they can scale specialty products into adjacent sectors.
- ALPOLIC (Chesapeake, Virginia) — a leader in code‑compliant, recycled‑content ACM with demonstrated capability to certify products across multiple jurisdictions. Strategy implication: emphasis on recycled content and code compliance is an effective barrier to entry where procurement priorities include sustainability and regulatory compliance.
- Alfrex (USA) — integration of in‑house fire‑resistant core compounding and plate/coil coating options enables faster technical iterations and localized supply. Strategy implication: vertical integration around critical core technologies reduces time‑to‑market for certified offerings and is an efficient way to manage margin under cost pressure.
- Alumanate (USA) — focused on sign‑grade ACM with rapid manufacturing lead times; competitive where quick turnarounds and localized supply are primary buyer criteria. Strategy implication: speed and regional footprint can be used to defend pricing in lower‑differentiation segments.
- Aludecor (India) — demonstrates how emerging‑market players combine customization (color, finish) with fire‑rated options to serve highly price‑sensitive but regulation‑aware segments. Strategy implication: local customization and certification competency are prerequisites for market share in rapidly urbanizing markets.
Recent industry moves — for example, the launch of an A2 fire‑retardant core production facility in 2025, ultra‑lightweight product introductions, and expanded certifications for specialty composite systems in 2026 — reflect a broader trend: certification and product performance now directly translate to access on higher‑value projects.
Investment and commercial actions recommended for 2026
- Prioritize certification: accelerate A2 and non‑combustible pathways where your product roadmap allows, and build certification timing into go‑to‑market plans. Loss of specification access can be material and rapid.
- Hedge and diversify aluminum exposure: adopt layered procurement (combining term contracts, regional sourcing, and strategic inventory), and stress‑test pricing pass‑through clauses with typical project stakeholders.
- Segment product offering by buyer economics: deploy a dual strategy of compliance‑led premium products for architectural and infrastructure projects, and a commoditized offering optimized for signage/advertising where speed and cost matter more.
- Invest selectively in lightweight and transport‑grade panels if your manufacturing footprint can scale; weight reduction is a clear P&L lever for transportation OEMs and can unlock new contracts.
- Prepare M&A playbooks that prioritize technologies (FR core compounding, coil coating) and local manufacturing footprints to reduce lead times and import exposure.
Risk matrix: near‑term threats and mitigants
- Raw material price shocks — mitigate with multi‑tiered sourcing and hedging; model 20–30% price shock scenarios in capex plans.
- Regulatory lag or misalignment — maintain a certification task force and early engagement with notified bodies and code authorities.
- Specification capture risk from innovators — protect margins with faster NPD cycles and pilot partnerships with architecture firms and OEMs.
- Quality and counterfeit product risk in cost‑sensitive channels — enforce traceability, branded supply chains, and third‑party verification for high‑risk contracts.
Methodology transparency and what we intentionally withhold here
The full PW Consulting report contains the granular, client‑grade models and the segmented intelligence that underpins the strategic recommendations above: detailed regional and application breakdowns, product‑type level pricing curves, manufacturer revenue splits, and transaction‑ready supplier scorecards. In this briefing we deliberately show the market sizing trajectory, the 6.16% CAGR, and the high‑level strategic implications — but we have withheld the proprietary segment allocations and exact price curves to preserve commercial value for subscribers and potential advisory engagements.
Conclusion — what to do next in 2026
For executives making 2026 choices, the imperative is clear: align product certification, raw‑material strategy, and channel segmentation around the twin realities of rising regulatory thresholds and material cost volatility. Companies that move first to secure certified, demonstrably fire‑safe, and/or lightweight product offers — and that back that move with supply‑chain hedges — will capture the most valuable specification positions as the market expands toward the forecast horizon.
PW Consulting’s full report operationalizes these recommendations into implementation roadmaps, procurement templates, and valuation tooling. For teams preparing board briefs, M&A diligence, or a three‑year commercial plan, the complete dataset and models are available on our report page.
For detailed analysis of this topic, please visit the official page: Aluminum Composite Panels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Period Panties Market to Reach USD 321.7M by 2032 (7.05% CAGR)
By pmarketresearch, 2026-07-13
Period Panties Market 2026: Strategic Preview and Decision Framework
Introduction — Why this moment matters
The period panties market has moved beyond niche novelty to become a calculated strategic frontier for consumer health, intimate apparel, and sustainable personal-care portfolios. Between rising consumer preference for reusable solutions, tightening regulation on product chemistries, and clear indications of steady demand growth, 2026 will be a pivotal year for companies deciding whether to scale, specialize, partner, or exit. This short-form briefing previews PW Consulting’s full Period Panties Market study and highlights the practical, decision-grade intelligence executives will need to act confidently in 2026.
Period Panties Market
Market snapshot: scale, trajectory, and what it means for 2026 planning
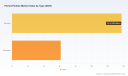
At a macro level, the market has demonstrated consistent expansion over the past half-decade and is on a trajectory that supports continued investment. From our report’s base-year perspective (2025), total industry revenues rose meaningfully since 2020 and are forecast to continue expanding through 2032 at a compound annual growth rate of approximately 7.05%. By the end of the forecast horizon the market is expected to be materially larger than it is today, reflecting both unit growth (adoption and usage frequency) and premiumization (higher-value SKUs and adjacent-service monetization).
Period Panties Market
For corporate planning, that growth profile translates into three strategic realities for 2026: (1) sufficient market momentum exists to justify new product development and channel expansion; (2) margin expansion is achievable for brands that systemically address sustainability and regulatory risk; and (3) scale remains a differentiator—but not an absolute barrier—to entry for focused challengers with clear positioning.
Period Panties Market
What the full report delivers — practical, operational intelligence
- Quantified demand trends and revenue forecasts across 2020–2032 with scenario analysis calibrated to regulatory and material-cost shocks.
- A dynamics module that maps the most consequential non-market forces (regulatory updates, ingredient bans, and sustainability innovations) to impact timelines and P&L exposures.
- Go-to-market playbooks tailored for incumbents, direct-to-consumer challengers, and private-label manufacturers — including channel mixes, promotional ladders, and price-pack architecture examples.
- SKU-level product roadmaps: material trade-offs, cost-to-serve models for reusable vs. disposable offerings, and laundering/aftercare positioning that improve retention.
- Supply-chain and sourcing maps that identify critical raw-material nodes, alternate suppliers, and strategic inventory levers to mitigate ingredient constraints.
- Competitive profiles and M&A screens with playbooks for partnerships, licensing, and bolt-on acquisition targets.
- Consumer segmentation and behavioral models that marry attitudinal data to actual purchase flows—actionable for marketing and product teams.
Competitive landscape — players, capabilities, and likely next moves
The competitive field is populated by digitally native brands with differentiated product engineering, legacy intimates brands expanding into the category, and a growing number of regionally focused challengers. Leading players are building defensible positions along four vectors: absorbency and fit engineering, material provenance and sustainability claims, inclusive sizing and gender positioning, and channel mastery (DTC subscription vs. retail partnerships).
- Saalt: Known for leakproof engineering and long-wear claims; positioned to leverage patent-backed gusset technology in both direct channels and clinical-adjacent partnerships.
- Knix: A high-volume North American leader with strong brand equity and SKU breadth; will likely invest in premium and youth-facing sub-brands to protect growth.
- Thinx: Differentiated on performance claims and youth outreach; a candidate to expand into adjacencies (postpartum, incontinence) while protecting core anti-leak IP.
- Modibodi: Early mover on reusable technical linings and multi-layer systems; best placed to exploit sustainability-driven premiumization and international channel expansion.
- Rael, Ruby Love, The Period Company, TomboyX: Each brings specific strengths—from organic-material positioning and teen sizing to gender inclusivity and price accessibility—that make them attractive acquirers or acquisition targets depending on strategy.
Strategic implication: 2026 will favor brands that convert technical performance into clear consumer value propositions (e.g., “12-hour protection” backed by test protocols), while also demonstrating a defensible supply chain and regulatory awareness.
Regulatory, material and consumer dynamics shaping near-term strategy
- Regulatory posture: Recent clarifications and amendments to product classification and labeling have raised the compliance floor for manufacturers. A notable development is the regulatory framing that situates many period panties under medical-device rules with lower premarket burdens for routine products; parallel state-level actions have introduced specific ingredient restrictions and disclosure demands.
- Ingredient constraints and disclosure: Several U.S. states have enacted restrictions (including PFAS bans in menstrual products) that materially affect formulation choices and supplier sourcing. California’s continuing rollout of mandatory disclosure of intentionally added ingredients has increased due-diligence and labeling costs for multi-jurisdictional players.
- Sustainability & circularity: Innovations in compostable fabrics and extended-lifetime reusable constructions (including recent commercial partnerships to bring high-compostability product lines to market) are reshaping product development roadmaps. These developments create both premiumization opportunities and operational trade-offs (e.g., durability vs. compostability).
- Consumer preference shift: Empirical market signals show consumers increasingly favor reusable solutions for cost and environmental reasons, but adoption hinges on perceived convenience, hygiene claims, and trust in care instructions—areas where brands can establish durable differentiation.
Practical strategic moves for 2026 (what should leadership teams do now)
- Prioritize regulatory-compliant reformulation and labeling roadmaps: Build a cross-functional regulatory & procurement task force to de-risk PFAS exposure and to prepare for expanding ingredient disclosure requirements. Map alternative suppliers and secure multi-year contracts for critical technical textiles.
- Invest in third-party validation & transparent testing: Convert performance claims into retailable trust—independent lab validation of absorbency and leakproof duration will be a purchase driver and a defensive asset in retail listings and marketplaces.
- Segment the product portfolio by usage occasions: Create clear, monetizable tiers (light, moderate, heavy/postpartum, overnight) and tie retention programs to laundering guidance and subscription models to increase LTV.
- Pursue partnerships that extend lifecycle narratives: Link compostable or long-life product lines with retrofit services (e.g., take-back, recycling) or third-party composting partnerships to credibly claim circularity without sacrificing durability for heavy-use segments.
- Channel and pricing playbook: Test hybrid go-to-market models that blend DTC subscription economics with selective retail distribution to reach discovery customers while protecting margin and data capture for direct channels.
- M&A and partnership scouting: Target capability buyouts (materials science, testing labs, or regional logistics) rather than revenue acquisitions if your priority is speed-to-market on safer formulations and scale efficiencies.
Commercial execution levers — quick wins versus structural investments
- Quick wins (0–12 months): Launch targeted performance-validated SKUs for high-intent cohorts; publish ingredient disclosures and lab results prominently; roll out targeted digital acquisition with educational content on care and sustainability.
- Structural investments (12–36 months): Reengineer supply contracts for PFAS-free components, invest in proprietary absorbent linings or licensing agreements, and build post-sale services (subscriptions and take-back programs) that increase customer lifetime value.
Competitive monitoring — what to watch in 2026
Track the following near-term signals: large retailers’ private-label moves into reusable period wear, new regulatory clarifications at federal and state levels, patent filings on absorbent linings, and a wave of partnerships aimed at compostability claims. We also expect to see increased cross-category bundling (e.g., period panties + subscription menstrual-care kits) as brands chase share of wallet.
Methodology note and the “trailer” to the full report
PW Consulting’s full study synthesizes historical sales data, primary interviews with manufacturers, retailers and distributors, consumer-panel behavioral microdata, and materials-cost modeling. The report provides granular segmentation, regional and application-level breakdowns, competitive share models, and scenario-based P&L impacts under multiple regulatory and input-cost permutations. In keeping with the practice of prompting informed commercial engagement, this preview omits the proprietary segment-level shares, SKU-level elasticity matrices, and transaction-level pricing models that constitute the report’s core deliverables.
Final word — how to use this preview to set 2026 priorities
Use this briefing to align your executive questions: Are you a product-first brand that should accelerate technical validation and premiumization? Are you a cost-focused manufacturer seeking entry via private label? Or are you a retailer evaluating captive-brand economics versus partnering with branded innovators? The full PW Consulting Period Panties Market report turns the high-level signals summarized here into executable roadmaps, valuation-grade forecasts, and negotiation playbooks tailored to each decision profile. For teams making budget, M&A, or R&D commitments in 2026, that operational intelligence will materially shorten time-to-decision and lower execution risk.
For detailed analysis of this topic, please visit the official page: Period Panties Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Manuka Honey Market Poised for Growth at 5.98% CAGR Through 2032
By pmarketresearch, 2026-07-13
Manuka Honey Market: Strategic Outlook for 2026 — A PW Consulting Preview
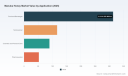
As supply chains reset, consumer health narratives evolve, and regulatory regimes tighten, Manuka honey stands at an inflection point. Our latest PW Consulting market study (base year 2025) synthesizes five years of historical dynamics, and projects performance through 2032 — providing the strategic context executives need to make high-stakes 2026 decisions. The global Manuka honey market reached a notable milestone in 2025 and, with a compound annual growth rate (CAGR) of 5.98% across the 2026–2032 forecast window, represents a commercially significant, premium food-and-health ingredient category for brand owners, ingredient buyers, and investors.
Manuka Honey Market
Why this study matters for 2026 planning
-
It translates macro momentum into boardroom-relevant scenarios. The market’s steady mid-single-digit CAGR masks critical inflection points — scarcity-driven price pressure, certification-driven premiumization, and a channel shift toward health-first e-commerce — that will determine winners and losers in 2026.
Manuka Honey Market -
It isolates operational levers. Given constrained floral supply and increasingly exacting export controls, decisions on sourcing, vertical integration, and packaging resilience will materially affect margins and access to high-value markets.
Manuka Honey Market -
It aligns go-to-market choices with compliance reality. Regulatory enforcement and independent certification regimes are now de facto market access requirements in several markets; the study maps the interaction between certification, testing regimes, and commercial positioning.
Market trajectory — the headline view
From a clear 2025 baseline, the market is forecast to expand at approximately 5.98% CAGR over the 2026–2032 period. That pace is indicative of a mature premium niche that benefits from sustained consumer interest in natural therapeutics and functional foods, while being moderated by raw-material constraints and regulatory friction. For commercial strategists, the implication is that organic top-line growth remains available, but it must be harvested through precision moves — not broadscale volume plays.
Core dynamics shaping strategy
-
Premiumization and trust: Consumers continue to pay a premium for verified potency and provenance. Certification schemes (e.g., established methylglyoxal-based verification systems) now underpin product credibility. Brands without robust traceability face uphill battles in premium channels.
-
Supply-side scarcity and raw-material cost inflation: Tight floral supply windows and concentrated production geographies create periodic price spikes and procurement risk. Market signals in late 2025 showed wholesale raw material prices at elevated levels, reinforcing the need for multi-year supply agreements and inventory strategies.
-
Regulatory and certification gatekeeping: Export and labeling regimes have hardened. Authoritative testing definitions and recognized laboratory networks are prerequisites for meaningful access to key markets. Compliance is no longer just legal hygiene — it is a commercial enabler.
-
Channel bifurcation: Traditional retail remains important for mainstream penetration, but premium and therapeutic propositions are migrating toward direct-to-consumer and health-channel models where storytelling, certification, and consumer education drive conversion.
-
Product innovation beyond jars: Encapsulated nutraceuticals, skincare formulations, and combined functional-ingredient offerings are expanding the addressable market, but each application introduces distinct margin and regulatory profiles that require tailored strategies.
Competitive landscape — concentrated but evolving
The Manuka honey ecosystem is characterized by a moderate level of concentration: a small group of established players controls a meaningful share of supply and certification-recognized inventory, while a broader field of regional producers and new entrants competes on niche differentiation. This concentration creates both stability and chokepoints: stable supply from integrated leaders, but risk of access constraints for downstream buyers.
Key archetypes we profile in the study include:
-
Vertically integrated leaders with traceability crowns — companies that control hive-to-shelf processes and have invested heavily in independent testing and quality assurance. Their strategic advantage lies in predictable supply, recognized certification, and premium pricing power.
-
Specialist organic and clean-label innovators — producers focused on certified organic lines, clean-label processing, and wellness formulations. Their success hinges on authenticity narratives and channel partnerships in natural health retail.
-
Regional exporters and authenticity challengers — firms that leverage national authenticity marks to penetrate export markets, often competing on price-performance or specific certification endorsements.
Recent industry developments underscore these dynamics. A major industry participant initiated a voluntary recall in 2025 tied to packaging integrity, highlighting how operational minutiae can cascade into reputational and distribution risk. Conversely, recognition of an Australian producer for export excellence and official updates to approved exporter lists in late 2025 demonstrate that regulatory alignment and export credentials remain decisive commercial assets.
Strategic implications for 2026 decision cycles
-
Sourcing and procurement: Move from transactional buying toward contracted supply with quality- and compliance-linked SLAs. Scenario planning should assume periodic raw-material tightness and incorporate hedging, vertical partnerships, and co-investment in apiary management.
-
Portfolio management: Distinguish between therapeutic-grade SKUs that command margin and mainstream SKUs that drive volume. Allocate R&D and marketing spend to SKUs where certification and evidence-based claims create defensibility.
-
Regulatory playbook: Invest in recognized certification and MPI/AMHA-compliant testing pathways early. For exporters, ensuring facilities and processes are on approved lists materially reduces time-to-market and trade friction.
-
Operational resilience: Packaging integrity and cold-chain/handling controls are not mere cost centers; recent recall activity shows they are core to continuity. Quality assurance programs should extend to co-packers and contract manufacturers.
-
M&A and partnerships: The market’s concentration profile makes bolt-on acquisitions and supply agreements attractive for fast access to certified inventory. But diligence should prioritize chain-of-custody, lab-test history, and export credentials over headline production volumes.
Risk matrix — what to watch in 2026
-
Authenticity and testing disputes: Independent lab validation and defensible chain-of-custody documentation are essential to mitigate litigation and market rejection.
-
Biosecurity and cross-border controls: Import permits and species-specific biosecurity checks can introduce delays and unexpected costs for cross-jurisdictional supply.
-
Operational slip-ups: Packaging failures or labeling non-conformances can trigger recalls with outsized commercial impact in premium categories.
-
Price volatility: Periodic raw-material cost surges require commercial models capable of absorbing temporary margin compression without brand damage.
What PW Consulting’s full report delivers (actionable highlights)
Our study is structured for executive decision-making and includes pragmatic tools and deliverables designed for rapid implementation:
-
Market sizing and forward-looking scenarios (base year 2025; forecast to 2032) with sensitivity analysis across supply and demand shocks.
-
Competitive profiles and capability mapping for the leading producers, focusing on traceability, certification, vertical integration, and channel reach.
-
Regulatory and certification playbooks for major export markets, including lab-recognition matrices and practical compliance checklists.
-
Commercial playbook templates — sourcing contracts, inventory hedging models, and premiumization positioning frameworks tailored for CPG and ingredient buyers.
-
Operational risk checklists covering packaging, co-packer oversight, recall readiness, and lab-test governance.
-
Deal rationales and valuation comparables for M&A activity, alongside a prioritized list of strategic targets and partnership archetypes.
Note: this preview intentionally omits the granular region-by-region and application-level tables that many corporates use directly in procurement and channel plans. Those detailed splits and unit-level estimates are available in the full report and datasets for subscribers.
How to apply these insights in your 2026 roadmap
-
For procurement leaders: renegotiate supplier contracts to include certified-test pass-throughs and minimum traceability metrics; consider co-investment in apiary programs to secure multi-year flow.
-
For brand and category managers: refine SKU architecture to clearly separate premium, certified therapeutic propositions from mass-market spread products; align pricing with certification-backed claims.
-
For operations and QA: adopt a packaging-integrity audit cycle and mandate third-party testing for inbound lots; review recall preparedness given demonstrated recent incidents.
-
For corporate development teams: screen acquisition targets for certification pedigree, export approvals, and chain-of-custody robustness rather than headline volume alone.
Conclusion — a focused entry into a premium growth category
Manuka honey presents a compelling, mid-single-digit growth opportunity amplified by consumer preference for natural therapeutics and premium provenance. However, the pathway to durable commercial success in 2026 requires a disciplined blend of procurement sophistication, certification-led brand strategy, operational rigor, and regulatory alignment. PW Consulting’s full Manuka Honey Market study equips leaders with the empirical forecasts, operational tools, and competitive insights necessary to convert market momentum into defensible advantage. For teams preparing 2026 budgets and strategic plans, the difference between capturing outsized margin and conceding premium share will be how quickly and comprehensively they act on certification, supply security, and packaging integrity — all subjects the full report covers in actionable detail.
For detailed analysis of this topic, please visit the official page: Manuka Honey Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com