

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Aluminum Composite Panels Market Poised for 6.16% CAGR (2026–2032) — PW Consulting

Aluminum Composite Panels Market: Strategic Outlook for 2026 Decision‑Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise, decision‑focused introduction to our latest Aluminum Composite Panels (ACP) market study. This briefing surfaces the macro trends, competitive moves, and actionable implications that should inform capital allocation, commercial strategy, and supply‑chain planning in 2026 — while preserving the detailed segment‑level intelligence for the full report. Consider this a strategic trailer: rigorous, evidence‑based, and oriented to near‑term action, but intentionally high‑level on proprietary breakdowns so that stakeholders must access the full dataset for transactional implementation.
Aluminum Composite Panels Market
Market pulse and forecast framing
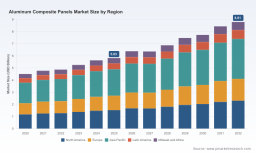
Our market modelling (base year 2025, historical window 2020–2025, forecast 2026–2032) shows the ACP market continuing a steady expansion driven by regulatory tightening, product innovation, and retrofit demand. Measured in USD (Billion), the industry expanded from approximately 4.5 in 2020 to about 5.8 in 2025 and — under the central forecast — reaches the mid‑single‑digit range in 2026 before progressing toward an expected market size of roughly 8.8 billion by 2032. The compound annual growth rate (CAGR) for the forecast horizon is 6.16%.
Aluminum Composite Panels Market
Why this matters for 2026: the market is large enough to sustain multiple business models (premium, compliance‑led, and cost‑competitive manufacturing), yet dynamic enough that a single regulatory or product innovation can re‑rate competitive positions quickly. The 6.16% CAGR and the distribution of growth across construction, retrofit, and specialty transport applications underline opportunities for manufacturers and material suppliers to capture structural margin improvement — provided they align product, certification, and channel strategies before demand shifts accelerate.
Aluminum Composite Panels Market
What the PW Consulting report delivers (practical tools inside)
- Market sizing and an auditable methodology spanning 2020–2032, with scenario variants tied to regulatory and raw‑material shocks.
- Demand driver mapping and a three‑scenario demand model (conservative, base, accelerated) that translates macro inputs to addressable revenue by product family.
- Supplier risk matrix and procurement playbook: aluminum exposure modelling, hedging levers, and recommended contract structures to protect margins.
- Regulatory compliance playbook: certification timelines, regional code comparators, and a go‑to‑certification roadmap for A2 and non‑combustible classifications.
- Commercial playbooks for OEMs and cladding contractors: channel economics, specification tactics, and conversion cost models.
- M&A and JV decision framework: valuation sensitivities, integration scorecards, and five archetypal consolidation targets.
- Implementation roadmaps with 6–18 month KPIs for product launches, certification sequencing, and supply‑chain reconfiguration.
Core dynamics shaping 2026 strategy
- Regulatory acceleration: Fire‑safety standards and product certifications are the single biggest short‑term commercial lever. Recent regulatory moves — including the extended compulsory certification for ACP in some markets and the emergence of A2 fire‑retardant cores — have shifted procurement specifications toward certified, non‑combustible solutions. Companies without rapid certification pathways face specification exclusion on major projects.
- Input cost volatility and pass‑through mechanics: Primary aluminum prices averaged near USD 2,600 per ton in early 2025, exhibiting intra‑year swings linked to production policy and geopolitical risk. In our cost model, metal content accounts for the majority share of panel input cost, making raw‑material strategy (hedging, local sourcing, value‑added alloy management) essential to margin protection.
- Product innovation and differentiation: Lightweight panels for transportation, higher performance fire‑resistant cores, and eco‑certified product lines (CE‑certified entrants enabling EU market access) are reshaping value propositions. Innovations that reduce weight or improve fire performance materially affect specification decisions in both infrastructure and mobile applications.
- Channel bifurcation: Project‑specification buyers (architects, large contractors) are increasingly driven by compliance and lifecycle cost, while signage and smaller contractors compete on lead time and price. The implication: companies need dual go‑to‑market capabilities — a compliance/systems approach for large projects and a fast‑turn commodity channel for signage and advertising segments.
Competitive landscape — strategic implications (what top players are signaling)
The market structure is neither atomized nor monopolistic: it supports national champions, specialized regional suppliers, and nimble innovators. Below are high‑level strategic reads on representative vendors based on public profiles and recent moves.
- Alucobond (United States) — a pioneer in metal facades that is increasingly leveraging product innovation (for example, ultra‑lightweight panels aimed at transportation) to create cross‑sector mobility opportunities. Strategy implication: incumbency in architecture combined with targeted product differentiation positions firms like Alucobond to capture premium margins when they can scale specialty products into adjacent sectors.
- ALPOLIC (Chesapeake, Virginia) — a leader in code‑compliant, recycled‑content ACM with demonstrated capability to certify products across multiple jurisdictions. Strategy implication: emphasis on recycled content and code compliance is an effective barrier to entry where procurement priorities include sustainability and regulatory compliance.
- Alfrex (USA) — integration of in‑house fire‑resistant core compounding and plate/coil coating options enables faster technical iterations and localized supply. Strategy implication: vertical integration around critical core technologies reduces time‑to‑market for certified offerings and is an efficient way to manage margin under cost pressure.
- Alumanate (USA) — focused on sign‑grade ACM with rapid manufacturing lead times; competitive where quick turnarounds and localized supply are primary buyer criteria. Strategy implication: speed and regional footprint can be used to defend pricing in lower‑differentiation segments.
- Aludecor (India) — demonstrates how emerging‑market players combine customization (color, finish) with fire‑rated options to serve highly price‑sensitive but regulation‑aware segments. Strategy implication: local customization and certification competency are prerequisites for market share in rapidly urbanizing markets.
Recent industry moves — for example, the launch of an A2 fire‑retardant core production facility in 2025, ultra‑lightweight product introductions, and expanded certifications for specialty composite systems in 2026 — reflect a broader trend: certification and product performance now directly translate to access on higher‑value projects.
Investment and commercial actions recommended for 2026
- Prioritize certification: accelerate A2 and non‑combustible pathways where your product roadmap allows, and build certification timing into go‑to‑market plans. Loss of specification access can be material and rapid.
- Hedge and diversify aluminum exposure: adopt layered procurement (combining term contracts, regional sourcing, and strategic inventory), and stress‑test pricing pass‑through clauses with typical project stakeholders.
- Segment product offering by buyer economics: deploy a dual strategy of compliance‑led premium products for architectural and infrastructure projects, and a commoditized offering optimized for signage/advertising where speed and cost matter more.
- Invest selectively in lightweight and transport‑grade panels if your manufacturing footprint can scale; weight reduction is a clear P&L lever for transportation OEMs and can unlock new contracts.
- Prepare M&A playbooks that prioritize technologies (FR core compounding, coil coating) and local manufacturing footprints to reduce lead times and import exposure.
Risk matrix: near‑term threats and mitigants
- Raw material price shocks — mitigate with multi‑tiered sourcing and hedging; model 20–30% price shock scenarios in capex plans.
- Regulatory lag or misalignment — maintain a certification task force and early engagement with notified bodies and code authorities.
- Specification capture risk from innovators — protect margins with faster NPD cycles and pilot partnerships with architecture firms and OEMs.
- Quality and counterfeit product risk in cost‑sensitive channels — enforce traceability, branded supply chains, and third‑party verification for high‑risk contracts.
Methodology transparency and what we intentionally withhold here
The full PW Consulting report contains the granular, client‑grade models and the segmented intelligence that underpins the strategic recommendations above: detailed regional and application breakdowns, product‑type level pricing curves, manufacturer revenue splits, and transaction‑ready supplier scorecards. In this briefing we deliberately show the market sizing trajectory, the 6.16% CAGR, and the high‑level strategic implications — but we have withheld the proprietary segment allocations and exact price curves to preserve commercial value for subscribers and potential advisory engagements.
Conclusion — what to do next in 2026
For executives making 2026 choices, the imperative is clear: align product certification, raw‑material strategy, and channel segmentation around the twin realities of rising regulatory thresholds and material cost volatility. Companies that move first to secure certified, demonstrably fire‑safe, and/or lightweight product offers — and that back that move with supply‑chain hedges — will capture the most valuable specification positions as the market expands toward the forecast horizon.
PW Consulting’s full report operationalizes these recommendations into implementation roadmaps, procurement templates, and valuation tooling. For teams preparing board briefs, M&A diligence, or a three‑year commercial plan, the complete dataset and models are available on our report page.
For detailed analysis of this topic, please visit the official page: Aluminum Composite Panels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com