

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Manuka Honey Market Poised for Growth at 5.98% CAGR Through 2032

Manuka Honey Market: Strategic Outlook for 2026 — A PW Consulting Preview
As supply chains reset, consumer health narratives evolve, and regulatory regimes tighten, Manuka honey stands at an inflection point. Our latest PW Consulting market study (base year 2025) synthesizes five years of historical dynamics, and projects performance through 2032 — providing the strategic context executives need to make high-stakes 2026 decisions. The global Manuka honey market reached a notable milestone in 2025 and, with a compound annual growth rate (CAGR) of 5.98% across the 2026–2032 forecast window, represents a commercially significant, premium food-and-health ingredient category for brand owners, ingredient buyers, and investors.
Manuka Honey Market
Why this study matters for 2026 planning
-
It translates macro momentum into boardroom-relevant scenarios. The market’s steady mid-single-digit CAGR masks critical inflection points — scarcity-driven price pressure, certification-driven premiumization, and a channel shift toward health-first e-commerce — that will determine winners and losers in 2026.
Manuka Honey Market -
It isolates operational levers. Given constrained floral supply and increasingly exacting export controls, decisions on sourcing, vertical integration, and packaging resilience will materially affect margins and access to high-value markets.
Manuka Honey Market -
It aligns go-to-market choices with compliance reality. Regulatory enforcement and independent certification regimes are now de facto market access requirements in several markets; the study maps the interaction between certification, testing regimes, and commercial positioning.
Market trajectory — the headline view
From a clear 2025 baseline, the market is forecast to expand at approximately 5.98% CAGR over the 2026–2032 period. That pace is indicative of a mature premium niche that benefits from sustained consumer interest in natural therapeutics and functional foods, while being moderated by raw-material constraints and regulatory friction. For commercial strategists, the implication is that organic top-line growth remains available, but it must be harvested through precision moves — not broadscale volume plays.
Core dynamics shaping strategy
-
Premiumization and trust: Consumers continue to pay a premium for verified potency and provenance. Certification schemes (e.g., established methylglyoxal-based verification systems) now underpin product credibility. Brands without robust traceability face uphill battles in premium channels.
-
Supply-side scarcity and raw-material cost inflation: Tight floral supply windows and concentrated production geographies create periodic price spikes and procurement risk. Market signals in late 2025 showed wholesale raw material prices at elevated levels, reinforcing the need for multi-year supply agreements and inventory strategies.
-
Regulatory and certification gatekeeping: Export and labeling regimes have hardened. Authoritative testing definitions and recognized laboratory networks are prerequisites for meaningful access to key markets. Compliance is no longer just legal hygiene — it is a commercial enabler.
-
Channel bifurcation: Traditional retail remains important for mainstream penetration, but premium and therapeutic propositions are migrating toward direct-to-consumer and health-channel models where storytelling, certification, and consumer education drive conversion.
-
Product innovation beyond jars: Encapsulated nutraceuticals, skincare formulations, and combined functional-ingredient offerings are expanding the addressable market, but each application introduces distinct margin and regulatory profiles that require tailored strategies.
Competitive landscape — concentrated but evolving
The Manuka honey ecosystem is characterized by a moderate level of concentration: a small group of established players controls a meaningful share of supply and certification-recognized inventory, while a broader field of regional producers and new entrants competes on niche differentiation. This concentration creates both stability and chokepoints: stable supply from integrated leaders, but risk of access constraints for downstream buyers.
Key archetypes we profile in the study include:
-
Vertically integrated leaders with traceability crowns — companies that control hive-to-shelf processes and have invested heavily in independent testing and quality assurance. Their strategic advantage lies in predictable supply, recognized certification, and premium pricing power.
-
Specialist organic and clean-label innovators — producers focused on certified organic lines, clean-label processing, and wellness formulations. Their success hinges on authenticity narratives and channel partnerships in natural health retail.
-
Regional exporters and authenticity challengers — firms that leverage national authenticity marks to penetrate export markets, often competing on price-performance or specific certification endorsements.
Recent industry developments underscore these dynamics. A major industry participant initiated a voluntary recall in 2025 tied to packaging integrity, highlighting how operational minutiae can cascade into reputational and distribution risk. Conversely, recognition of an Australian producer for export excellence and official updates to approved exporter lists in late 2025 demonstrate that regulatory alignment and export credentials remain decisive commercial assets.
Strategic implications for 2026 decision cycles
-
Sourcing and procurement: Move from transactional buying toward contracted supply with quality- and compliance-linked SLAs. Scenario planning should assume periodic raw-material tightness and incorporate hedging, vertical partnerships, and co-investment in apiary management.
-
Portfolio management: Distinguish between therapeutic-grade SKUs that command margin and mainstream SKUs that drive volume. Allocate R&D and marketing spend to SKUs where certification and evidence-based claims create defensibility.
-
Regulatory playbook: Invest in recognized certification and MPI/AMHA-compliant testing pathways early. For exporters, ensuring facilities and processes are on approved lists materially reduces time-to-market and trade friction.
-
Operational resilience: Packaging integrity and cold-chain/handling controls are not mere cost centers; recent recall activity shows they are core to continuity. Quality assurance programs should extend to co-packers and contract manufacturers.
-
M&A and partnerships: The market’s concentration profile makes bolt-on acquisitions and supply agreements attractive for fast access to certified inventory. But diligence should prioritize chain-of-custody, lab-test history, and export credentials over headline production volumes.
Risk matrix — what to watch in 2026
-
Authenticity and testing disputes: Independent lab validation and defensible chain-of-custody documentation are essential to mitigate litigation and market rejection.
-
Biosecurity and cross-border controls: Import permits and species-specific biosecurity checks can introduce delays and unexpected costs for cross-jurisdictional supply.
-
Operational slip-ups: Packaging failures or labeling non-conformances can trigger recalls with outsized commercial impact in premium categories.
-
Price volatility: Periodic raw-material cost surges require commercial models capable of absorbing temporary margin compression without brand damage.
What PW Consulting’s full report delivers (actionable highlights)
Our study is structured for executive decision-making and includes pragmatic tools and deliverables designed for rapid implementation:
-
Market sizing and forward-looking scenarios (base year 2025; forecast to 2032) with sensitivity analysis across supply and demand shocks.
-
Competitive profiles and capability mapping for the leading producers, focusing on traceability, certification, vertical integration, and channel reach.
-
Regulatory and certification playbooks for major export markets, including lab-recognition matrices and practical compliance checklists.
-
Commercial playbook templates — sourcing contracts, inventory hedging models, and premiumization positioning frameworks tailored for CPG and ingredient buyers.
-
Operational risk checklists covering packaging, co-packer oversight, recall readiness, and lab-test governance.
-
Deal rationales and valuation comparables for M&A activity, alongside a prioritized list of strategic targets and partnership archetypes.
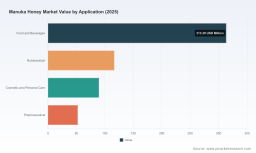
Note: this preview intentionally omits the granular region-by-region and application-level tables that many corporates use directly in procurement and channel plans. Those detailed splits and unit-level estimates are available in the full report and datasets for subscribers.
How to apply these insights in your 2026 roadmap
-
For procurement leaders: renegotiate supplier contracts to include certified-test pass-throughs and minimum traceability metrics; consider co-investment in apiary programs to secure multi-year flow.
-
For brand and category managers: refine SKU architecture to clearly separate premium, certified therapeutic propositions from mass-market spread products; align pricing with certification-backed claims.
-
For operations and QA: adopt a packaging-integrity audit cycle and mandate third-party testing for inbound lots; review recall preparedness given demonstrated recent incidents.
-
For corporate development teams: screen acquisition targets for certification pedigree, export approvals, and chain-of-custody robustness rather than headline volume alone.
Conclusion — a focused entry into a premium growth category
Manuka honey presents a compelling, mid-single-digit growth opportunity amplified by consumer preference for natural therapeutics and premium provenance. However, the pathway to durable commercial success in 2026 requires a disciplined blend of procurement sophistication, certification-led brand strategy, operational rigor, and regulatory alignment. PW Consulting’s full Manuka Honey Market study equips leaders with the empirical forecasts, operational tools, and competitive insights necessary to convert market momentum into defensible advantage. For teams preparing 2026 budgets and strategic plans, the difference between capturing outsized margin and conceding premium share will be how quickly and comprehensively they act on certification, supply security, and packaging integrity — all subjects the full report covers in actionable detail.
For detailed analysis of this topic, please visit the official page: Manuka Honey Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com