

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Period Panties Market to Reach USD 321.7M by 2032 (7.05% CAGR)

Period Panties Market 2026: Strategic Preview and Decision Framework
Introduction — Why this moment matters
The period panties market has moved beyond niche novelty to become a calculated strategic frontier for consumer health, intimate apparel, and sustainable personal-care portfolios. Between rising consumer preference for reusable solutions, tightening regulation on product chemistries, and clear indications of steady demand growth, 2026 will be a pivotal year for companies deciding whether to scale, specialize, partner, or exit. This short-form briefing previews PW Consulting’s full Period Panties Market study and highlights the practical, decision-grade intelligence executives will need to act confidently in 2026.
Period Panties Market
Market snapshot: scale, trajectory, and what it means for 2026 planning
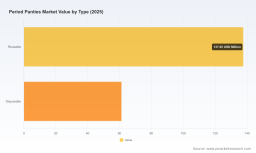
At a macro level, the market has demonstrated consistent expansion over the past half-decade and is on a trajectory that supports continued investment. From our report’s base-year perspective (2025), total industry revenues rose meaningfully since 2020 and are forecast to continue expanding through 2032 at a compound annual growth rate of approximately 7.05%. By the end of the forecast horizon the market is expected to be materially larger than it is today, reflecting both unit growth (adoption and usage frequency) and premiumization (higher-value SKUs and adjacent-service monetization).
Period Panties Market
For corporate planning, that growth profile translates into three strategic realities for 2026: (1) sufficient market momentum exists to justify new product development and channel expansion; (2) margin expansion is achievable for brands that systemically address sustainability and regulatory risk; and (3) scale remains a differentiator—but not an absolute barrier—to entry for focused challengers with clear positioning.
Period Panties Market
What the full report delivers — practical, operational intelligence
- Quantified demand trends and revenue forecasts across 2020–2032 with scenario analysis calibrated to regulatory and material-cost shocks.
- A dynamics module that maps the most consequential non-market forces (regulatory updates, ingredient bans, and sustainability innovations) to impact timelines and P&L exposures.
- Go-to-market playbooks tailored for incumbents, direct-to-consumer challengers, and private-label manufacturers — including channel mixes, promotional ladders, and price-pack architecture examples.
- SKU-level product roadmaps: material trade-offs, cost-to-serve models for reusable vs. disposable offerings, and laundering/aftercare positioning that improve retention.
- Supply-chain and sourcing maps that identify critical raw-material nodes, alternate suppliers, and strategic inventory levers to mitigate ingredient constraints.
- Competitive profiles and M&A screens with playbooks for partnerships, licensing, and bolt-on acquisition targets.
- Consumer segmentation and behavioral models that marry attitudinal data to actual purchase flows—actionable for marketing and product teams.
Competitive landscape — players, capabilities, and likely next moves
The competitive field is populated by digitally native brands with differentiated product engineering, legacy intimates brands expanding into the category, and a growing number of regionally focused challengers. Leading players are building defensible positions along four vectors: absorbency and fit engineering, material provenance and sustainability claims, inclusive sizing and gender positioning, and channel mastery (DTC subscription vs. retail partnerships).
- Saalt: Known for leakproof engineering and long-wear claims; positioned to leverage patent-backed gusset technology in both direct channels and clinical-adjacent partnerships.
- Knix: A high-volume North American leader with strong brand equity and SKU breadth; will likely invest in premium and youth-facing sub-brands to protect growth.
- Thinx: Differentiated on performance claims and youth outreach; a candidate to expand into adjacencies (postpartum, incontinence) while protecting core anti-leak IP.
- Modibodi: Early mover on reusable technical linings and multi-layer systems; best placed to exploit sustainability-driven premiumization and international channel expansion.
- Rael, Ruby Love, The Period Company, TomboyX: Each brings specific strengths—from organic-material positioning and teen sizing to gender inclusivity and price accessibility—that make them attractive acquirers or acquisition targets depending on strategy.
Strategic implication: 2026 will favor brands that convert technical performance into clear consumer value propositions (e.g., “12-hour protection” backed by test protocols), while also demonstrating a defensible supply chain and regulatory awareness.
Regulatory, material and consumer dynamics shaping near-term strategy
- Regulatory posture: Recent clarifications and amendments to product classification and labeling have raised the compliance floor for manufacturers. A notable development is the regulatory framing that situates many period panties under medical-device rules with lower premarket burdens for routine products; parallel state-level actions have introduced specific ingredient restrictions and disclosure demands.
- Ingredient constraints and disclosure: Several U.S. states have enacted restrictions (including PFAS bans in menstrual products) that materially affect formulation choices and supplier sourcing. California’s continuing rollout of mandatory disclosure of intentionally added ingredients has increased due-diligence and labeling costs for multi-jurisdictional players.
- Sustainability & circularity: Innovations in compostable fabrics and extended-lifetime reusable constructions (including recent commercial partnerships to bring high-compostability product lines to market) are reshaping product development roadmaps. These developments create both premiumization opportunities and operational trade-offs (e.g., durability vs. compostability).
- Consumer preference shift: Empirical market signals show consumers increasingly favor reusable solutions for cost and environmental reasons, but adoption hinges on perceived convenience, hygiene claims, and trust in care instructions—areas where brands can establish durable differentiation.
Practical strategic moves for 2026 (what should leadership teams do now)
- Prioritize regulatory-compliant reformulation and labeling roadmaps: Build a cross-functional regulatory & procurement task force to de-risk PFAS exposure and to prepare for expanding ingredient disclosure requirements. Map alternative suppliers and secure multi-year contracts for critical technical textiles.
- Invest in third-party validation & transparent testing: Convert performance claims into retailable trust—independent lab validation of absorbency and leakproof duration will be a purchase driver and a defensive asset in retail listings and marketplaces.
- Segment the product portfolio by usage occasions: Create clear, monetizable tiers (light, moderate, heavy/postpartum, overnight) and tie retention programs to laundering guidance and subscription models to increase LTV.
- Pursue partnerships that extend lifecycle narratives: Link compostable or long-life product lines with retrofit services (e.g., take-back, recycling) or third-party composting partnerships to credibly claim circularity without sacrificing durability for heavy-use segments.
- Channel and pricing playbook: Test hybrid go-to-market models that blend DTC subscription economics with selective retail distribution to reach discovery customers while protecting margin and data capture for direct channels.
- M&A and partnership scouting: Target capability buyouts (materials science, testing labs, or regional logistics) rather than revenue acquisitions if your priority is speed-to-market on safer formulations and scale efficiencies.
Commercial execution levers — quick wins versus structural investments
- Quick wins (0–12 months): Launch targeted performance-validated SKUs for high-intent cohorts; publish ingredient disclosures and lab results prominently; roll out targeted digital acquisition with educational content on care and sustainability.
- Structural investments (12–36 months): Reengineer supply contracts for PFAS-free components, invest in proprietary absorbent linings or licensing agreements, and build post-sale services (subscriptions and take-back programs) that increase customer lifetime value.
Competitive monitoring — what to watch in 2026
Track the following near-term signals: large retailers’ private-label moves into reusable period wear, new regulatory clarifications at federal and state levels, patent filings on absorbent linings, and a wave of partnerships aimed at compostability claims. We also expect to see increased cross-category bundling (e.g., period panties + subscription menstrual-care kits) as brands chase share of wallet.
Methodology note and the “trailer” to the full report
PW Consulting’s full study synthesizes historical sales data, primary interviews with manufacturers, retailers and distributors, consumer-panel behavioral microdata, and materials-cost modeling. The report provides granular segmentation, regional and application-level breakdowns, competitive share models, and scenario-based P&L impacts under multiple regulatory and input-cost permutations. In keeping with the practice of prompting informed commercial engagement, this preview omits the proprietary segment-level shares, SKU-level elasticity matrices, and transaction-level pricing models that constitute the report’s core deliverables.
Final word — how to use this preview to set 2026 priorities
Use this briefing to align your executive questions: Are you a product-first brand that should accelerate technical validation and premiumization? Are you a cost-focused manufacturer seeking entry via private label? Or are you a retailer evaluating captive-brand economics versus partnering with branded innovators? The full PW Consulting Period Panties Market report turns the high-level signals summarized here into executable roadmaps, valuation-grade forecasts, and negotiation playbooks tailored to each decision profile. For teams making budget, M&A, or R&D commitments in 2026, that operational intelligence will materially shorten time-to-decision and lower execution risk.
For detailed analysis of this topic, please visit the official page: Period Panties Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com