

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: NMR Spectrometer Market to reach USD 1,712M by 2032 at 5.35% CAGR

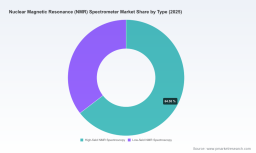
Nuclear Magnetic Resonance (NMR) Spectrometer Market — Strategic Briefing for 2026 Decisions
Executive summary
The NMR spectrometer market is transitioning from an instrument-centric, research-dominated landscape to a digitally integrated, application-driven industry that directly supports regulated manufacturing and distributed analytical workflows. Our PW Consulting baseline analysis (base year 2025) sizes the global market at USD 1,203 Million and projects steady expansion at a compound annual growth rate (CAGR) of 5.35% across the 2026–2032 forecast window, reaching an anticipated market value in the early 1700s (USD Million) by the end of the period. That trajectory reflects a dual trend: continued investment in ultra-high-field research instruments and rapid adoption of benchtop, cryogen-free, and AI-enabled platforms across pharma, industry QC, and applied research.
Nuclear Magnetic Resonance (NMR) Spectrometer Market
Why this report matters for 2026 strategic planning
-
Investment timing and sizing — The market’s mid-single-digit CAGR signals a stable growth environment where well-timed CapEx and R&D bets can secure disproportionate advantage. Organizations deciding now on lab refresh cycles, manufacturing analytics investments, or vendor consolidation need data-driven scenario framing to avoid both under- and over-investment.
Nuclear Magnetic Resonance (NMR) Spectrometer Market -
Regulatory alignment — Accelerating regulatory acceptance of NMR for identity and purity, and frameworks that favor in-line and at-line analytics in continuous manufacturing, transform NMR from a “nice-to-have” research tool into a core process control technology for life sciences manufacturers.
Nuclear Magnetic Resonance (NMR) Spectrometer Market -
Vendor and technology bifurcation — The market is increasingly segmented by capability: very-high-field systems serving frontier research and structure elucidation, versus compact, integrated solutions for QC, PAT, and decentralized laboratories. Strategic buyers must balance performance needs, total cost of ownership (TCO), and lifecycle service architecture.
-
Concentration dynamics — Market concentration data indicate that leading vendors hold a material share of revenues, but the industry remains contestable for innovative entrants focused on cryogen-free magnets, portability, AI-assisted interpretation, and LIMS/ERP integration.
Core market movements and regulatory drivers
A confluence of technical and regulatory forces is reshaping demand patterns. Pharmaceutical regulators are increasingly comfortable with NMR-based identity and purity testing and are building frameworks that nudge manufacturers toward PAT-enabled continuous operations. Simultaneously, instrument manufacturers are delivering innovations—higher accessible fields, room-temperature shimming, cryogen-free permanent magnets, and AI-assisted spectral interpretation—that lower operational barriers for non-specialist users.
Consequence for buyers: procurement decisions must now be evaluated along three axes simultaneously—analytical performance, integration-readiness (digital and process), and regulatory evidence. Benchtop systems that once targeted teaching labs are now being validated for GMP environments; conversely, ultra-high-field players are differentiating on capability to support increasingly complex molecular characterization challenges.
What the PW Consulting report delivers (practical, decision-ready content)
-
Market sizing and forecast model (2020–2032): a transparent, testable model with scenario toggles for adoption velocity, pricing pressure, and service margins. High-level historical figures and forward curves anchor board-level investment planning.
-
Buyer’s decision framework: TCO calculators, procurement scorecards, and a decision matrix that maps use-cases (R&D, QC, PAT, education) to appropriate instrument classes and service models.
-
Vendor benchmarking and strategic profiles: qualitative and quantitative assessments of major vendors’ strengths, product roadmaps, go-to-market models, and service footprints—sufficient to shortlist suppliers and structure RFPs without revealing detailed vendor financials.
-
Regulatory and validation playbook: a risk matrix linking regulatory trends (including controller frameworks for continuous manufacturing) to validation requirements, audit readiness, and documentation templates.
-
Integration blueprints: practical templates for LIMS/ERP connectivity, edge data capture for PAT, and sample case studies showing how benchtop NMR deployments were staged into multi-site manufacturing networks.
-
Commercial levers and negotiation toolkit: guidance on service bundling, cryogen-management clauses, spare-parts strategies, and maintenance SLAs tailored to different operating models.
-
Deal and M&A intelligence: a shortlist of capability gaps where bolt-on acquisitions make sense (e.g., AI spectral interpretation, cryogen-free magnet platforms, or supply-chain-critical component suppliers) including integration playbooks for buyers.
Competitive landscape — who matters and why
The competitive map includes well-established high-field leaders and a set of agile specialists commercializing compact, low-maintenance platforms. Key firms covered in the report include:
-
Bruker Corporation — a market leader with deep offerings across high-field and benchtop lines; continues to push field boundaries with commercial delivery of flagships that extend research capability.
-
JEOL Ltd. — a high-performance instrument vendor advancing strategies around reduced cryogen dependency and room-temperature shim technologies to lower operating cost for research customers.
-
Magritek Ltd. — a focused innovator in benchtop systems delivering high sensitivity and cryogen-free operation, appealing to decentralised labs and education environments.
-
Oxford Instruments plc — positions itself at the intersection of benchtop convenience and research-level quality, adding AI-assisted workflows to broaden user bases.
-
Anasazi Instruments, Inc. — targets educational and industrial users with permanent-magnet offerings and simplified operational footprints.
-
Nanalysis Scientific Corp. — a portable and benchtop specialist enabling immediate availability and operational simplicity without cryogens.
-
Thermo Fisher Scientific Inc. — leverages broad commercial reach to place routine benchtop platforms in teaching and standard analytical roles.
Recent product and installation moves—ranging from the commercial delivery of unprecedented high-field instruments to launches of AI-assisted benchtop systems and room-temperature shimming platforms—underscore a two-front competitive dynamic: performance-led differentiation at the high end, and operational simplicity + integration at the benchtop/field end.
Strategic implications and recommended actions for 2026
-
Adopt a use-case-first procurement posture. For QC and PAT, prioritize compact, integrated systems with validated digital pipelines and lower TCO; for frontier R&D, map required spectral performance and reserve budget for higher-field instruments.
-
Embed regulatory-readiness into vendor selection. Insist on validated workflows, audit-trail capabilities, and demonstrable evidence of regulatory acceptance for intended use (identity/purity or PAT).
-
Design for multi-vendor resilience. Given the mix of dominant suppliers and nimble specialists, structure supply agreements to protect uptime and spare-parts availability while preserving optionality for future innovation adoption.
-
Invest in digital integration early. Prioritise systems with native LIMS/ERP connectors and cloud/edge architectures to accelerate PAT implementations and consolidate analytical datasets for lifecycle analytics.
-
Quantify cryogen exposure in total cost models. Cryogen-free innovations materially shift operating economics—buyers should model scenarios that include cryogen supply disruption and service variability.
-
Pursue targeted M&A or partner strategies to fill capability gaps—particularly in AI-assisted interpretation, portable magnet technology, and field-service networks.
-
Run a staged deployment: pilot benchtop platforms in QC labs and scale to manufacturing lines once integration and validation lessons are assimilated—this limits program risk while accelerating benefit realization.
How to use the full PW Consulting report
This article previews the strategic framing and top-line market trajectory for executives making 2026 decisions. The full PW Consulting NMR market research suite provides the granular intelligence required to act: downloadable forecast models, vendor scorecards, procurement templates, regulatory validation checklists, and installation case studies that disclose lessons learned and measurable KPIs. Those materials are designed to turn strategy into executable programs—without exposing sensitive segmentation tables in this teaser.
If your organization is planning lab modernizations, PAT rollouts, or acquisition screening in 2026, use this briefing as the framing document for internal alignment, then consult the full report for the detailed inputs and models required to finalize budgets, RFPs, and integration plans.
For detailed analysis of this topic, please visit the official page: Nuclear Magnetic Resonance (NMR) Spectrometer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com