

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
High Speed Doors Market to Reach USD 1,889.4M by 2032 with 6.7% CAGR — PW Consulting

High Speed Doors Market: A Strategic Preview for 2026 Decision-Makers
As global industrial flows accelerate and hygiene, energy efficiency, and throughput expectations tighten, high speed doors have moved from commoditized accessories to strategic assets across logistics, cold chain, manufacturing, and regulated food and pharmaceutical environments. This preview introduces PW Consulting’s 2026 market study (base year 2025), summarizing the rigorous analysis and practical toolsets that senior executives, M&A teams, product leaders, and procurement heads need to convert market signals into defensible decisions.
High Speed Doors Market
Snapshot — Why this research matters in 2026
-
Market scale and trajectory: The high speed doors market reached a material size in our 2025 base year and is forecast to expand at a mid-single-digit CAGR through the 2026–2032 horizon. That growth reflects a combination of logistics modernization, regulatory-driven replacement cycles, and incremental automation investments.
High Speed Doors Market -
Decision cadence: For 2026 planning cycles—capital allocation, product roadmaps, plant upgrades, and M&A diligence—granular, forward-looking market intelligence is no longer optional. It is the foundation for prioritizing bets and sizing opportunities.
High Speed Doors Market -
Operational impact: High speed door choices influence energy budgets, throughput metrics, safety incidents, and hygiene compliance; the right specification reduces operating expenditure and operational risk, the wrong one multiplies retrofit costs and service headaches.
What PW Consulting’s report delivers (practical, executable)
-
Market sizing & forecast model (base year 2025, outlook through 2032) with scenario variants and sensitivity toggles for macroeconomic and raw-material shocks.
-
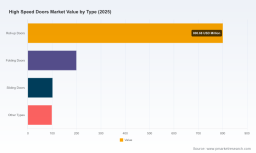
Segmentation architecture (by product type, application, and region) linked to buyer personas and procurement decision rules. Note: this preview highlights directionality and drivers; detailed split tables and downloadable datasets are included in the full report.
-
Regulatory and standards matrix mapping compliance triggers (safety, hygiene, lift-systems) to spec sheets and validation checklists usable by engineering teams and third-party certifiers.
-
Supplier and competitor playbooks — capabilities mapping, go-to-market footprints, and service-network overlays to accelerate partner selection or M&A screening.
-
TCO and ROI toolkits: energy, throughput, maintenance, and downtime models that quantify payback under different operating regimes.
-
M&A and inorganic growth frameworks: target archetypes, valuation touchpoints, integration checklists, and post-deal value-capture roadmaps.
-
Commercial annexes: RFP templates, technical acceptance criteria, aftermarket SLAs, and implementation checklists for pilot-to-scale rollouts.
Market dynamics — the data-driven story
Between 2020 and 2025 the market expanded meaningfully as warehouse automation and refrigerated logistics continued to push demand for faster, tighter-sealing door systems. Our modeling, built from a combination of public disclosures, company filings, primary interviews, and installer intelligence, shows sustained expansion into 2032, with the market expected to approach roughly one-and-a-half times its 2025 scale under the base case. The implied compounded annual growth is in the mid-single digits, driven by both retrofit cycles and new-build demand.
Growth is not uniform. Three structural trends explain where and why demand concentrates: (1) throughput and energy economics — faster door cycles and better seals materially shrink heat transfer and pressure differentials, directly improving operational efficiency; (2) regulatory and product safety requirements — evolving standards compel upgrades or replacement, particularly in food, pharma, and cold-chain locations; and (3) automation and connectivity — integration with WMS/ASRS systems raises the value of doors that offer predictable, fast, and safe operation.
Material and standards dynamics are shaping product roadmaps. Fabric curtains—increasingly reinforced polyester and PVC blends—are now the primary curtain materials, selected to reduce energy loss and simplify maintenance. Steel and aluminum subcomponents remain broadly available, albeit with higher emphasis on corrosion-resistant coatings for exterior use. From a compliance standpoint, manufacturers and end users must navigate a denser standards environment: recent updates to DASMA specifications and lifting-cable guidance, European TÜV SÜD / DGUV safety regimes that mandate frequent automatic checks and collision compensation measures, and sector-specific mandates (e.g., FDA-compatible materials for food processing). These regulations convert into purchase drivers and upgrade obligations for facility owners and facility engineering teams.
Competitive landscape — capabilities, not just logos
The market remains moderately fragmented—leading players capture a meaningful share but a long tail of regional specialists and installers persist. The top-three and top-five concentration metrics indicate room for consolidation alongside healthy regional competition. Understanding capability clusters is more important than headline names when evaluating partners or acquisition targets.
-
North American specialists: Several U.S.-based firms excel in engineered roll-up and fabric high-speed systems optimized for cold storage and high-throughput logistics. These vendors typically differentiate through advanced sealing, automation integration, and extensive service networks—critical for customers prioritizing uptime.
-
European engineering leaders: Select European manufacturers combine high mechanical speeds with stringent safety and cycle-life guarantees, appealing to logistics operators and OEMs demanding long service life and compliance with strict local safety rules.
-
Chinese OEMs and exporters: Cost-competitive solutions for large-volume warehouses and standard applications, increasingly offering CE/UL-certified options and emphasizing low-maintenance spiral systems for logistics parks and third-party logistics providers.
-
Product innovation vectors: Patented reinsert technologies, soft-edge safety features, auto re-feed systems, and spiral door architectures provide functional differentiation. Producers who couple mechanical reliability with digital telematics for predictive maintenance will extract higher aftermarket revenue per installed door.
Recent market moves underscore these dynamics: a leading North American manufacturer staged live spiral-door demonstrations at major 2026 trade events to showcase integration capabilities, while an Asian supplier published updated product guides emphasizing “zero-maintenance” spiral architectures and smart logistics integrations. These activities reflect the dual priorities of demonstrable operational superiority and an accelerated push into system-level offerings.
Strategic implications — a 2026 playbook
-
For incumbents: Prioritize modular platforms that support rapid field configurability and telematics-enabled aftermarket services. Invest selectively in compliance-testing and certification labs to shorten sales cycles with regulated buyers.
-
For challengers and new entrants: Target vertical niches (e.g., food-grade environments, cold-chain micro-distribution) where technical spec complexity raises barriers to low-cost competitors. Offer bundled service agreements to lock in recurring revenue.
-
For private equity and corporate M&A teams: Screening should emphasize service footprints, digital aftermarket capabilities, and regional channel strength. Small bolt-ons that add installer networks or certification competencies often deliver outsized integration synergies.
-
For procurement and supply chain leaders: Hedge fabric and polymer exposure and qualify multiple steel-coating suppliers to reduce retrofit lead times. Incorporate regulatory-compliance clauses and test-acceptance milestones into contracts.
-
For operations and engineering teams: Run targeted pilots that measure energy savings, seal performance, and cycle reliability in live conditions. Use TCO models to compare replacement vs. retrofit across the installation population.
Risk radar — what to monitor in 2026–2028
-
Regulatory tightening in safety and hygiene standards that could accelerate replacement cycles and raise compliance costs.
-
Raw material price volatility for polymers and coatings that impacts margins for standard models.
-
Service-network shortages in tight labor markets, raising aftermarket SLA fulfillment risk.
-
Cyber and connectivity risks as doors become integrated with building and logistics control systems—security must be a specification item, not an afterthought.
-
Trade policy shifts that affect cross-border supply of certified doors and components.
How PW Consulting’s study unlocks commercial value
This research blends a quantitative forecasting engine with qualitative, practitioner-focused guidance. Subscribers receive: interactive forecast models, a prioritized list of actionable initiatives tied to near-term ROI, detailed supplier capability matrices, regulatory compliance playbooks, and commercially ready annexes (RFP templates, acceptance tests, and TCO calculators). Crucially, the report balances top-down market sizing with bottom-up installer and OEM intelligence so decision-makers can align capital allocation with measurable operational benefit.
We intentionally hold back the detailed, tabulated segment splits in this preview. That granular intelligence—region-by-region and application-by-application sizing, competitive shares at product-family level, and downloadable datasets—is included in the full PW Consulting deliverable and is designed to plug directly into your financial models and procurement pipelines.
Next steps for leaders
-
Use the preview to align executive hypotheses for 2026 planning; then deploy the full dataset to stress-test capex, product, and M&A scenarios.
-
Commission a short, custom workshop with PW Consulting to map the report’s findings to your portfolio and to co-create a 6–12 month prioritized implementation plan.
-
Adopt a staged pilot approach: validate energy and throughput claims on two representative sites before committing to multi-site rollouts—use our TCO templates to quantify payback.
In sum, the high speed doors market in 2026 sits at the intersection of operational efficiency, safety regulation, and digitally-enabled service economics. Strategic clarity—grounded in reliable forecasts, standards-aware product specifications, and realistic aftermarket assumptions—turns opportunities embedded in a growing market into durable advantage. PW Consulting’s full report supplies the granular intelligence and executable toolkits you will need to make those decisions with confidence.
For detailed analysis of this topic, please visit the official page: High Speed Doors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com