

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Programmable Power Supply Market to Reach USD 344.8M by 2032 at 6.98% CAGR

Programmable Power Supply Devices: Strategic Intelligence for 2026 Decision-Making
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a forward-looking synthesis of the Programmable Power Supply Device market designed to inform executive choices in 2026. This analysis combines macro growth signaling, competitive motion, regulatory and supply-side dynamics, and the practical, executable insights that senior leaders and product strategists require—without divulging the granular segmentation that is preserved for the full report.
Programmable Power Supply Device Market
Why this market matters in 2026
The programmable power supply market is no longer a niche instrumentation category: it sits at the intersection of industrial automation, battery validation, semiconductor capital equipment, and advanced test & measurement. Our industry modeling (base year 2025) shows a resilient expansion path, with the total market scaling notably through the historical period and continuing at a compound annual growth rate of 6.98% across the 2026–2032 forecast window. That trajectory reflects both rising unit complexity (multi‑function digital platforms) and stronger average selling prices where high-voltage, bidirectional, and digitally integrated supplies are required.
Programmable Power Supply Device Market
Market trajectory: what the headline numbers tell you
- Momentum: The market demonstrated steady recovery and growth through the early 2020s and reached a clear inflection by 2025. The growth profile implied in our forecasts favors technology-differentiated offerings (digital control, higher power density, bidirectionality) and sectors undertaking large-scale electrification projects.
- Outlook: Near‑term demand drivers are pragmatic—battery gigafactory validation, semiconductor fab expansions, and automotive electrification testing. Longer‑term upside is tied to increasingly software-defined test workflows and on‑site power systems for new energy infrastructures.
- Concentration: Competitive structure remains fragmented relative to classic power electronics incumbencies; the top few firms together account for a modest share of the market, leaving substantial runway for innovation, specialization, and M&A-driven consolidation.
Strategic implications for 2026 corporate decision-makers
Executives planning product roadmaps, procurement strategies, or M&A activity should treat the programmable power segment as a strategic enabler rather than a cost center. The clear implications we draw from the data are:
Programmable Power Supply Device Market
- Prioritize software and systems integration. Buyers increasingly prize platforms that integrate power control, data telemetry, and automated test sequencing. Suppliers that expose APIs and support edge-to-cloud telemetry will win larger, longer contracts.
- Differentiate on safety and standards compliance. IEC compliance and RoHS 3 alignment are table stakes for industrial and laboratory deployments; plans that bake regulatory certainty into product lifecycles see faster adoption among OEMs and test labs.
- Assess supply-chain resilience beyond commodity pricing. Raw material sourcing—especially semiconductors and key passive components—remains geographically concentrated. Strategic sourcing, multi-supplier qualification, and localized manufacturing footprints are credible hedges against disruption.
- Monitor cost‑competition while defending high-value niches. Competitive pressure from lower-cost suppliers has intensified in commodity power ranges. Western suppliers can offset margin erosion by leaning into high-voltage, high-reliability, and custom-system segments or by pursuing strategic partnerships and selective consolidation.
What our report delivers: actionable, operational intelligence
This research is crafted for executives who must convert market insight into actions in 2026. The full deliverable contains:
- Validated market sizing and trend models (historical analysis 2020–2025; forecast 2026–2032) to stress-test business plans and revenue scenarios.
- Use-case led demand matrices that map platform capabilities (e.g., bidirectionality, high-voltage, density, digital controls) to buyer personas in battery testing, semiconductor fabs, industrial automation, and lab procurement.
- Go-to-market playbooks for suppliers, including channel models, pricing sweet spots, and after-sales service design that capture lifetime value in capital equipment deployments.
- A disciplined M&A screen that identifies targets by capability gaps (digital controls, high-voltage design, localized manufacturing) rather than by headline revenues, reducing integration risk and accelerating cross-sell potential.
- Risk and mitigation frameworks tied to raw-material concentration, compliance timelines, and competitive pricing dynamics—structured for immediate board-level decision-making.
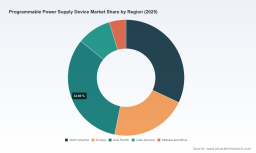
Note: the full report includes detailed regional and application splits and the granular quantitative tables that underwrite the conclusions above. Those segmentation tables are intentionally withheld here to encourage access to the full intelligence package.
Competitive landscape — who to watch and why
The market’s competitive topology is an interplay of global incumbents, specialized system integrators, and nimble innovators. The following profiles capture players whose recent moves are shaping buying criteria and market structure:
- TDK-Lambda Americas Inc. (New York, USA): Known for high-power GENESYS DC programmable supplies and the newer GENESYS AC series, TDK‑Lambda is strengthening its industrial and automotive test bench relevance through modular, high‑power solutions suitable for aerospace and renewable testing.
- AMETEK Programmable Power (United States): With precision AC/DC programmable supplies, electronic loads, and systems (Asterion, Mi‑BEAM, i‑BEAM), AMETEK is deepening its position in battery testing and compliance services—evidenced by recent partnerships that broaden calibration and distribution reach.
- Magna‑Power Electronics (Flemington, NJ, USA): Distinguished by rugged DC supplies and vertically integrated U.S. manufacturing, Magna‑Power continues to move upstream in high-voltage and mission‑critical applications, supported by recent product launches and strategic contract awards.
- XP Power (United Kingdom): XP’s digitally configurable HP and HPA series target semiconductor manufacturing and robotics, reflecting a deliberate play into high-uptime, digitally controlled factory floors.
- Phihong USA, Acopian Power Supplies, Pico Electronics, Applied Power Systems: Each of these players occupies focused niches—Industry 4.0 automation OEM solutions, high-voltage platforms, miniaturized converters, and bespoke high-performance systems respectively—creating a diversified competitive field where specialization matters.
Recent market activity underscores these dynamics: product announcements and strategic awards in early‑mid 2026 highlight a race toward higher voltage, denser packaging, and system-level offerings. Examples include a new high‑voltage 1U DC model class and selection to power a hypersonic wind tunnel, plus partnerships to expand distribution and calibration services—all of which shift buyer expectations.
Market dynamics and regulatory realities
- Regulation and compliance: Expect IEC conformity and RoHS 3 compliance to strongly influence procurement cycles, particularly in regulated industries and export-sensitive supply chains. Designing for compliance up-front reduces technical debt and shortens approval timelines.
- Raw-material and supply-chain signals: The programmable power market depends on a specialized ecosystem of electronic components; sourcing concentration in certain regions increases geopolitical and logistical risk. Manufacturers pursuing nearshoring or dual-sourcing strategies will reduce lead-time variability.
- Macro trends: Battery gigafactory growth and semiconductor capex surges create predictable pockets of demand for programmable power systems. Simultaneously, cost competition from lower-cost suppliers is reshaping go-to-market economics for commodity ranges—accelerating consolidation among suppliers who cannot sustain margin contraction.
Risks, mitigants, and recommended near-term moves
For executives preparing budgets and strategic plans in 2026, the recommended priority list is pragmatic and short-cycle:
- Short-term (0–12 months): Lock down supply agreements for critical components; prioritize product configurations that demonstrate IEC/RoHS compliance; accelerate API and telemetry development for new platforms to meet buyer integration requirements.
- Medium-term (12–36 months): Invest in modular architectures that enable field-upgradable features (e.g., firmware-enabled bidirectionality); evaluate strategic alliances with calibration and distribution partners; consider bolt-on acquisitions to acquire high-voltage IP or localized manufacturing capabilities.
- Strategic (36+ months): Build an end-to-end services proposition (test software, predictive maintenance, calibration networks) to move beyond hardware commoditization and capture annuity-style revenue streams.
How to use this report in boardroom decisions
This PW Consulting research is intentionally structured to be directly actionable in board presentations and investment memos. It provides scenario-modeled revenue impacts, capex-to-ROI analysis for new product investments, and an M&A prioritization framework mapped to integration complexity and value capture. Use it to validate budgets, prioritize R&D spend, and set acquisition filters that align with your strategic horizon.
Conclusion and next step
The programmable power supply market in 2026 is a growth arena with clear winners for companies that combine technical differentiation, standards-first design, and resilient supply strategies. Our analysis quantifies the opportunity and prescribes pragmatic moves—while the full report contains the proprietary segmentation, granular regional and application tables, and vendor scorecards necessary to convert insight into signed contracts and launched products.
Access the comprehensive dataset and executable annexes on our site to unlock the detailed splits and vendor-level metrics that senior teams will use to finalize 2026 commitments.
For detailed analysis of this topic, please visit the official page: Programmable Power Supply Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com