

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Procalcitonin Market Set to Reach USD 365.4M by 2032 with 6.98% CAGR
By pmarketresearch, 2026-07-13
Procalcitonin (CAS 56645-65-9) Market 2026: Strategic Imperatives for Corporate Decision‑Makers
As PW Consulting’s lead industry strategist, I present a high‑caliber, executive‑level orientation to our Procalcitonin (PCT) Market study—designed specifically to inform boardroom decisions in 2026. This briefing synthesizes macro trajectories, competitive dynamics, regulatory and reimbursement inflection points, and a pragmatic playbook that senior leaders can deploy immediately. The intent here is to demonstrate the analytical depth underpinning our full offering while preserving the granular, proprietary numbers and segment breakouts that reside in the complete report.
Procalcitonin (CAS 56645-65-9) Market
Why PCT matters to 2026 strategy
Procalcitonin has evolved from a specialist research analyte to a clinically actionable biomarker shaping sepsis care pathways and antibiotic stewardship programs. Between 2020 and the report base year of 2025, the global market for Procalcitonin diagnostics expanded materially—driven by increasing guideline acceptance, hospital program adoption, and improved assay availability across platforms. Our modeled trajectory through the forecast period (2026–2032) assumes a compound annual growth rate (CAGR) of approximately 6.98%, reflecting both near‑term reimbursement tailwinds and medium‑term diffusion across care settings.
Procalcitonin (CAS 56645-65-9) Market
To anchor perspective: PW Consulting’s topline market model shows a market increasing from a mid‑hundreds million USD base in 2025 to a substantially larger addressable pool by 2032. This scale and growth profile creates distinct strategic choices for incumbents, instrument makers, reagent suppliers, and later‑stage investors—choices that demand different allocation of R&D, commercial effort, and M&A capital in 2026.
Procalcitonin (CAS 56645-65-9) Market
What corporate leaders should see as the immediate operating environment
-
Clinical and payer momentum: In 2025–2026 we observe expanded payer coverage—public and private—that explicitly supports PCT‑guided antibiotic decisions for sepsis and lower respiratory tract infections. This reimbursement expansion materially improves utilization economics and accelerates adoption where hospital stewardship programs can operationalize test‑based protocols.
-
Regulatory validation: New clearances are lowering barriers to clinical uptake. A notable development in May 2025 was a 510(k) clearance for a PCT assay and related controls—an outcome the market interprets as regulatory endorsement of PCT platforms as substantially equivalent to legacy systems. This creates a more permissive environment for new entrants and second‑generation assays seeking hospital and reference laboratory customers.
-
Platform and supply‑chain dynamics: The PCT ecosystem spans global in vitro diagnostics (IVD) instrument leaders, specialized assay originators, and a small but strategic set of suppliers for recombinant antigens and monoclonal antibodies. Control of calibrators, reference reagents, and validated antibodies is a non‑trivial source of competitive advantage, particularly for vendors seeking rapid assay development or for buyers aiming to reduce procurement risk.
-
Market structure: Market concentration levels indicate a fragmented landscape—top competitors do not dominate the space to an extent that would dissuade bold market entry or roll‑up strategies. The current concentration metrics show room for specialist firms to win share by focusing on niche clinical claims, pricing, or channel excellence.
Competitive landscape — who matters and why
PCT is currently supported by a small set of well‑known diagnostics firms and specialized reagent suppliers. These organizations occupy complementary strategic positions that together define the competitive chessboard for 2026:
-
Major platform incumbents (Roche Diagnostics, bioMérieux, Thermo Fisher Scientific, Siemens Healthineers): These firms offer integrated assays and analyzer solutions that are deeply embedded in hospital and reference labs. Their strengths are distribution reach, installed base economics, and the ability to bundle PCT testing with other routine lab workflows—making them natural favorites for enterprise procurement committees focused on operational efficiency.
-
Specialist reagent and assay developers (DiaSys Diagnostic Systems, HyTest, BBI Solutions): Specialist firms provide focused assay kits, calibrators, and critical raw materials (recombinant PCT antigen, monoclonal antibodies). Regulatory milestones from such players (for example, recent FDA 510(k) clearance events) are proof points that niche developers can convert technical capabilities into commercial access and can quickly influence local adoption when supported by effective clinical evidence.
-
Strategic implications: Market participants should treat platform players and reagent specialists as both partners and competitors. Partnerships or OEM supply agreements can accelerate market entry for smaller firms, while incumbents must guard against supply substitution and price erosion by vertically integrating or by signing exclusive reagent contracts.
Regulatory and reimbursement — windows of opportunity in 2026
-
Expanded coverage for PCT testing by public payers and commercial insurers in 2025 materially changes the near‑term ROI for hospital purchasers. For commercially driven product launches in 2026, aligning the evidence generation plan with payer expectations—especially around antibiotic‑stewardship outcomes and cost‑avoidance metrics—should be a top priority.
-
Regulatory precedent from recent 510(k) clearances reduces uncertainty for product teams following established platform claims. That said, companies targeting new indications (for example, point‑of‑care use outside intensive care settings) will still need tailored regulatory strategies and pragmatic clinical validation to secure formulary placements.
Key risks and cross‑cutting uncertainties
-
Clinical guideline variability: Adoption of PCT‑guided protocols is uneven across systems and influenced by local antimicrobial stewardship leadership. Shifts in guideline language or the publication of counter‑evidence could meaningfully affect uptake curves.
-
Technological substitution: Advances in multiplex molecular panels or novel host‑response biomarkers could compete with single‑marker PCT strategies in certain use cases. Firms must monitor adjacent diagnostic innovations and consider platform flexibility.
-
Procurement dynamics: Hospital formulary decisions and group purchasing organization contracts remain decisive for adoption. Successful suppliers will need playbooks for contracting, clinical affairs engagement, and on‑site implementation support.
What our report contains — operational, actionable deliverables
The full PW Consulting Procalcitonin Market report is constructed as a decision‑grade tool for 2026. Highlights of the practical content included are:
- Topline market sizing and validated growth forecasts from 2020 through 2032, with scenario analysis that isolates near‑term reimbursement impacts and longer‑term diffusion curves.
- Competitive intelligence dossiers for leading and emerging firms, including commercial models, product portfolios, advantage maps, and go‑to‑market strengths and weaknesses.
- Regulatory and payer playbooks: templated evidence packages, recommended clinical endpoints for label expansion, and reimbursement submission frameworks tailored to national markets.
- Channel and pricing strategies: unit economics models, contract negotiation levers for selling into hospital systems and reference labs, and pricing sensitivity analyses to support margin optimization.
- Supply‑chain risk assessment and mitigation tactics: supplier scorecards for raw materials (recombinant antigen, monoclonals), qualification checklists, and inventory strategies to support clinical continuity.
- Transaction and partnership guidance: M&A screening criteria, partnership archetypes, and valuation sensitivities built from multiples observed in recent diagnostics deals and relative margin performance.
Each module contains exhibits, supporting data tables, and a set of executable recommendations. To preserve the commercial value of those granular exhibits (segment breakouts, regional revenue splits, and unit‑price schedules), they are accessible exclusively through the full report package.
Strategic playbook for 2026 — five prioritized moves
-
Lock the clinical story: Fund or partner on targeted outcome studies that demonstrate antibiotic‑sparing benefits and reductions in length of stay. Payer coverage in many markets now ties directly to such outcomes; evidence gaps materially slow procurement decisions.
-
Defend and diversify supply chains: Secure multi‑sourced supplies for recombinant antigen and antibodies or invest in backward integration. A targeted contingency strategy for critical reagents will protect growth and reduce procurement leverage from competitors.
-
Negotiate formulary access early: Build compelling total cost of ownership (TCO) cases for hospital executives and procurement consortia. Bundle PCT offerings with implementation services, stewardship program support, and dashboards that demonstrate measurable impact.
-
Consider platform vs niche positioning: Decide whether to pursue broader platform integration with major analyzer OEMs or to dominate a niche (e.g., point‑of‑care, rapid triage). Both approaches can win in 2026 — but each requires different investment, pricing, and partnership playbooks.
-
Use M&A and partnerships as force multipliers: With current market concentration moderate, well‑timed acquisitions of reagent specialists or clinical services firms can accelerate share gains and close technology gaps faster than organic development.
Final observation — why 2026 is pivotal
2026 represents a decision nexus: reimbursement and regulatory shifts enacted in 2025 have improved the commercial environment, while the market’s medium‑term growth (a near 7% CAGR over the forecast interval) supports expansion investments. For corporate leaders, the choice is whether to invest to capture the inflection—by bolstering evidence, securing supply and channel access, and using partnerships to close capability gaps—or to adopt a defensive posture as competitors consolidate position.
PW Consulting’s Procalcitonin Market study equips leaders to make that choice with confidence. The analysis delivers not only the macro forecasts and competitive context outlined here, but also the masked, transaction‑grade exhibits that translate strategy into actionable budgets, timelines, and KPI targets. For access to the full dataset, segmented models, and our recommended implementation templates, please consult the complete report.
For detailed analysis of this topic, please visit the official page: Procalcitonin (CAS 56645-65-9) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Non-dairy Creamer Market to reach USD 3,025M by 2032 at 5.82% CAGR
By pmarketresearch, 2026-07-13
Non-dairy Creamer Market 2026: Strategic Preview for Executive Decision-Making
PW Consulting presents a condensed strategic preview of our full Non-dairy Creamer Market study — positioned to inform executive decision-making in 2026. The market is no longer a peripheral category; it sits at the intersection of shifting consumer diets, ingredient-cost volatility, and an evolving regulatory landscape. This preview outlines the macro trajectory, critical dynamics, competitive posture, and the practical decision tools contained in the full report. It is intentionally diagnostic rather than exhaustive: we surface the strategic implications and proprietary frameworks you will need, while reserving granular segment tables and detailed supplier-level data for the full release available on our website.
Non-dairy Creamer Market
Why this study matters for 2026 decisions
-
Measured momentum: The category’s trajectory is resilient. With a 2025 base of USD 2,050 Million (base year) and a forecast through 2032 at an industry compound annual growth rate (CAGR) of 5.82%, the market presents a clear expansion pathway for incumbents and new entrants alike. By 2032 the market is projected to approach USD 3.025 Billion, representing a meaningful addressable opportunity for product innovation, channel expansion, and consolidation plays.
Non-dairy Creamer Market -
Tightening commercial margins: Rising input costs for plant-based feedstocks — almond, coconut, oat and soy — and ongoing logistics pressure are compressing gross margins for many producers. The economics of formulation, scale manufacturing, and price pass‑through are therefore central to 2026 budgeting and sourcing decisions.
Non-dairy Creamer Market -
Regulatory & recall risk is front‑and‑center: Recent high‑profile recalls and tightening FDA guidance make allergen controls, labeling accuracy, and FSVP compliance non‑negotiable for market access. These risks have direct implications for private-label suppliers, co‑packers, and import-reliant brands.
What the full PW Consulting study delivers (high-level)
The report blends market sizing, scenario forecasting, competitor benchmarking, and hands‑on execution tools. Key deliverables include:
-
Top‑down and bottom‑up market sizing with a 2026–2032 forecast built on demand drivers and price trends.
-
Demand-driver analytics that quantify the impact of health positioning, flavor innovation, and foodservice recovery on category growth.
-
Supply‑chain and input‑cost models that allow you to stress test margin scenarios under multiple commodity and logistics regimes.
-
Regulatory and recall playbook: compliance checklists, label‑review matrixes, and an incident response simulation tailored to non‑dairy creamer formulations.
-
Commercial frameworks: SKU rationalization tools, channel prioritization matrices, and a retailer negotiation playbook informed by current private‑label dynamics.
-
M&A and partnership screening methodology: a prioritized shortlist of strategic acquisition archetypes and the valuation levers that matter in 2026—2028.
Market dynamics you cannot ignore
-
Ingredient economics: Plant‑based feedstocks command a price premium relative to conventional dairy inputs. This dynamic materially alters formulation choices, affects placement of premium vs. value SKUs, and increases the importance of long‑term procurement contracts and hedging strategies.
-
Labeling & allergen control: Recent events — including a Class I recall tied to undeclared milk allergen — and updated FDA guidance emphasize that “non‑dairy” labeling is not a regulatory safe harbor. Manufacturers must ensure ingredient transparency and robust supplier verification to avoid market‑stopping recalls.
-
Trade & import scrutiny: Intensified FSVP inspections and import alerts mean import‑reliant players must invest in traceability and foreign supplier governance to preserve access to key markets.
-
Channel blend evolution: Retail premiumization and foodservice demand for barista‑grade behaviorally consistent creamers are creating bifurcated opportunities — premium, clean‑label formats vs. large‑volume industrial and foodservice formats.
Competitive landscape — synthesis and strategic takeaways
The market exhibits moderate concentration, with the combined market share of the top three and top five firms indicating room for both scale advantages and regional entrants. The competitive set spans large multinational CPG players, agile plant‑based specialists, and regional bulk manufacturers. Below we synthesize the strategic posture of representative players and the implications for 2026 strategy.
-
Nestlé: Leverages scale, shelf‑space relationships and strong foodservice channels. Advantage lies in distribution depth and brand familiarity; risk centers on speed of innovation against nimble plant‑based specialists.
-
Danone: Plays the plant‑forward portfolio and reduced‑sugar propositions into retailer health objectives. Strategic implication: incumbents must defend through both formulation and value communication.
-
Oatly and Califia Farms: Specialists with strong clean‑label and oat‑centric narratives. Their strengths are ingredient authenticity and brand positioning; their constraints are scale and ingredient cost exposure — ideal partners for premium placement or co‑development deals.
-
Chobani, Nutpods, Elmhurst, Ripple: Positioned on product innovation, flavor variety, and targeted health claims (unsweetened, high‑protein, lentil‑based). These players demonstrate the tactical value of niche differentiation combined with purposeful channel strategies.
-
Native Forest and specialty regional manufacturers (e.g., OEMs in China): Offer competitively priced, high‑volume supply for industrial and private‑label channels. Strategic considerations: sourcing reliability and regulatory transparency are critical when engaging with bulk suppliers.
Strategic implications: incumbents should pair scale‑driven efficiencies (pricing and distribution) with targeted innovation to defend premium niches. New entrants can win via credible clean‑label claims, targeted channel focus (e.g., specialty coffee or online DTC), and partnerships that mitigate ingredient and compliance risk.
Recent industry events that change the playbook
-
Product recalls and allergen enforcement: A high‑risk Class I recall in 2025 for undeclared milk allergen underscores the immediate commercial damage of labeling failures. Companies must treat allergen control as a board‑level risk item, not an operational checkbox.
-
New product launches: Several large and emerging brands expanded into flavored and simplified‑ingredient creamers in 2025–2026, reflecting retailer appetite for clean‑label, low‑sugar alternatives. These launches validate demand but also compress premiumization windows as more SKUs chase the same shelf space.
-
Regulatory enforcement: FDA import alerts and FSVP audits have real consequences for importers and private‑label supply chains. Investment in supplier verification and traceability technology is no longer discretionary.
Actionable recommendations for 2026
-
Reassess supplier strategy: Prioritize dual‑sourcing for critical plant inputs and formalize long‑term contracts to stabilise costs. For importers, accelerate FSVP remediation and third‑party audits before market entry.
-
Optimize SKU architecture: Use our SKU rationalization template to identify which formulations to scale, simplify or sunset. Focus R&D spend on clean‑label, low‑sugar and barista‑grade functionalities that command premium margins.
-
Invest in labeling and traceability: Implement a labeling governance framework, routine label audits, and real‑time ingredient traceability to reduce recall probability and speed incident response.
-
Prepare for strategic M&A: Target acquisition archetypes include regional co‑packers with compliant supply chains, ingredient technology startups that reduce cost‑in‑use, and brands with loyal DTC followings. Use our valuation levers to prioritize targets.
-
Scenario planning for commodity shocks: Run our three‑scenario margin model (base, stress, severe) over your 2026 P&L to set defensible pricing and promotional strategies.
What’s reserved for the full report
To preserve the utility of our proprietary analysis, the full report contains the detailed segment-level tables, regional and application splits, SKU-level pricing forecasts, and a prioritized supplier directory. It also includes downloadable tools — supplier scorecards, a recall simulation workbook, and a channel prioritization matrix — that translate insight into executable plans. These items are intentionally withheld from this preview to drive direct engagement with the study and ensure strategic exclusivity for subscribing clients.
How PW Consulting can assist
-
Customized briefings: We provide executive workshops that translate report findings into 90‑day tactical roadmaps.
-
Due diligence & M&A support: Target screening, commercial diligence, and post‑deal integration plans tailored to non‑dairy creamer assets.
-
Operational playbooks: Co‑development of supplier governance, allergen control programs, and barista‑grade manufacturing checklists.
In a market growing at an anticipated 5.82% CAGR from 2026 to 2032 and expanding from a USD 2,050 Million base in 2025 to an expected USD 3,025 Million by 2032, the strategic edges will be held by organizations that combine commercial scale, ingredient foresight, and uncompromising regulatory controls. PW Consulting’s full Non‑dairy Creamer Market study equips leadership teams with the modeling, competitive intelligence, and practical tools to act quickly and confidently in 2026. For access to the complete dataset, segmented forecasts, and operational toolkits, please visit our report page.
For detailed analysis of this topic, please visit the official page: Non-dairy Creamer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Avocado Oil Market to Hit USD 933.33M by 2032 at 6% CAGR
By pmarketresearch, 2026-07-13
Avocado Oil Market 2026: Strategic Signals and Executive Playbook
The global avocado oil market is at an inflection point entering 2026. After steady expansion through the 2020–2025 baseline, our analysis shows the market reaching roughly USD 626 million in 2025 and tracking toward nearly USD 933 million by 2032 under our central scenario — a compound annual growth rate (CAGR) of approximately 6.0% across the forecast window. These headline figures understate the complexity beneath the curve: shifting supply dynamics, regulatory friction, premiumization in culinary and personal care channels, and a moderately concentrated supplier landscape are combining to create differentiated opportunity sets for market entrants, incumbents, and investors.
Avocado Oil Market
Why this briefing matters to 2026 corporate decisions
-
Timing for capacity and sourcing choices: The market growth trajectory implies more aggressive procurement and inventory strategies for companies exposed to upstream avocado supply volatility. Decisions made in H1–H2 2026 on sourcing contracts, tolling arrangements, or vertical integration will materially affect cost curves through the rest of this decade.
Avocado Oil Market -
Channel and product mix prioritization: Premium extra-virgin and cold-pressed propositions are commanding outsized attention from health-conscious consumers and premium foodservice buyers, while refined and blended formats retain relevance for mass retail and industrial uses. Allocating commercial resources between premiumization and scale channels needs to align with your margin architecture and brand positioning.
Avocado Oil Market -
M&A and partnership timing: With the top three players holding just over half of the market and the top five approaching seven-tenths concentration, there is structural room for bolt-on acquisitions and strategic alliances — particularly for firms seeking shelf-scale, category adjacency, or raw-material control.
-
Regulatory readiness and risk mitigation: Recent regulatory moves affecting imports and export bans have demonstrated how quickly supply availability can shift. Incorporating regulatory scenario planning into procurement and go-to-market playbooks is no longer optional.
Market dynamics shaping strategy in 2026
-
Supply-side shocks and sourcing geography: Periodic harvest shortfalls and export controls (notably temporary export restrictions observed recently in some producing countries) have compressed availability windows and increased price volatility. Buyers should expect occasional tightness that will favor firms with diversified sourcing or owned supply.
-
Regulation and trade policy as operational levers: USDA and other trade authorities have re-affirmed certification and maturity requirements for imports, and industry discussions around tariff-rate quotas and inspector deployments have resumed. These administrative levers can alter landed cost and clearance timelines; companies without a regulatory playbook risk margin erosion and stockouts.
-
Premiumization and functional claims: Consumers continue to value neutral-flavor, high smoke-point oils and seek recognizable health and clean-label claims. Avocado oil’s positioning in both culinary and personal-care formulations is strengthening, especially where cold-pressed or extra-virgin claims can be credibly substantiated.
-
Channel bifurcation: DTC and e-commerce give premium producers rapid access to high-LTV customers and data-driven product iteration, while brick-and-mortar grocery and industrial channels still drive volume. Balancing the two requires different commercial and supply-chain architectures.
Competitive landscape: profiles and strategic takeaways
-
Chosen Foods (San Diego, CA) — https://chosenfoods.com
Positioning: A leading mainstream brand emphasizing 100% pure avocado oil across culinary SKUs and convenience formats (e.g., sprays and mayos). Recent moves include nationwide expansion of organic SKUs and a new cold-pressed line aimed at antioxidant retention. Strategic implication: Chosen Foods is leveraging scale and brand recognition to defend mass-premium space; competitors should anticipate aggressive retail shelf activity and promotional cadence from this player.
-
Marianne’s Harvest (Woodland, CA) — https://mariannesharvest.com
Positioning: Family-owned, sustainability-forward manufacturer with organic and regenerative-certified variants. Recent January 2026 rollout on Amazon with nationwide shipping signals a deliberate shift into high-reach e-commerce. Strategic implication: Marianne’s Harvest is prioritizing direct-to-consumer scale while preserving premium claims; incumbents should monitor its digital pricing and subscription strategies as a leading indicator for premium channel economics.
-
Bella Vado (Valley Center, CA) — https://bellavado.com
Positioning: The only U.S. producer of cold-pressed, extra-virgin, unrefined avocado oil from a family organic grove. Strategic implication: Bella Vado’s tight provenance story and single-origin authenticity create a defendable niche in high-end culinary and gift segments; however, limited production scale makes it less of a competitive threat at mass retail unless it pursues partnerships or licensing.
-
Grove Avocado Oil (Te Puna, New Zealand) — https://groveavocadooil.co.nz
Positioning: Premium extra-virgin producer with a focus on health benefits. Strategic implication: Geographic diversification in supply and strong quality propositions position Grove to serve export markets that value provenance and cold-pressed processing.
-
La Tourangelle (Woodland, CA) — https://latourangelle.com
Positioning: Artisan oil house offering blended and specialty avocado oil SKUs, leveraging heritage processing techniques. Strategic implication: La Tourangelle targets culinary enthusiasts and heritage food channels; their blended SKUs may be attractive to co-manufacturers seeking consistency and cost-efficiency.
-
Avohass (Los Angeles, CA) — https://avohass.com
Positioning: Premium extra-virgin producer sourcing from multiple origins and offering infused variants. Strategic implication: Broad sourcing plus product variety enables Avohass to service multiple channels, but it also requires tight quality assurance to maintain premium claims across origins.
Collectively, the top three players control just over half the market, and the top five approach roughly two-thirds. That concentration profile creates both defensive imperatives for incumbents (scale-driven procurement, branded distribution) and opportunities for challengers (niche specialization, supply control, premium DTC plays).
What the full PW Consulting report delivers (practical, executable content)
-
Transparent market sizing and trend maps: year-by-year market totals from 2020–2025 and scenario-based forecasts to 2032, with clear assumptions and sensitivity ranges.
-
Demand segmentation frameworks (by format, application, and route-to-market) translated into go-to-market priorities and SKU rationalization templates. Note: detailed segment percentage tables and proprietary breakdowns are available in the full dataset.
-
Supply-chain intelligence pack: origin risk heatmaps, landed-cost models, supplier scorecards, and a short-list of vetted co-manufacturers and toll partners.
-
Regulatory and trade-risk matrix: impact assessment for import/export controls, certification requirements, and mitigation playbooks for common regulatory shocks.
-
Commercial playbooks: pricing elasticity diagnostics by channel, promotion optimization heuristics, and a three-tier channel strategy tailored to premium, mainstream, and industrial customers.
-
M&A and partnership playbook: acquisition target scoring, synergy valuation templates, and a phased integration checklist designed for the category.
-
Executive dashboards and data appendices: downloadable models (USD, revenue unit: Million), CR3/CR5 concentration analytics, and a reproducible forecasting workbook aligned to the report’s baseline assumptions.
Practical 90-day plan for executives
-
Run a sourcing stress-test: model three procurement scenarios (conservative, central, contingency) that include alternate origin mixes and cost pass-through assumptions. Prioritize contracts that offer flexibility (short-term options, FOB vs CIF toggles).
-
Validate premium SKU economics: pilot two extra-virgin/cold-pressed SKUs in e-commerce and specialty retail channels with controlled A/B pricing and creative testing to quantify margin premium viability.
-
Regulatory readiness sprint: assign a cross-functional task force to translate USDA and other trade requirements into clearance workflows and identify at least one certified inspection partner in each key origin.
-
Competitive monitoring and partnership scouting: open diligence on one bolt-on asset or offtake partner that accelerates access to either scale production or differentiated provenance claims.
-
Stakeholder communication: prepare investor and retail partner narratives that explain supply strategies and margin protection measures in light of recent export and regulatory events.
Closing and next steps
For executives planning their 2026 playbook, the difference between opportunistic and enduring success will be determined by the combination of supply resilience, brand-to-channel alignment, and disciplined use of data to execute SKU and pricing decisions. Our report provides the granular scenario outputs, segmented demand matrices, and operational templates necessary to translate the headline growth — roughly USD 626 million in 2025 expanding toward a nearly USD 933 million outlook by 2032 at ~6.0% CAGR — into actionable strategies.
To access the complete segmented datasets, downloadable financial models, and the detailed competitive annex — including source-verified timelines of recent product launches and channel expansions — please visit the PW Consulting Avocado Oil Market report page. The full intelligence package is designed to support board-level strategy sessions, commercial planning cycles, and M&A diligence in 2026.
For detailed analysis of this topic, please visit the official page: Avocado Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Emergency Lighting Market Set for 8.2% CAGR Through 2032
By pmarketresearch, 2026-07-13
Emergency Lighting Market 2026: Strategic Imperatives for Risk‑Averse Growth
As emergency lighting migrates from a compliance checkbox to a systems-level safety and resilience play, 2026 will be a watershed year for equipment manufacturers, distributors, building owners, and infrastructure investors. PW Consulting’s latest Emergency Lighting Market study synthesizes five years of historical performance with a seven-year forecast horizon to surface the choices that determine winners and losers. The global market we track expanded from roughly USD 350 million in 2020 to USD 450 million in 2025 and — at a compound annual growth rate of 8.2% — is projected to approach the high‑seven‑hundreds of millions by 2032. That trajectory reflects a mix of retrofit demand, code-driven upgrades, and increased adoption of lithium‑battery, self‑diagnostic and connected platforms.
Emergency Lighting Market
Why this study matters for 2026 corporate decision-making
Several converging forces make 2026 a decisive planning year. Regulatory refreshes (including the 2024 NFPA/Life Safety Code and the upcoming NEC revision cycle) raise testing and spatial illumination requirements that directly drive retrofit cycles across commercial, institutional, and public safety assets. UL 924 and its 2024–2025 updates have tightened certification pathways and introduced additional investigative steps such as Emergency Lighting Control Functionality (ELCF) testing and a broader acceptance of alternative visual designs through UL 924A — increasing the R&D and compliance burden for manufacturers while creating differentiation opportunities for those with strong certification programs.
Emergency Lighting Market
At the same time, component economics matter more than ever. Lithium batteries have become a meaningful component cost driver — industry analysis indicates battery chemistry can account for up to roughly a quarter of a fixture’s unit price, and lithium carbonate spot dynamics created material cost volatility in early 2025. Combined, these regulatory and commodity headwinds mean product roadmaps, sourcing strategies, and aftermarket business models will determine margin trajectories and go-to-market viability in 2026 and beyond.
Emergency Lighting Market
What the PW Consulting report delivers — practical, transaction‑ready intelligence
- Bottom‑up market sizing and a seven‑year forecast that translates CAGR assumptions into revenue scenarios at the global level (base year 2025, forecast through 2032), including downside and upside stress tests tailored to regulatory and commodity shocks.
- Regulatory compliance playbook mapping UL 924, UL 924A, NFPA 101, and IBC implications to product design, testing timelines, and documentation workflows — designed for immediate operational use in product development and certification planning.
- Supply‑chain risk heatmap and procurement toolkit that models lithium price sensitivity, alternative chemistry impacts, lead‑time risk, and supplier concentration — with step‑by‑step mitigation actions and contract templates.
- Retrofit and new‑build demand assessment that converts code revisions and building stock vintage into prioritized sales targets and retrofit-ready value propositions.
- Commercial playbooks for pricing, tender response, and service‑based monetization (extended warranties, diagnostics subscriptions, remote testing services), including margin impact models calibrated to 2026 cost baselines.
- Competitive positioning module—company scorecards, capability matrices, and product-differentiation frameworks—designed to support M&A screening, OEM partnerships, and distributor alignment.
- Executive dashboard and downloadable financial models for scenario planning, enabling management teams to run “what‑if” analyses in minutes during board and investor discussions.
Competitive landscape — interpreting the movers and makers
The market exhibits moderate fragmentation: leading multi‑national vendors are influential but do not monopolize demand, leaving space for nimble challengers and vertical specialists. Strategic positioning today follows one of several clear approaches:
- Integrated systems play: Large lighting manufacturers that combine certified emergency fixtures, battery systems and control electronics pursue comprehensive solutions for commercial and institutional portfolios. These players leverage scale in certification, distribution, and channel relationships to defend specification pathways.
- Component and subsystem specialization: Suppliers focusing on drivers, electronics and battery integration are becoming strategic linchpins. Their roadmaps determine product performance and compliance timelines for OEMs; control over driver innovations and diagnostics can translate directly into higher ASPs and aftermarket revenue.
- Vertical and application specialization: Firms that concentrate on high‑abuse, marine, or public‑safety segments achieve defensible margins by meeting durable performance specs and certification programs unique to those verticals.
- Smart and services‑first challengers: A cohort of vendors is pairing LED fixtures with IoT‑ready diagnostics and subscription services, turning a compliance product into a recurring revenue asset that appeals to facility managers seeking lifecycle certainty.
Representative vendors illustrate these archetypes: Cooper Lighting Solutions continues to push high‑output, lithium‑enabled exit and emergency fixtures with built‑in self‑diagnostics and UL 924 alignment; Kenall focuses on rugged, NFPA‑approved solutions for demanding environments; Whelen emphasizes public safety lighting and mass notification systems; Fulham is influential at the component level with emergency drivers and control electronics; Lumitec competes in marine and industrial niches with specialized reliability claims; and European players bring smart, design‑forward emergency systems to institutional projects. Recent product activity — from Cooper’s SEL 30‑70 series to new driver introductions by Fulham and literature refreshes by Whelen — confirms that product refresh cadence and certification readiness will be differentiators in 2026.
Market dynamics and risk vectors to monitor in 2026
- Regulatory acceleration: Tighter enforcement and updated testing specifications will accelerate retrofit demand but also lengthen product development cycles for companies that fail to anticipate new certification steps.
- Commodity volatility: Lithium chemistry pricing and availability remain principal cost risks; firms need procurement hedges, supplier diversification, or alternative chemistry roadmaps to protect margins.
- Technology substitution: The shift to IoT‑enabled self‑diagnostic platforms creates upsell paths (remote testing subscriptions, analytics) but requires investments in cybersecurity and data management capabilities.
- Channel and specification control: Access to spec writers, integrators, and major distributors will determine market share in large tenders. Companies that can bundle fixture supply, testing documentation, and maintenance services will win larger contracts.
- M&A and consolidation: Moderate concentration at the top of the market implies opportunities for bolt‑on acquisitions that expand geographic reach or add specialist vertical competencies.
Actionable strategic plays for 2026
- Prioritize retrofit-first GTM: Target building stock subject to recent code revisions with fast‑track retrofit offers that bundle product, certification support, and testing services — capture early retrofit premiums while competitors retool.
- Build certification as a capability: Invest in in‑house testing labs, or strategic partnerships, to shorten UL 924/ELCF timelines and exploit UL 924A alternative pathways for design differentiation.
- Hedge the battery supply chain: Negotiate multi‑year offtake arrangements, evaluate hybrid chemistries, and design modular battery subsystems to reduce single‑supplier dependency and to insulate pricing to customers.
- Monetize services: Convert one‑time fixture sales into recurrent revenue via diagnostics subscriptions, compliance reporting, and scheduled maintenance contracts — increase customer lifetime value and resilience to price pressure.
- Targeted M&A: Acquire niche specialists to fill capability gaps (mass notification, marine/environmental ruggedization, or driver/control expertise) rather than broad horizontal scale plays; the market’s current structure rewards capability complements over simple size.
How PW Consulting helps executives in 2026
Our Emergency Lighting Market study is structured as both an analytical foundation and an operational toolkit. Clients receive the macro forecasts and a suite of ready‑to‑use deliverables — procurement negotiation templates, certification project roadmaps, retrofit prioritization scorecards, and competitive playbooks. For teams preparing board decisions or investor presentations, we offer tailored scenario modeling workshops that embed your cost structure, geographic focus, and product roadmap into the report’s forecast engine.
We intentionally designed this release to demonstrate our methodology and strategic perspective while preserving the granular segment tables and competitive scorecards that underpin transaction and procurement decisions. Those detailed segmentations — including the region/type/application matrices and the full set of company financial proxies — are available in the full report package and through our consulting engagement services.
To secure a copy of the full intelligence set, including downloadable models and the proprietary segmentation tables that operationalize the above recommendations, visit the report page or contact our industry practice. In a market where compliance, components, and connected services intersect, the decisions you make in 2026 will determine your cost structure, specification access, and recurring revenue trajectory for the next decade — choose the intelligence that makes those decisions defensible.
For detailed analysis of this topic, please visit the official page: Emergency Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
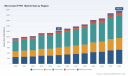
Micronized PTFE Market: Strategic Imperatives for 2026 Decision‑Makers
As PW Consulting’s senior strategy lead and chief industry analyst, I present a synthesis of the Micronized PTFE market study designed to shape corporate decisions in 2026. Built on a base year of 2025 with a historical window that covers 2020–2025 and a forward-looking forecast to 2032, the study projects continued expansion at a compound annual growth rate (CAGR) of 6.92%. The market has expanded from roughly USD 950 million in 2020 to about USD 1.225 billion in 2025, and our scenarios point toward nearly USD 2.0 billion by 2032 under baseline assumptions. This briefing highlights the strategic takeaways, competitive dynamics, and near‑term actions executives should consider — while reserving the full granular segmentation and proprietary model outputs for the full report.
Micronized PTFE Market
Why this study matters now
-
Timing and magnitude: 2026 is shaping up to be a pivot year. Demand growth is steady and predictable at the headline CAGR, but supply‑side shocks, regulatory tightening, and shifts in end‑use formulations are creating asymmetric risks for both suppliers and converters. Companies that align procurement, R&D, and commercial strategies now will capture outsized share and margin improvement through the next planning cycle.
Micronized PTFE Market -
Strategic visibility: Our analysis translates aggregate market momentum into decision‑grade outputs — supply risk maps, price sensitivity matrices, and product/market prioritization frameworks — enabling executive teams to make informed tradeoffs between securing capacity, investing in product innovation, and defending margin under input‑cost stress.
Micronized PTFE Market -
Operational cadence: For procurement, manufacturing and product teams the report frames six actionable workstreams (sourcing diversification, price hedging, product reformulation, capacity choreography, sustainability certification, and M&A/partnership screening) that should be instituted as part of the 2026 operating plan.
Macro and market dynamics shaping 2026
-
Supply tightness and pricing volatility: Regulatory shifts and export licensing in key fluorite supply geographies have tightened upstream availability. Industry data show a material contraction in export volumes from principal suppliers, which has pushed global spot pricing upward and raised costs for hydrofluoric acid and other fluorochemical feedstocks. These upstream moves translate into higher landed costs and shorter contract lead‑times in Europe and North America.
-
Regulatory and environmental pressure: Tighter environmental controls on fluoropolymer production — including PFAS scrutiny and emissions monitoring — are increasing compliance burdens and capital expenditure requirements for manufacturers. Expect ongoing increases in testing, monitoring and reporting costs that will be reflected in supplier pricing and qualifying processes.
-
Raw material volatility: Tetrafluoroethylene (TFE) pricing and feedstock availability have become more volatile, complicating long‑term contract negotiations. Our scenario work shows that an 8% swing in TFE prices can materially affect small compounders’ margin profiles and accelerate consolidation if sustained.
-
Demand resilience with structural changes: End‑use demand remains resilient across coatings, lubricants, polymer modification, inks and specialty industrial applications, but the mix is shifting toward low‑VOC systems, water‑based formulations and recycled‑content products — a movement that creates both growth opportunities and qualification hurdles for micronized PTFE grades.
Market trajectory and structural implications
At the headline level, the market’s progression from the low‑hundreds of millions in 2020 to the mid‑billions by 2032 reflects steady volumetric growth and gradual value uplift as higher‑performance grades and sustainability credentials command pricing premiums. Market concentration metrics indicate a moderately fragmented industry: the top three companies account for roughly one‑third of global revenue and the top five do not exceed 40% share, underscoring a competitive environment where regional players, specialty compounders and global fluoropolymer producers all retain strategic relevance.
Implication for strategy: buyers enjoy choice but face heterogenous supplier risk. Large converters should use that fragmentation to extract service and security commitments; smaller players may need to pursue vertical integration, strategic alliances, or long‑term supply contracts to stabilize margins.
Competitive landscape — what to watch
-
Chemours Company (Zonyl®): A global specialty supplier with a strong presence in coatings, lubricants and polymer modification. Recent strategic moves include securing additional regional production capacity through alliance structures to reduce delivery lead‑times into high‑growth markets.
-
Daikin Industries: A technology‑driven producer with engineered grades targeted at high‑performance plastics and industrial additives. Their product leadership and global footprint make them a key supplier for formulators demanding precise performance attributes.
-
3M Company (Dyneon™): Continued product innovation, including surface‑modified micronized PTFE grades for low‑VOC and water‑based coatings, positions them well for formulators transitioning away from solvent systems.
-
AGC Inc.: Expanding fluorochemical capacity and gaining early third‑party recycled‑content certifications creates a differentiated sustainability narrative that will influence corporate procurement policies and brand‑driven specification trends.
-
Specialist and regional producers: European and Chinese producers provide local cost and service advantages, especially for regional formulators. Smaller compounders, however, face margin compression under feedstock scarcity and regulatory cost pressure, increasing M&A potential.
Recent corporate activities — capacity alliances in India, capacity expansions in Japan, recycled‑content certification rollouts, and launches of application‑specific low‑VOC grades — collectively point to three dynamics: diversified geographic capacity buildout, premiumization via application engineering, and sustainability as a competitive axis. These moves, taken together, will materially influence commercial negotiations and qualification calendars in 2026.
What the PW Consulting report delivers (practical contents)
-
Proprietary market model: a transparent, auditable Excel model spanning 2020–2032 that supports scenario testing (base, supply‑shock, accelerated‑demand). The model includes price curves, cost drivers, and sensitivity levers.
-
Supply‑risk taxonomy and map: supplier scorecards, capacity overlays, and logistics risk indices to prioritize contracted capacity and identify safe‑source partners.
-
Commercial playbooks: negotiation templates for long‑term offtake, hybrid pricing mechanisms, and contract clauses addressing force majeure, allocation, and ESG commitments.
-
Product and formulation roadmaps: gap analyses for coating, lubricant and polymer applications with recommendations on specification migration, qualification timelines, and co‑development priorities.
-
M&A and partnership screening: target lists and valuation priors for bolt‑on acquisitions and strategic alliances that strengthen feedstock security, technical capability, or regional presence.
-
Regulatory risk dashboard: jurisdictional compliance trackers, cost impact simulations for emission controls and PFAS rules, and recommended mitigation actions for 12–36 month horizons.
Note: the summary above is intentionally high level. The full report contains the detailed subsegment datasets, regional and application splits, supplier revenue estimates, and the raw model files necessary for direct import into corporate planning systems.
High‑impact recommendations for 2026
-
Secure supply through diversification and contracts: Move from spot exposure to a blended strategy that includes multi‑year contracts, strategic buffer inventories, and regional secondary suppliers to mitigate upstream export licensing risk.
-
Prioritize product innovation for low‑VOC and recycled content: Build or partner for grades formulated for water‑based and recycled‑content specifications now, to compress qualification timelines and capture premium pricing as demand mix shifts.
-
Implement raw material governance and hedging: Tighten procurement governance around TFE and fluorspar exposure, adopt trigger‑based hedges, and perform quarterly stress‑tests to update cost pass‑through clauses with customers.
-
Accelerate sustainability certification: Use third‑party recycled‑content and lifecycle verification to differentiate supply and shorten approval cycles with sustainability‑driven OEMs and brands.
-
Evaluate near‑market capacity plays: Consider minority investments or JVs in growth regions to secure domestic supply, shorten lead times and avoid the most acute landed‑cost inflation.
Final note — how PW Consulting supports execution
Our Micronized PTFE Market study is structured to convert market intelligence into executable plans. For 2026, this means translating a 6.92% CAGR baseline and the observable supply shocks into concrete procurement, R&D, and commercial actions that protect margin and position businesses for selective top‑line capture. The study’s datasets, supplier scorecards, and scenario models are designed for direct integration into corporate planning tools — but those proprietary elements are available only in the full report and model package.
For teams preparing 2026 operating plans: begin by mapping your exposure across the six workstreams highlighted, run the supplied scenario models against your demand plan, and initiate selective supplier conversations informed by our risk maps. PW Consulting can support those activities with targeted workshops, model integration, and deal support.
To access the full dataset, supplier scorecards and executable playbooks, please consult the full Micronized PTFE Market report.
For detailed analysis of this topic, please visit the official page: Micronized PTFE Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
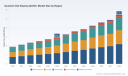
Quantum Dot Display (QLED) Market: Strategic Outlook for 2026 — PW Consulting Preview
Quantum dot displays have moved from a niche image-quality differentiator to a mainstream strategic vector for display OEMs, material suppliers, and systems integrators. This PW Consulting preview distills why the QLED market will matter to boardroom agendas in 2026 and how senior commercial, product and M&A leaders should reframe decisions in light of an accelerating technology and supply-chain reconfiguration.
Quantum Dot Display (QLED) Market
Market trajectory at a glance
After an inflection period between 2020 and 2025 — when the market expanded from roughly USD 1.9 billion to USD 2.95 billion — PW Consulting projects the QLED market to enter a sustained growth phase through our forecast window (2026–2032). Our modeled baseline shows a compound annual growth rate of 8.8% into the forecast period, with total market value rising toward the mid-single-digit billions by the early 2030s. This momentum reflects broader adoption across premium consumer electronics, the emergence of new form factors, and the industrialization of quantum dot material supply chains.
Quantum Dot Display (QLED) Market
Why this matters for 2026 decision-making
- Portfolio prioritization: Product leaders must decide which display platforms to accelerate. QLED technologies are no longer solely a premium TV play — they are influencing monitor, mobile, and automotive display strategies. The pace of adoption over the next 18 months will determine whether QLED remains a differentiator or becomes table stakes in multiple product tiers.
- Supply-chain locking and capacity planning: Vertical and horizontal integration moves by material foundries and panel makers are reshaping bargaining leverage. With a few players controlling a significant share of production and materials, early capacity commitments (or failure to secure them) will materially affect cost, lead times, and innovation cadence.
- M&A and partnership timing: Given a concentrated supplier landscape, strategic acquisitions, minority-stake investments, or long-term supply agreements executed in 2026 will yield asymmetric returns. Our scenario work shows that well-timed consolidation or exclusive supply contracts can accelerate time-to-market while protecting margin.
- Regulatory and product-compliance planning: Materials and environmental compliance (notably the cadmium debate and cadmium-free alternatives) are central to go-to-market strategies. Certification and licensing decisions taken now will influence global distribution and brand positioning.
What PW Consulting’s full report delivers — practical, decision-focused content
This study is designed as a playbook for executives making near- to medium-term strategic choices. Highlights of the full report include (summarized at a high level to preserve strategic value):
Quantum Dot Display (QLED) Market
- Proprietary market sizing and a year-by-year historical series (2020–2025) with a transparent forecasting framework for 2026–2032, enabling sensitivity testing against price, adoption, and component-cost scenarios.
- Segment-level modelling by technology type, application, and region — with both baseline and upside cases — and a methodology appendix so clients can adapt scenarios to internal assumptions.
- Competitive intelligence dossiers on leading foundries, material innovators, and panel manufacturers, including capacities, strategic positioning, and capability maps.
- Actionable GTM playbooks for OEMs and material suppliers: pricing levers, channel strategies, and product roadmaps tailored to short-cycle consumer markets and longer-cycle automotive opportunities.
- M&A playbooks and value-capture models showing where consolidation, licensing, or joint manufacturing agreements create the most defensible value pools.
- Supply-chain risk matrix and mitigation blueprints addressing raw-material concentration, trade policy exposure, and manufacturing consolidation.
We deliberately avoid reproducing sensitive sub-segment numbers in this preview; the full report provides granular splits, share tables, and downloadable data files for client use.
Competitive landscape — who matters and why
The QLED ecosystem now features a mix of material foundries, component specialists, and panel integrators. Market concentration is meaningful: three firms account for a substantial portion of market revenue (CR3 ~65%), while the top five increase concentration further (CR5 ~72%). This structure creates both barriers and opportunities — incumbents can defend pricing and scale, but nimble specialists can capture high-margin adjacency with the right IP or partnerships.
- Nanosys, Inc. (Milpitas, CA) — A leading foundry and quantum dot material supplier that combines product R&D with wide-scale manufacturing partnerships. Nanosys’ foundry model and integration partnerships (including QD-OLED workstreams) make it a logical counterparty for OEMs seeking rapid deployment without internalizing material manufacturing.
- Shoei Chemical, Inc. (Tokyo) — As a vertically integrated advanced materials player, Shoei’s scale and its role in the production ramp of quantum dots give it strategic leverage. Its large-scale factory investments are shifting the supply curve for quantum dot films and materials.
- Samsung Electronics & Samsung Display (Seoul) — Samsung’s twin role as a consumer OEM and panel manufacturer makes it a pivotal adopter of quantum dot innovations. Certification initiatives and product launches are signaling downstream expectations for color performance and cadmium compliance.
- LG Display & Sony — Both players are advancing QD-OLED and QLED variants in premium home-entertainment portfolios; Sony’s integration of QD-OLED in Bravia and LG Display’s product introductions sharpen the competition at the high end.
- China-based panel makers (e.g., BOE, TCL) — These firms offer volume pathways and cost pressure; their adoption timelines and export strategies will determine how quickly premium quantum dot performance becomes accessible in volume markets.
- Nanoco Group (London) — A key player for cadmium-free quantum dots, Nanoco’s licensing and collaboration actions are relevant for firms seeking compliant material routes that mitigate regulatory risk.
Technology, materials and supply-chain dynamics
Three structural factors will determine winners and losers into 2026:
- Material performance vs. regulatory fit: Cadmium-containing quantum dots remain attractive for optical performance, but regulatory and brand-compliance pressures favour cadmium-free solutions. Licensing, certification, and partnerships (already in motion across the industry) will determine which materials scale commercially.
- Manufacturing scale and foundry economics: Large-scale production capacity — for example, foundry output measured in tens of millions of square meters annually — shifts unit costs and enables verticals such as automotive and professional displays to adopt QLED at scale. Early capacity investments translate directly into commercial leverage.
- Trade policy and raw material risk: Supply chains for rare earths and specialty components remain exposed to export controls and geopolitical friction. Restricted access to certain inputs can lengthen lead times and force supply reengineering, affecting both cost and time-to-market.
Recent industry signals illustrate these dynamics: prototype demonstrations highlighting improved color primitives, product launches embedding quantum dot sheets into mass-market TVs, and public certification moves all point to a commercialization phase where product differentiation is tightly coupled with supplier selection and compliance strategy.
Strategic actions for 2026 — a short playbook
- Secure optionality in supply: Negotiate multi-source supply agreements with staged volume commitments. Prioritize suppliers with validated scale and compliance credentials.
- Protect product roadmaps: Prioritize R&D investments that translate quantum-dot optical advantages into perceptible end-user benefits (brightness, color volume, power efficiency) rather than incremental spec battles.
- Use licensing and partnerships as force multipliers: Consider non-equity partnerships with material specialists to accelerate market entry while keeping capital intensity manageable.
- Embed regulatory & sustainability as commercial KPIs: Certification and cadmium-free positioning can drive premium placement and reduce go-to-market friction in regulated markets.
- Model M&A outcomes against concentration metrics: With the top three-to-five firms controlling a high share of market value, acquisitions or minority stakes can be an efficient route to secure technology or capacity — but valuation discipline is critical.
How PW Consulting recommends using this research in 2026
Use the full report as a decision engine: feed its scenario outputs into product-portfolio P&L models, link its supplier risk matrices to procurement playbooks, and use the company dossiers to prioritize partnership or M&A targets. For leadership teams, the report provides both the quantitative backbone and the qualitative narrative necessary to present coherent, defensible investment cases to boards or funding committees.
Final note — the value of the full analysis
This preview highlights trends and decision levers that will shape QLED strategies in 2026. For executives needing executable detail — regional and application-level forecasts, supplier scorecards, price-path assumptions, and downloadable model files — PW Consulting’s full report contains the granular data and strategic tools required to operationalize these insights. Access to the complete dataset and model allows you to stress-test scenarios against internal plans and to blueprint concrete agreements and roadmaps for the coming year.
Contact PW Consulting to obtain the full Quantum Dot Display (QLED) Market report and the accompanying data pack for scenario customization and boardroom-ready strategy materials.
For detailed analysis of this topic, please visit the official page: Quantum Dot Display (QLED) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Nickel Sulfate Market to Hit USD 10.94B by 2032 (12.45% CAGR)
By pmarketresearch, 2026-07-13
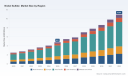
Nickel Sulfate Market — Strategic Imperatives for 2026
As environmental policy, electric-vehicle adoption, and regional industrial strategies accelerate demand for battery materials, nickel sulfate is transitioning from a niche industrial chemical to a cornerstone commodity in battery metals value chains. PW Consulting’s latest Nickel Sulfate Market study (base year 2025, forecasts through 2032, currency USD, revenue unit: Billion) translates this structural shift into actionable intelligence for executives preparing capital allocation, sourcing, and downstream integration decisions in 2026.
Nickel Sulfate Market
Why this report matters for 2026 decision-makers
-
Macro clarity when timing capital: The nickel sulfate market has expanded rapidly from the early 2020s into mid‑decade — rising from roughly USD 2.5 Billion in 2020 to about USD 4.8 Billion in 2025 — and is projected to exceed USD 10.9 Billion by 2032 under our central case, reflecting a compound annual growth rate of 12.45% across the 2026–2032 forecast window. Those magnitudes change project economics: payback periods, headroom for integrated refining projects, and the viability of green‑premium product lines.
Nickel Sulfate Market -
Concentration and counterparty selection: The market exhibits moderate concentration (CR3 ~48%, CR5 ~65%), which means top-tier producers exercise meaningful influence over near‑term availability and pricing. Commercial agreements and offtake structures will require negotiation strategies that reflect this asymmetry.
Nickel Sulfate Market -
Practical risk-to-reward view: With multiple sources of policy and feedstock volatility active across 2025–2026, the study provides timing-sensitive scenarios that distinguish transient price shocks from durable shifts in supply-demand balance — essential for procurement and investment committees acting in 2026.
Market trajectory — the numbers that shape strategy
From a PW Consulting vantage, the nickel sulfate market’s recent history and near-term forecast form a clear narrative. The five-year historical series (2020–2025) shows steady expansion, and our forecast (2026–2032) models continued robust growth driven by accelerating battery production, upstream metallurgical developments, and expanded refining capacity in regions pursuing onshore cathode precursor production. The market is expected to roughly double from mid‑decade levels by the early 2030s, which has direct implications for capacity planning, feedstock contracting, and capital markets positioning for companies that must decide in 2026 whether to build, expand, or vertically integrate.
Importantly, this growth is not uniform: price cycles, feedstock composition, regulatory shifts, and project execution timelines create materially different outcomes for near‑term cash flows versus long‑term strategic positioning. The report separates these layers to help leadership teams make differentiated choices for 2026 capital deployment versus longer‑term portfolio design.
What the PW Consulting report contains — operational, decision‑ready deliverables
-
Forward-looking demand model and alternative scenarios (policy-driven, technology-driven, and disrupted supply) with sensitivity analysis around battery chemistry mix and EV adoption pathways.
-
Comprehensive supply-side build‑out: an up-to-date project tracker covering announced refineries, conversions, and expansions, their estimated commissioning windows, and probabilistic capacity delivery timelines to 2032.
-
Feedstock flow models mapping ore, MHP/NPI streams, and refinery feed conversion routes — calibrated to recent upstream quota changes and price behaviour.
-
Price-formation framework linking upstream ore dynamics, refinery utilization, and short-term physical tightness to benchmark price scenarios and spot/contract spread outcomes.
-
Commercial playbook: offtake and tolling contract templates, counterparty risk heatmaps, and negotiation checklists designed for procurement and business development teams.
-
Project diligence tools: CAPEX/OPEX benchmarking, lifecycle carbon and water footprints, and permitting risk matrices tailored to regional jurisdictions.
-
Executive dashboards and investor‑ready narrative: a concise set of slides and briefings for C-suite decision cycles in 2026.
Note: the full report includes the granular regional and application splits, detailed price curves, and company-level capacity tables that are deliberately withheld in this preview to protect proprietary segment-level intelligence and to guide readers to the primary report for subscription access.
Competitive landscape — positioning and strategic moves to watch
The nickel sulfate value chain is populated by a mix of specialized chemical producers, battery-materials refineries, junior developers pursuing vertically integrated routes, and regional distributors. PW Consulting’s competitive scan emphasizes strategic positioning rather than exhaustive company metrics, focusing on capabilities, integration strategies, and execution risk.
-
Umicore (Belgium) — Global player with established production of battery‑grade nickel sulfate for cathode chemistries. Umicore’s strength lies in downstream integration and customer relationships with cathode and battery manufacturers, making it a bellwether for quality, traceability expectations, and sustainability premiums in offtake agreements.
-
Electra Battery Materials (Canada) — Focused on establishing North American refinery capacity. Recent contract awards and project progress indicate accelerated execution toward an Ontario refinery, which — if delivered on schedule — could reshuffle regional sourcing dynamics and offer nearshore alternatives to offshore refining for OEMs seeking supply chain resilience.
-
FPX Nickel (Canada) — Advancing downstream qualification via pilot production runs of battery‑grade crystals from awaruite concentrate. Their production runs and engagement with prospective EV supply-chain partners illustrate a pathway from unconventional feedstock to certified battery materials, highlighting technological pathways that could unlock non-traditional nickel sources.
-
Univerical (India) — Specializes in ultra‑high‑purity nickel sulfate with tight impurity controls. Suppliers like Univerical address a growing premium segment where cathode makers demand low-impurity feedstock for high‑energy cathodes and stricter quality control.
-
Ataman Chemical (Turkey) and Vrik Pharma (India) — Suppliers with broader industrial portfolios that anchor demand outside batteries (plating, catalysts, industrial chemicals). Their diversified end‑market exposure can smooth cyclicality but may limit focus on battery‑grade certification processes.
-
GEM Co., Ltd. (China) and Vivochem (Netherlands) — Represent high‑volume producers and distributors in established chemical markets, offering scale and logistical reach that serve both research and industrial customers; their inventories and distribution networks are important buffers during short‑term tightness.
In 2025–2026 the market has seen tactical moves that matter for 2026 strategy: FPX’s pilot‑scale production runs to secure battery‑grade qualification; Electra’s contract awards and reported emissions‑ and water‑reduction targets for its Ontario refinery; and a steady stream of project announcements that have compressed the window for first‑mover advantage in several regions. PW Consulting’s report maps these activities into competitive response options: from strategic JV structures to off‑take hedging and retrofit vs. greenfield decision trees.
Market dynamics, near-term noise, and policy risk
-
Policy and quotas: Indonesia’s revised nickel ore production quotas (announced January 2026) have important second‑order effects on downstream feedstock allocation and timing for converting upstream capacity into refined products. Companies with flexible feedstock strategies will be advantaged.
-
Price signals: Chinese nickel sulfate prices showed stabilization in early 2026 amid upstream feedstock adjustments, a sign that short-term volatility may be settling into new structural price ranges. Our scenarios distinguish transient spikes from multi‑year structural uplift that justifies incremental refinery CAPEX.
-
Trade and classification: Customs rulings and tariff classifications (including U.S. determinations in 2025) have created friction in cross‑border flows, affecting landed costs and compelling multinational buyers to reassess sourcing matrices and origin clauses in contracts.
-
Environmental differentiation: Projects emphasizing lower CO2 and water footprints (for example, an Ontario refinery design claiming substantial reductions versus offshore refining) will capture a sustainability premium with OEMs and financiers; integrating lifecycle footprints into commercial terms is increasingly material.
Strategic actions for 2026 — a short playbook
-
Treat 2026 as the last low‑regret window for capacity commitments: With the market visibility provided by our forecast, investors and industrials should prioritize options and modular designs that allow staged capacity additions synchronized with validated demand signals and offtake commitments.
-
Lock feedstock optionality: Secure diversified feed streams (MHP/NPI, sulfide concentrates, non‑traditional sources) and build contractual flexibility to route material to the most economic processing path as premiums for low‑impurity, low‑carbon product variants emerge.
-
Embed sustainability metrics into commercial terms: Demand from battery OEMs for low‑carbon, transparent supply chains is not merely reputational; it increasingly influences price and allocation. Integrate lifecycle reporting into offtake and financing documentation.
-
Prioritize counterparty resilience over marginal cost advantage: With moderate market concentration, evaluate counterparty credit, execution track record, and logistics redundancy as primary procurement criteria.
How executives should use this study in 2026
Use the study as a decision‑support system: run the provided scenarios through capital allocation committees, use the project‑level tracker to stress test commissioning risk in your region of interest, and adopt the commercial templates to accelerate contracted supply arrangements. For M&A teams, our capacity and concentration analysis narrows target lists and identifies where synergies are likely to pass through to margin or secure offtake. For procurement leaders, the price‑formation framework and counterparty heatmaps convert market forecasts into negotiation levers.
Next steps
PW Consulting’s Nickel Sulfate Market study delivers the quantitative backbone and the pragmatic roadmaps that executives need to act confidently in 2026. The analysis is intentionally framed to reveal strategic levers and operational options while protecting the granular segment tables that drive execution. For access to the complete dataset, regional and application breakdowns, and the proprietary project trackers referenced here, please consult the full report via PW Consulting’s distribution channels.
In a market characterized by rapid growth, policy flux, and technological divergence, 2026 will separate organizations that claim share through disciplined, optional, and sustainability‑aligned investments from those forced into reactive sourcing. This study is designed to put your leadership team in the former category.
For detailed analysis of this topic, please visit the official page: Nickel Sulfate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Oil-Free Compressor Market to Hit USD 26.93 Billion by 2032 at 4.82% CAGR
By pmarketresearch, 2026-07-13
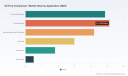
Oil-Free Compressor Market — 2026 Strategic Briefing
This briefing, prepared by PW Consulting’s senior strategy team, introduces our latest Oil Free Compressor Market research and explains its practical value for 2026 corporate decision‑making. The intent is to demonstrate the analytical depth, scenario rigor, and decision-ready outputs contained in the full study while preserving the proprietary micro‑segmentation and granular financial tables that clients access through the full report.
Oil Free Compressor Market
Market snapshot — what the macro data means for planning
Using 2025 as the base year, our topline market sizing shows the oil‑free compressor industry as a stable, expanding industrial equipment market. The report’s historical series (2020–2025) captures the sector’s recovery from pandemic supply‑chain distortion and cyclical slowdowns, and the forecast window (2026–2032) models a compound annual growth rate of 4.82%. In cash terms, the global revenue pool moves from USD 19.5 billion in 2025 to an anticipated USD 26.93 billion by 2032, with an inflection already visible in 2026.
Oil Free Compressor Market
Why this matters for 2026 decisions: a near‑term uptick in addressable demand coupled with a mid‑term steady growth trajectory creates a policy environment where near‑term capital allocation, supplier selection, and product road‑mapping choices have multi‑year payback and strategic impact. In other words, choices made in 2026 about platform design, energy efficiency investments, and go‑to‑market emphasis are likely to determine competitive positioning into the early 2030s.
Oil Free Compressor Market
Key structural dynamics shaping strategy
-
Regulatory and standards pressure: Governments and standards bodies are tightening both efficiency and purity requirements. Two salient items: Department of Energy efficiency requirements for rotary compressors (effective January 2025) raise the benchmark for isentropic efficiency across size bands; and ISO 8573‑1 Class 0 remains the de facto global specification for guaranteed oil‑free air in contamination‑sensitive industries. These create procurement floors and design must‑haves for OEMs and end users alike.
-
Purity‑sensitive end markets expanding: Food & beverage, pharmaceuticals, and semiconductor/electronics are intensifying adoption of 100% oil‑free systems to mitigate contamination risk and regulatory exposure. That demand is driving product innovation and premiumization in both rotating and reciprocating platforms.
-
Energy and lifecycle economics dominate capex decisions: Variable‑speed drives, system integration, and optimized heat recovery materially change total cost of ownership. With tougher efficiency regulations and higher energy cost volatility, purchasing decisions are shifting from lowest‑capex to lowest‑lifecycle‑cost models.
-
Supply chain and raw material constraints: Oil‑free screw compressors use aluminum and steel forgings, specialized rotors and bearings—all of which are subject to supply and input‑cost cycles. Procurement strategies that lock in raw material pricing or diversify suppliers can materially reduce project risk.
-
Competitive fragmentation with consolidation potential: Market concentration at the top end is moderate (the three largest vendors do not dominate fully), leaving space for differentiation, regional champions, and targeted M&A to improve scale and aftermarket reach.
How the report supports concrete 2026 decisions
The full PW Consulting report is designed as a decision toolkit, not an academic exercise. It bundles the quantitative market forecast with templates and frameworks you can apply immediately:
-
Capex vs retrofit playbooks — a modular decision tree and ROI model that compares replacement, retrofitting, and staged upgrades across efficiency scenarios and regulatory outcomes.
-
Procurement and specification templates — compliant spec language (including ISO Class 0, DOE efficiency thresholds, and test protocols) that legal and purchasing teams can drop into RFPs.
-
TCO calculators — configurable models that incorporate energy tariffs, duty cycles, maintenance regimes, and residual values to reveal true lifecycle cost differentials across platforms and vendors.
-
Vendor due‑diligence scorecards and supplier risk heatmaps — standardized templates to rate OEMs on technology, service footprint, spare‑parts availability, and financial resilience.
-
Scenario and sensitivity analyses — three strategic scenarios (baseline demand growth, accelerated premiumization from tightening purity rules, and downside commodity‑price shock) with implications for capacity planning and inventory buffers.
-
M&A and partnership playbook — identification criteria for bolt‑on assets (service networks, aftermarket-tech platforms, regional manufacturing) and an M&A valuation grid tuned to the oil‑free compressor economics.
Competitive landscape — positioning and implications
The report profiles leading OEMs and maps their strategic strengths, R&D focus, and go‑to‑market footprints. Highlights include:
-
Atlas Copco (Sweden): A recognized pioneer of ISO Class 0 technology with breadth across rotary screw, centrifugal, scroll, and piston platforms. Atlas Copco’s recent product expansion targeting pharmaceutical‑grade reliability underlines its play for high‑value, purity‑sensitive accounts.
-
Ingersoll Rand (United States): Strong in variable‑speed, energy‑efficient rotary screw systems and recognized for broad industrial penetration and aftermarket capabilities that reduce customer lifecycle costs.
-
Sullair (United States): Known for co‑engineering and rigorous industrial performance; its collaborations (including historic ties with Hitachi engineering) position it well in heavy industrial and utility environments.
-
Gardner Denver, Kobelco, Quincy, Hertz Kompressoren, and Worthington Creyssensac: Each brings differentiated engineering approaches (dry screw, water‑injected screw, scroll, piston) and regional strengths useful for targeted competitive plays—OEM selection should be driven by technical fit, aftermarket coverage, and local service density rather than brand alone.
-
Market structure note: concentration metrics indicate a moderately fragmented market—there are scale advantages to be gained through targeted consolidation (service networks, spare parts logistics, and digital remote‑monitoring platforms are high‑value consolidation targets).
Recent industry movements — what to watch in 2026
-
Atlas Copco expanded its oil‑free range in mid‑2025, explicitly targeting pharmaceutical air‑purity requirements — a signal that vendors are accelerating product launches aimed at regulatory‑driven opportunities.
-
ELGi showcased new oil‑free product lines and demand‑management tech in late 2025, pointing to cross‑industry interest (including automotive aftermarket applications) in cleaner compressed air solutions.
-
Garrett’s early‑2026 launch of high‑capacity oil‑free centrifugal models illustrates the rising importance of large, centralized compressed‑air plants for data centers, large manufacturing, and cold chain applications.
Practical 90‑day and 12‑month action plans for 2026
-
Next 90 days (tactical):
- Mandate ISO Class 0 (or equivalent) language in new procurement RFPs for contamination‑sensitive lines.
- Run a prioritized TCO review on the top 20% of compressor fleet spend by energy consumption and age; identify 2–3 immediate retrofit candidates.
- Initiate vendor scorecard assessments for current suppliers to expose single‑source dependencies on parts and bearings.
-
12 months (strategic):
- Develop a three‑year capital roadmap that phases in variable‑speed and heat‑recovery modules where lifecycle economics are favorable.
- Pursue strategic partnerships or targeted M&A to expand aftermarket reach in priority regions or to acquire digital monitoring capabilities that lower O&M costs.
- Model and stress‑test the supply chain for aluminum/steel/rotor component constraints and obtain alternate qualification plans.
Why the full report is strategic intelligence, not just data
Our report combines the headline market model with executable deliverables: procurement templates, TCO models, vendor diagnostics, and M&A screens. It translates the macro numbers into operational directives—what to buy, when to upgrade, which vendors to partner with, and how to hedge regulatory and commodity risks in capital planning.
Because the most valuable parts of the study are the proprietary segmentation matrices, price and volume overlays, and granular competitive benchmarking (which underpin vendor selection and M&A screens), those datasets are intentionally gated in the full report. This “trailer” approach shows the analytical spine while preserving the detailed intelligence that directly drives commercial advantage.
Next steps
If your 2026 strategy includes capex for manufacturing reliability, a push to lower lifecycle energy costs, or a plan to expand service and aftermarket revenues, PW Consulting’s full Oil Free Compressor Market report provides the operational blueprints. To convert the market’s 4.82% CAGR and the underlying demand shifts into prioritized investment and sourcing decisions, request the full report and the accompanying toolkit for immediate adoption.
For detailed analysis of this topic, please visit the official page: Oil Free Compressor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com