

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Non-dairy Creamer Market to reach USD 3,025M by 2032 at 5.82% CAGR

Non-dairy Creamer Market 2026: Strategic Preview for Executive Decision-Making
PW Consulting presents a condensed strategic preview of our full Non-dairy Creamer Market study — positioned to inform executive decision-making in 2026. The market is no longer a peripheral category; it sits at the intersection of shifting consumer diets, ingredient-cost volatility, and an evolving regulatory landscape. This preview outlines the macro trajectory, critical dynamics, competitive posture, and the practical decision tools contained in the full report. It is intentionally diagnostic rather than exhaustive: we surface the strategic implications and proprietary frameworks you will need, while reserving granular segment tables and detailed supplier-level data for the full release available on our website.
Non-dairy Creamer Market
Why this study matters for 2026 decisions
-
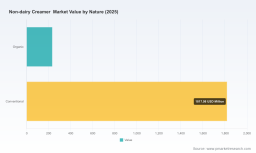
Measured momentum: The category’s trajectory is resilient. With a 2025 base of USD 2,050 Million (base year) and a forecast through 2032 at an industry compound annual growth rate (CAGR) of 5.82%, the market presents a clear expansion pathway for incumbents and new entrants alike. By 2032 the market is projected to approach USD 3.025 Billion, representing a meaningful addressable opportunity for product innovation, channel expansion, and consolidation plays.
Non-dairy Creamer Market -
Tightening commercial margins: Rising input costs for plant-based feedstocks — almond, coconut, oat and soy — and ongoing logistics pressure are compressing gross margins for many producers. The economics of formulation, scale manufacturing, and price pass‑through are therefore central to 2026 budgeting and sourcing decisions.
Non-dairy Creamer Market -
Regulatory & recall risk is front‑and‑center: Recent high‑profile recalls and tightening FDA guidance make allergen controls, labeling accuracy, and FSVP compliance non‑negotiable for market access. These risks have direct implications for private-label suppliers, co‑packers, and import-reliant brands.
What the full PW Consulting study delivers (high-level)
The report blends market sizing, scenario forecasting, competitor benchmarking, and hands‑on execution tools. Key deliverables include:
-
Top‑down and bottom‑up market sizing with a 2026–2032 forecast built on demand drivers and price trends.
-
Demand-driver analytics that quantify the impact of health positioning, flavor innovation, and foodservice recovery on category growth.
-
Supply‑chain and input‑cost models that allow you to stress test margin scenarios under multiple commodity and logistics regimes.
-
Regulatory and recall playbook: compliance checklists, label‑review matrixes, and an incident response simulation tailored to non‑dairy creamer formulations.
-
Commercial frameworks: SKU rationalization tools, channel prioritization matrices, and a retailer negotiation playbook informed by current private‑label dynamics.
-
M&A and partnership screening methodology: a prioritized shortlist of strategic acquisition archetypes and the valuation levers that matter in 2026—2028.
Market dynamics you cannot ignore
-
Ingredient economics: Plant‑based feedstocks command a price premium relative to conventional dairy inputs. This dynamic materially alters formulation choices, affects placement of premium vs. value SKUs, and increases the importance of long‑term procurement contracts and hedging strategies.
-
Labeling & allergen control: Recent events — including a Class I recall tied to undeclared milk allergen — and updated FDA guidance emphasize that “non‑dairy” labeling is not a regulatory safe harbor. Manufacturers must ensure ingredient transparency and robust supplier verification to avoid market‑stopping recalls.
-
Trade & import scrutiny: Intensified FSVP inspections and import alerts mean import‑reliant players must invest in traceability and foreign supplier governance to preserve access to key markets.
-
Channel blend evolution: Retail premiumization and foodservice demand for barista‑grade behaviorally consistent creamers are creating bifurcated opportunities — premium, clean‑label formats vs. large‑volume industrial and foodservice formats.
Competitive landscape — synthesis and strategic takeaways
The market exhibits moderate concentration, with the combined market share of the top three and top five firms indicating room for both scale advantages and regional entrants. The competitive set spans large multinational CPG players, agile plant‑based specialists, and regional bulk manufacturers. Below we synthesize the strategic posture of representative players and the implications for 2026 strategy.
-
Nestlé: Leverages scale, shelf‑space relationships and strong foodservice channels. Advantage lies in distribution depth and brand familiarity; risk centers on speed of innovation against nimble plant‑based specialists.
-
Danone: Plays the plant‑forward portfolio and reduced‑sugar propositions into retailer health objectives. Strategic implication: incumbents must defend through both formulation and value communication.
-
Oatly and Califia Farms: Specialists with strong clean‑label and oat‑centric narratives. Their strengths are ingredient authenticity and brand positioning; their constraints are scale and ingredient cost exposure — ideal partners for premium placement or co‑development deals.
-
Chobani, Nutpods, Elmhurst, Ripple: Positioned on product innovation, flavor variety, and targeted health claims (unsweetened, high‑protein, lentil‑based). These players demonstrate the tactical value of niche differentiation combined with purposeful channel strategies.
-
Native Forest and specialty regional manufacturers (e.g., OEMs in China): Offer competitively priced, high‑volume supply for industrial and private‑label channels. Strategic considerations: sourcing reliability and regulatory transparency are critical when engaging with bulk suppliers.
Strategic implications: incumbents should pair scale‑driven efficiencies (pricing and distribution) with targeted innovation to defend premium niches. New entrants can win via credible clean‑label claims, targeted channel focus (e.g., specialty coffee or online DTC), and partnerships that mitigate ingredient and compliance risk.
Recent industry events that change the playbook
-
Product recalls and allergen enforcement: A high‑risk Class I recall in 2025 for undeclared milk allergen underscores the immediate commercial damage of labeling failures. Companies must treat allergen control as a board‑level risk item, not an operational checkbox.
-
New product launches: Several large and emerging brands expanded into flavored and simplified‑ingredient creamers in 2025–2026, reflecting retailer appetite for clean‑label, low‑sugar alternatives. These launches validate demand but also compress premiumization windows as more SKUs chase the same shelf space.
-
Regulatory enforcement: FDA import alerts and FSVP audits have real consequences for importers and private‑label supply chains. Investment in supplier verification and traceability technology is no longer discretionary.
Actionable recommendations for 2026
-
Reassess supplier strategy: Prioritize dual‑sourcing for critical plant inputs and formalize long‑term contracts to stabilise costs. For importers, accelerate FSVP remediation and third‑party audits before market entry.
-
Optimize SKU architecture: Use our SKU rationalization template to identify which formulations to scale, simplify or sunset. Focus R&D spend on clean‑label, low‑sugar and barista‑grade functionalities that command premium margins.
-
Invest in labeling and traceability: Implement a labeling governance framework, routine label audits, and real‑time ingredient traceability to reduce recall probability and speed incident response.
-
Prepare for strategic M&A: Target acquisition archetypes include regional co‑packers with compliant supply chains, ingredient technology startups that reduce cost‑in‑use, and brands with loyal DTC followings. Use our valuation levers to prioritize targets.
-
Scenario planning for commodity shocks: Run our three‑scenario margin model (base, stress, severe) over your 2026 P&L to set defensible pricing and promotional strategies.
What’s reserved for the full report
To preserve the utility of our proprietary analysis, the full report contains the detailed segment-level tables, regional and application splits, SKU-level pricing forecasts, and a prioritized supplier directory. It also includes downloadable tools — supplier scorecards, a recall simulation workbook, and a channel prioritization matrix — that translate insight into executable plans. These items are intentionally withheld from this preview to drive direct engagement with the study and ensure strategic exclusivity for subscribing clients.
How PW Consulting can assist
-
Customized briefings: We provide executive workshops that translate report findings into 90‑day tactical roadmaps.
-
Due diligence & M&A support: Target screening, commercial diligence, and post‑deal integration plans tailored to non‑dairy creamer assets.
-
Operational playbooks: Co‑development of supplier governance, allergen control programs, and barista‑grade manufacturing checklists.
In a market growing at an anticipated 5.82% CAGR from 2026 to 2032 and expanding from a USD 2,050 Million base in 2025 to an expected USD 3,025 Million by 2032, the strategic edges will be held by organizations that combine commercial scale, ingredient foresight, and uncompromising regulatory controls. PW Consulting’s full Non‑dairy Creamer Market study equips leadership teams with the modeling, competitive intelligence, and practical tools to act quickly and confidently in 2026. For access to the complete dataset, segmented forecasts, and operational toolkits, please visit our report page.
For detailed analysis of this topic, please visit the official page: Non-dairy Creamer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com