

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Oil-Free Compressor Market to Hit USD 26.93 Billion by 2032 at 4.82% CAGR

Oil-Free Compressor Market — 2026 Strategic Briefing
This briefing, prepared by PW Consulting’s senior strategy team, introduces our latest Oil Free Compressor Market research and explains its practical value for 2026 corporate decision‑making. The intent is to demonstrate the analytical depth, scenario rigor, and decision-ready outputs contained in the full study while preserving the proprietary micro‑segmentation and granular financial tables that clients access through the full report.
Oil Free Compressor Market
Market snapshot — what the macro data means for planning
Using 2025 as the base year, our topline market sizing shows the oil‑free compressor industry as a stable, expanding industrial equipment market. The report’s historical series (2020–2025) captures the sector’s recovery from pandemic supply‑chain distortion and cyclical slowdowns, and the forecast window (2026–2032) models a compound annual growth rate of 4.82%. In cash terms, the global revenue pool moves from USD 19.5 billion in 2025 to an anticipated USD 26.93 billion by 2032, with an inflection already visible in 2026.
Oil Free Compressor Market
Why this matters for 2026 decisions: a near‑term uptick in addressable demand coupled with a mid‑term steady growth trajectory creates a policy environment where near‑term capital allocation, supplier selection, and product road‑mapping choices have multi‑year payback and strategic impact. In other words, choices made in 2026 about platform design, energy efficiency investments, and go‑to‑market emphasis are likely to determine competitive positioning into the early 2030s.
Oil Free Compressor Market
Key structural dynamics shaping strategy
-
Regulatory and standards pressure: Governments and standards bodies are tightening both efficiency and purity requirements. Two salient items: Department of Energy efficiency requirements for rotary compressors (effective January 2025) raise the benchmark for isentropic efficiency across size bands; and ISO 8573‑1 Class 0 remains the de facto global specification for guaranteed oil‑free air in contamination‑sensitive industries. These create procurement floors and design must‑haves for OEMs and end users alike.
-
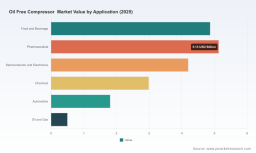
Purity‑sensitive end markets expanding: Food & beverage, pharmaceuticals, and semiconductor/electronics are intensifying adoption of 100% oil‑free systems to mitigate contamination risk and regulatory exposure. That demand is driving product innovation and premiumization in both rotating and reciprocating platforms.
-
Energy and lifecycle economics dominate capex decisions: Variable‑speed drives, system integration, and optimized heat recovery materially change total cost of ownership. With tougher efficiency regulations and higher energy cost volatility, purchasing decisions are shifting from lowest‑capex to lowest‑lifecycle‑cost models.
-
Supply chain and raw material constraints: Oil‑free screw compressors use aluminum and steel forgings, specialized rotors and bearings—all of which are subject to supply and input‑cost cycles. Procurement strategies that lock in raw material pricing or diversify suppliers can materially reduce project risk.
-
Competitive fragmentation with consolidation potential: Market concentration at the top end is moderate (the three largest vendors do not dominate fully), leaving space for differentiation, regional champions, and targeted M&A to improve scale and aftermarket reach.
How the report supports concrete 2026 decisions
The full PW Consulting report is designed as a decision toolkit, not an academic exercise. It bundles the quantitative market forecast with templates and frameworks you can apply immediately:
-
Capex vs retrofit playbooks — a modular decision tree and ROI model that compares replacement, retrofitting, and staged upgrades across efficiency scenarios and regulatory outcomes.
-
Procurement and specification templates — compliant spec language (including ISO Class 0, DOE efficiency thresholds, and test protocols) that legal and purchasing teams can drop into RFPs.
-
TCO calculators — configurable models that incorporate energy tariffs, duty cycles, maintenance regimes, and residual values to reveal true lifecycle cost differentials across platforms and vendors.
-
Vendor due‑diligence scorecards and supplier risk heatmaps — standardized templates to rate OEMs on technology, service footprint, spare‑parts availability, and financial resilience.
-
Scenario and sensitivity analyses — three strategic scenarios (baseline demand growth, accelerated premiumization from tightening purity rules, and downside commodity‑price shock) with implications for capacity planning and inventory buffers.
-
M&A and partnership playbook — identification criteria for bolt‑on assets (service networks, aftermarket-tech platforms, regional manufacturing) and an M&A valuation grid tuned to the oil‑free compressor economics.
Competitive landscape — positioning and implications
The report profiles leading OEMs and maps their strategic strengths, R&D focus, and go‑to‑market footprints. Highlights include:
-
Atlas Copco (Sweden): A recognized pioneer of ISO Class 0 technology with breadth across rotary screw, centrifugal, scroll, and piston platforms. Atlas Copco’s recent product expansion targeting pharmaceutical‑grade reliability underlines its play for high‑value, purity‑sensitive accounts.
-
Ingersoll Rand (United States): Strong in variable‑speed, energy‑efficient rotary screw systems and recognized for broad industrial penetration and aftermarket capabilities that reduce customer lifecycle costs.
-
Sullair (United States): Known for co‑engineering and rigorous industrial performance; its collaborations (including historic ties with Hitachi engineering) position it well in heavy industrial and utility environments.
-
Gardner Denver, Kobelco, Quincy, Hertz Kompressoren, and Worthington Creyssensac: Each brings differentiated engineering approaches (dry screw, water‑injected screw, scroll, piston) and regional strengths useful for targeted competitive plays—OEM selection should be driven by technical fit, aftermarket coverage, and local service density rather than brand alone.
-
Market structure note: concentration metrics indicate a moderately fragmented market—there are scale advantages to be gained through targeted consolidation (service networks, spare parts logistics, and digital remote‑monitoring platforms are high‑value consolidation targets).
Recent industry movements — what to watch in 2026
-
Atlas Copco expanded its oil‑free range in mid‑2025, explicitly targeting pharmaceutical air‑purity requirements — a signal that vendors are accelerating product launches aimed at regulatory‑driven opportunities.
-
ELGi showcased new oil‑free product lines and demand‑management tech in late 2025, pointing to cross‑industry interest (including automotive aftermarket applications) in cleaner compressed air solutions.
-
Garrett’s early‑2026 launch of high‑capacity oil‑free centrifugal models illustrates the rising importance of large, centralized compressed‑air plants for data centers, large manufacturing, and cold chain applications.
Practical 90‑day and 12‑month action plans for 2026
-
Next 90 days (tactical):
- Mandate ISO Class 0 (or equivalent) language in new procurement RFPs for contamination‑sensitive lines.
- Run a prioritized TCO review on the top 20% of compressor fleet spend by energy consumption and age; identify 2–3 immediate retrofit candidates.
- Initiate vendor scorecard assessments for current suppliers to expose single‑source dependencies on parts and bearings.
-
12 months (strategic):
- Develop a three‑year capital roadmap that phases in variable‑speed and heat‑recovery modules where lifecycle economics are favorable.
- Pursue strategic partnerships or targeted M&A to expand aftermarket reach in priority regions or to acquire digital monitoring capabilities that lower O&M costs.
- Model and stress‑test the supply chain for aluminum/steel/rotor component constraints and obtain alternate qualification plans.
Why the full report is strategic intelligence, not just data
Our report combines the headline market model with executable deliverables: procurement templates, TCO models, vendor diagnostics, and M&A screens. It translates the macro numbers into operational directives—what to buy, when to upgrade, which vendors to partner with, and how to hedge regulatory and commodity risks in capital planning.
Because the most valuable parts of the study are the proprietary segmentation matrices, price and volume overlays, and granular competitive benchmarking (which underpin vendor selection and M&A screens), those datasets are intentionally gated in the full report. This “trailer” approach shows the analytical spine while preserving the detailed intelligence that directly drives commercial advantage.
Next steps
If your 2026 strategy includes capex for manufacturing reliability, a push to lower lifecycle energy costs, or a plan to expand service and aftermarket revenues, PW Consulting’s full Oil Free Compressor Market report provides the operational blueprints. To convert the market’s 4.82% CAGR and the underlying demand shifts into prioritized investment and sourcing decisions, request the full report and the accompanying toolkit for immediate adoption.
For detailed analysis of this topic, please visit the official page: Oil Free Compressor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com