

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Nickel Sulfate Market to Hit USD 10.94B by 2032 (12.45% CAGR)

Nickel Sulfate Market — Strategic Imperatives for 2026
As environmental policy, electric-vehicle adoption, and regional industrial strategies accelerate demand for battery materials, nickel sulfate is transitioning from a niche industrial chemical to a cornerstone commodity in battery metals value chains. PW Consulting’s latest Nickel Sulfate Market study (base year 2025, forecasts through 2032, currency USD, revenue unit: Billion) translates this structural shift into actionable intelligence for executives preparing capital allocation, sourcing, and downstream integration decisions in 2026.
Nickel Sulfate Market
Why this report matters for 2026 decision-makers
-
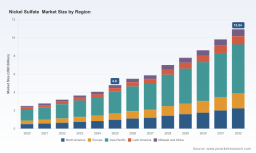
Macro clarity when timing capital: The nickel sulfate market has expanded rapidly from the early 2020s into mid‑decade — rising from roughly USD 2.5 Billion in 2020 to about USD 4.8 Billion in 2025 — and is projected to exceed USD 10.9 Billion by 2032 under our central case, reflecting a compound annual growth rate of 12.45% across the 2026–2032 forecast window. Those magnitudes change project economics: payback periods, headroom for integrated refining projects, and the viability of green‑premium product lines.
Nickel Sulfate Market -
Concentration and counterparty selection: The market exhibits moderate concentration (CR3 ~48%, CR5 ~65%), which means top-tier producers exercise meaningful influence over near‑term availability and pricing. Commercial agreements and offtake structures will require negotiation strategies that reflect this asymmetry.
Nickel Sulfate Market -
Practical risk-to-reward view: With multiple sources of policy and feedstock volatility active across 2025–2026, the study provides timing-sensitive scenarios that distinguish transient price shocks from durable shifts in supply-demand balance — essential for procurement and investment committees acting in 2026.
Market trajectory — the numbers that shape strategy
From a PW Consulting vantage, the nickel sulfate market’s recent history and near-term forecast form a clear narrative. The five-year historical series (2020–2025) shows steady expansion, and our forecast (2026–2032) models continued robust growth driven by accelerating battery production, upstream metallurgical developments, and expanded refining capacity in regions pursuing onshore cathode precursor production. The market is expected to roughly double from mid‑decade levels by the early 2030s, which has direct implications for capacity planning, feedstock contracting, and capital markets positioning for companies that must decide in 2026 whether to build, expand, or vertically integrate.
Importantly, this growth is not uniform: price cycles, feedstock composition, regulatory shifts, and project execution timelines create materially different outcomes for near‑term cash flows versus long‑term strategic positioning. The report separates these layers to help leadership teams make differentiated choices for 2026 capital deployment versus longer‑term portfolio design.
What the PW Consulting report contains — operational, decision‑ready deliverables
-
Forward-looking demand model and alternative scenarios (policy-driven, technology-driven, and disrupted supply) with sensitivity analysis around battery chemistry mix and EV adoption pathways.
-
Comprehensive supply-side build‑out: an up-to-date project tracker covering announced refineries, conversions, and expansions, their estimated commissioning windows, and probabilistic capacity delivery timelines to 2032.
-
Feedstock flow models mapping ore, MHP/NPI streams, and refinery feed conversion routes — calibrated to recent upstream quota changes and price behaviour.
-
Price-formation framework linking upstream ore dynamics, refinery utilization, and short-term physical tightness to benchmark price scenarios and spot/contract spread outcomes.
-
Commercial playbook: offtake and tolling contract templates, counterparty risk heatmaps, and negotiation checklists designed for procurement and business development teams.
-
Project diligence tools: CAPEX/OPEX benchmarking, lifecycle carbon and water footprints, and permitting risk matrices tailored to regional jurisdictions.
-
Executive dashboards and investor‑ready narrative: a concise set of slides and briefings for C-suite decision cycles in 2026.
Note: the full report includes the granular regional and application splits, detailed price curves, and company-level capacity tables that are deliberately withheld in this preview to protect proprietary segment-level intelligence and to guide readers to the primary report for subscription access.
Competitive landscape — positioning and strategic moves to watch
The nickel sulfate value chain is populated by a mix of specialized chemical producers, battery-materials refineries, junior developers pursuing vertically integrated routes, and regional distributors. PW Consulting’s competitive scan emphasizes strategic positioning rather than exhaustive company metrics, focusing on capabilities, integration strategies, and execution risk.
-
Umicore (Belgium) — Global player with established production of battery‑grade nickel sulfate for cathode chemistries. Umicore’s strength lies in downstream integration and customer relationships with cathode and battery manufacturers, making it a bellwether for quality, traceability expectations, and sustainability premiums in offtake agreements.
-
Electra Battery Materials (Canada) — Focused on establishing North American refinery capacity. Recent contract awards and project progress indicate accelerated execution toward an Ontario refinery, which — if delivered on schedule — could reshuffle regional sourcing dynamics and offer nearshore alternatives to offshore refining for OEMs seeking supply chain resilience.
-
FPX Nickel (Canada) — Advancing downstream qualification via pilot production runs of battery‑grade crystals from awaruite concentrate. Their production runs and engagement with prospective EV supply-chain partners illustrate a pathway from unconventional feedstock to certified battery materials, highlighting technological pathways that could unlock non-traditional nickel sources.
-
Univerical (India) — Specializes in ultra‑high‑purity nickel sulfate with tight impurity controls. Suppliers like Univerical address a growing premium segment where cathode makers demand low-impurity feedstock for high‑energy cathodes and stricter quality control.
-
Ataman Chemical (Turkey) and Vrik Pharma (India) — Suppliers with broader industrial portfolios that anchor demand outside batteries (plating, catalysts, industrial chemicals). Their diversified end‑market exposure can smooth cyclicality but may limit focus on battery‑grade certification processes.
-
GEM Co., Ltd. (China) and Vivochem (Netherlands) — Represent high‑volume producers and distributors in established chemical markets, offering scale and logistical reach that serve both research and industrial customers; their inventories and distribution networks are important buffers during short‑term tightness.
In 2025–2026 the market has seen tactical moves that matter for 2026 strategy: FPX’s pilot‑scale production runs to secure battery‑grade qualification; Electra’s contract awards and reported emissions‑ and water‑reduction targets for its Ontario refinery; and a steady stream of project announcements that have compressed the window for first‑mover advantage in several regions. PW Consulting’s report maps these activities into competitive response options: from strategic JV structures to off‑take hedging and retrofit vs. greenfield decision trees.
Market dynamics, near-term noise, and policy risk
-
Policy and quotas: Indonesia’s revised nickel ore production quotas (announced January 2026) have important second‑order effects on downstream feedstock allocation and timing for converting upstream capacity into refined products. Companies with flexible feedstock strategies will be advantaged.
-
Price signals: Chinese nickel sulfate prices showed stabilization in early 2026 amid upstream feedstock adjustments, a sign that short-term volatility may be settling into new structural price ranges. Our scenarios distinguish transient spikes from multi‑year structural uplift that justifies incremental refinery CAPEX.
-
Trade and classification: Customs rulings and tariff classifications (including U.S. determinations in 2025) have created friction in cross‑border flows, affecting landed costs and compelling multinational buyers to reassess sourcing matrices and origin clauses in contracts.
-
Environmental differentiation: Projects emphasizing lower CO2 and water footprints (for example, an Ontario refinery design claiming substantial reductions versus offshore refining) will capture a sustainability premium with OEMs and financiers; integrating lifecycle footprints into commercial terms is increasingly material.
Strategic actions for 2026 — a short playbook
-
Treat 2026 as the last low‑regret window for capacity commitments: With the market visibility provided by our forecast, investors and industrials should prioritize options and modular designs that allow staged capacity additions synchronized with validated demand signals and offtake commitments.
-
Lock feedstock optionality: Secure diversified feed streams (MHP/NPI, sulfide concentrates, non‑traditional sources) and build contractual flexibility to route material to the most economic processing path as premiums for low‑impurity, low‑carbon product variants emerge.
-
Embed sustainability metrics into commercial terms: Demand from battery OEMs for low‑carbon, transparent supply chains is not merely reputational; it increasingly influences price and allocation. Integrate lifecycle reporting into offtake and financing documentation.
-
Prioritize counterparty resilience over marginal cost advantage: With moderate market concentration, evaluate counterparty credit, execution track record, and logistics redundancy as primary procurement criteria.
How executives should use this study in 2026
Use the study as a decision‑support system: run the provided scenarios through capital allocation committees, use the project‑level tracker to stress test commissioning risk in your region of interest, and adopt the commercial templates to accelerate contracted supply arrangements. For M&A teams, our capacity and concentration analysis narrows target lists and identifies where synergies are likely to pass through to margin or secure offtake. For procurement leaders, the price‑formation framework and counterparty heatmaps convert market forecasts into negotiation levers.
Next steps
PW Consulting’s Nickel Sulfate Market study delivers the quantitative backbone and the pragmatic roadmaps that executives need to act confidently in 2026. The analysis is intentionally framed to reveal strategic levers and operational options while protecting the granular segment tables that drive execution. For access to the complete dataset, regional and application breakdowns, and the proprietary project trackers referenced here, please consult the full report via PW Consulting’s distribution channels.
In a market characterized by rapid growth, policy flux, and technological divergence, 2026 will separate organizations that claim share through disciplined, optional, and sustainability‑aligned investments from those forced into reactive sourcing. This study is designed to put your leadership team in the former category.
For detailed analysis of this topic, please visit the official page: Nickel Sulfate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com