

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Procalcitonin Market Set to Reach USD 365.4M by 2032 with 6.98% CAGR

Procalcitonin (CAS 56645-65-9) Market 2026: Strategic Imperatives for Corporate Decision‑Makers
As PW Consulting’s lead industry strategist, I present a high‑caliber, executive‑level orientation to our Procalcitonin (PCT) Market study—designed specifically to inform boardroom decisions in 2026. This briefing synthesizes macro trajectories, competitive dynamics, regulatory and reimbursement inflection points, and a pragmatic playbook that senior leaders can deploy immediately. The intent here is to demonstrate the analytical depth underpinning our full offering while preserving the granular, proprietary numbers and segment breakouts that reside in the complete report.
Procalcitonin (CAS 56645-65-9) Market
Why PCT matters to 2026 strategy
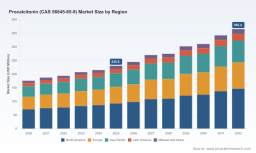
Procalcitonin has evolved from a specialist research analyte to a clinically actionable biomarker shaping sepsis care pathways and antibiotic stewardship programs. Between 2020 and the report base year of 2025, the global market for Procalcitonin diagnostics expanded materially—driven by increasing guideline acceptance, hospital program adoption, and improved assay availability across platforms. Our modeled trajectory through the forecast period (2026–2032) assumes a compound annual growth rate (CAGR) of approximately 6.98%, reflecting both near‑term reimbursement tailwinds and medium‑term diffusion across care settings.
Procalcitonin (CAS 56645-65-9) Market
To anchor perspective: PW Consulting’s topline market model shows a market increasing from a mid‑hundreds million USD base in 2025 to a substantially larger addressable pool by 2032. This scale and growth profile creates distinct strategic choices for incumbents, instrument makers, reagent suppliers, and later‑stage investors—choices that demand different allocation of R&D, commercial effort, and M&A capital in 2026.
Procalcitonin (CAS 56645-65-9) Market
What corporate leaders should see as the immediate operating environment
-
Clinical and payer momentum: In 2025–2026 we observe expanded payer coverage—public and private—that explicitly supports PCT‑guided antibiotic decisions for sepsis and lower respiratory tract infections. This reimbursement expansion materially improves utilization economics and accelerates adoption where hospital stewardship programs can operationalize test‑based protocols.
-
Regulatory validation: New clearances are lowering barriers to clinical uptake. A notable development in May 2025 was a 510(k) clearance for a PCT assay and related controls—an outcome the market interprets as regulatory endorsement of PCT platforms as substantially equivalent to legacy systems. This creates a more permissive environment for new entrants and second‑generation assays seeking hospital and reference laboratory customers.
-
Platform and supply‑chain dynamics: The PCT ecosystem spans global in vitro diagnostics (IVD) instrument leaders, specialized assay originators, and a small but strategic set of suppliers for recombinant antigens and monoclonal antibodies. Control of calibrators, reference reagents, and validated antibodies is a non‑trivial source of competitive advantage, particularly for vendors seeking rapid assay development or for buyers aiming to reduce procurement risk.
-
Market structure: Market concentration levels indicate a fragmented landscape—top competitors do not dominate the space to an extent that would dissuade bold market entry or roll‑up strategies. The current concentration metrics show room for specialist firms to win share by focusing on niche clinical claims, pricing, or channel excellence.
Competitive landscape — who matters and why
PCT is currently supported by a small set of well‑known diagnostics firms and specialized reagent suppliers. These organizations occupy complementary strategic positions that together define the competitive chessboard for 2026:
-
Major platform incumbents (Roche Diagnostics, bioMérieux, Thermo Fisher Scientific, Siemens Healthineers): These firms offer integrated assays and analyzer solutions that are deeply embedded in hospital and reference labs. Their strengths are distribution reach, installed base economics, and the ability to bundle PCT testing with other routine lab workflows—making them natural favorites for enterprise procurement committees focused on operational efficiency.
-
Specialist reagent and assay developers (DiaSys Diagnostic Systems, HyTest, BBI Solutions): Specialist firms provide focused assay kits, calibrators, and critical raw materials (recombinant PCT antigen, monoclonal antibodies). Regulatory milestones from such players (for example, recent FDA 510(k) clearance events) are proof points that niche developers can convert technical capabilities into commercial access and can quickly influence local adoption when supported by effective clinical evidence.
-
Strategic implications: Market participants should treat platform players and reagent specialists as both partners and competitors. Partnerships or OEM supply agreements can accelerate market entry for smaller firms, while incumbents must guard against supply substitution and price erosion by vertically integrating or by signing exclusive reagent contracts.
Regulatory and reimbursement — windows of opportunity in 2026
-
Expanded coverage for PCT testing by public payers and commercial insurers in 2025 materially changes the near‑term ROI for hospital purchasers. For commercially driven product launches in 2026, aligning the evidence generation plan with payer expectations—especially around antibiotic‑stewardship outcomes and cost‑avoidance metrics—should be a top priority.
-
Regulatory precedent from recent 510(k) clearances reduces uncertainty for product teams following established platform claims. That said, companies targeting new indications (for example, point‑of‑care use outside intensive care settings) will still need tailored regulatory strategies and pragmatic clinical validation to secure formulary placements.
Key risks and cross‑cutting uncertainties
-
Clinical guideline variability: Adoption of PCT‑guided protocols is uneven across systems and influenced by local antimicrobial stewardship leadership. Shifts in guideline language or the publication of counter‑evidence could meaningfully affect uptake curves.
-
Technological substitution: Advances in multiplex molecular panels or novel host‑response biomarkers could compete with single‑marker PCT strategies in certain use cases. Firms must monitor adjacent diagnostic innovations and consider platform flexibility.
-
Procurement dynamics: Hospital formulary decisions and group purchasing organization contracts remain decisive for adoption. Successful suppliers will need playbooks for contracting, clinical affairs engagement, and on‑site implementation support.
What our report contains — operational, actionable deliverables
The full PW Consulting Procalcitonin Market report is constructed as a decision‑grade tool for 2026. Highlights of the practical content included are:
- Topline market sizing and validated growth forecasts from 2020 through 2032, with scenario analysis that isolates near‑term reimbursement impacts and longer‑term diffusion curves.
- Competitive intelligence dossiers for leading and emerging firms, including commercial models, product portfolios, advantage maps, and go‑to‑market strengths and weaknesses.
- Regulatory and payer playbooks: templated evidence packages, recommended clinical endpoints for label expansion, and reimbursement submission frameworks tailored to national markets.
- Channel and pricing strategies: unit economics models, contract negotiation levers for selling into hospital systems and reference labs, and pricing sensitivity analyses to support margin optimization.
- Supply‑chain risk assessment and mitigation tactics: supplier scorecards for raw materials (recombinant antigen, monoclonals), qualification checklists, and inventory strategies to support clinical continuity.
- Transaction and partnership guidance: M&A screening criteria, partnership archetypes, and valuation sensitivities built from multiples observed in recent diagnostics deals and relative margin performance.
Each module contains exhibits, supporting data tables, and a set of executable recommendations. To preserve the commercial value of those granular exhibits (segment breakouts, regional revenue splits, and unit‑price schedules), they are accessible exclusively through the full report package.
Strategic playbook for 2026 — five prioritized moves
-
Lock the clinical story: Fund or partner on targeted outcome studies that demonstrate antibiotic‑sparing benefits and reductions in length of stay. Payer coverage in many markets now ties directly to such outcomes; evidence gaps materially slow procurement decisions.
-
Defend and diversify supply chains: Secure multi‑sourced supplies for recombinant antigen and antibodies or invest in backward integration. A targeted contingency strategy for critical reagents will protect growth and reduce procurement leverage from competitors.
-
Negotiate formulary access early: Build compelling total cost of ownership (TCO) cases for hospital executives and procurement consortia. Bundle PCT offerings with implementation services, stewardship program support, and dashboards that demonstrate measurable impact.
-
Consider platform vs niche positioning: Decide whether to pursue broader platform integration with major analyzer OEMs or to dominate a niche (e.g., point‑of‑care, rapid triage). Both approaches can win in 2026 — but each requires different investment, pricing, and partnership playbooks.
-
Use M&A and partnerships as force multipliers: With current market concentration moderate, well‑timed acquisitions of reagent specialists or clinical services firms can accelerate share gains and close technology gaps faster than organic development.
Final observation — why 2026 is pivotal
2026 represents a decision nexus: reimbursement and regulatory shifts enacted in 2025 have improved the commercial environment, while the market’s medium‑term growth (a near 7% CAGR over the forecast interval) supports expansion investments. For corporate leaders, the choice is whether to invest to capture the inflection—by bolstering evidence, securing supply and channel access, and using partnerships to close capability gaps—or to adopt a defensive posture as competitors consolidate position.
PW Consulting’s Procalcitonin Market study equips leaders to make that choice with confidence. The analysis delivers not only the macro forecasts and competitive context outlined here, but also the masked, transaction‑grade exhibits that translate strategy into actionable budgets, timelines, and KPI targets. For access to the full dataset, segmented models, and our recommended implementation templates, please consult the complete report.
For detailed analysis of this topic, please visit the official page: Procalcitonin (CAS 56645-65-9) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com