

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Micronized PTFE Market to Reach USD 1,960.38M by 2032

Micronized PTFE Market: Strategic Imperatives for 2026 Decision‑Makers
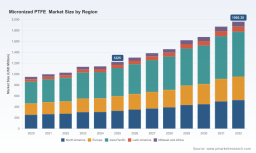
As PW Consulting’s senior strategy lead and chief industry analyst, I present a synthesis of the Micronized PTFE market study designed to shape corporate decisions in 2026. Built on a base year of 2025 with a historical window that covers 2020–2025 and a forward-looking forecast to 2032, the study projects continued expansion at a compound annual growth rate (CAGR) of 6.92%. The market has expanded from roughly USD 950 million in 2020 to about USD 1.225 billion in 2025, and our scenarios point toward nearly USD 2.0 billion by 2032 under baseline assumptions. This briefing highlights the strategic takeaways, competitive dynamics, and near‑term actions executives should consider — while reserving the full granular segmentation and proprietary model outputs for the full report.
Micronized PTFE Market
Why this study matters now
-
Timing and magnitude: 2026 is shaping up to be a pivot year. Demand growth is steady and predictable at the headline CAGR, but supply‑side shocks, regulatory tightening, and shifts in end‑use formulations are creating asymmetric risks for both suppliers and converters. Companies that align procurement, R&D, and commercial strategies now will capture outsized share and margin improvement through the next planning cycle.
Micronized PTFE Market -
Strategic visibility: Our analysis translates aggregate market momentum into decision‑grade outputs — supply risk maps, price sensitivity matrices, and product/market prioritization frameworks — enabling executive teams to make informed tradeoffs between securing capacity, investing in product innovation, and defending margin under input‑cost stress.
Micronized PTFE Market -
Operational cadence: For procurement, manufacturing and product teams the report frames six actionable workstreams (sourcing diversification, price hedging, product reformulation, capacity choreography, sustainability certification, and M&A/partnership screening) that should be instituted as part of the 2026 operating plan.
Macro and market dynamics shaping 2026
-
Supply tightness and pricing volatility: Regulatory shifts and export licensing in key fluorite supply geographies have tightened upstream availability. Industry data show a material contraction in export volumes from principal suppliers, which has pushed global spot pricing upward and raised costs for hydrofluoric acid and other fluorochemical feedstocks. These upstream moves translate into higher landed costs and shorter contract lead‑times in Europe and North America.
-
Regulatory and environmental pressure: Tighter environmental controls on fluoropolymer production — including PFAS scrutiny and emissions monitoring — are increasing compliance burdens and capital expenditure requirements for manufacturers. Expect ongoing increases in testing, monitoring and reporting costs that will be reflected in supplier pricing and qualifying processes.
-
Raw material volatility: Tetrafluoroethylene (TFE) pricing and feedstock availability have become more volatile, complicating long‑term contract negotiations. Our scenario work shows that an 8% swing in TFE prices can materially affect small compounders’ margin profiles and accelerate consolidation if sustained.
-
Demand resilience with structural changes: End‑use demand remains resilient across coatings, lubricants, polymer modification, inks and specialty industrial applications, but the mix is shifting toward low‑VOC systems, water‑based formulations and recycled‑content products — a movement that creates both growth opportunities and qualification hurdles for micronized PTFE grades.
Market trajectory and structural implications
At the headline level, the market’s progression from the low‑hundreds of millions in 2020 to the mid‑billions by 2032 reflects steady volumetric growth and gradual value uplift as higher‑performance grades and sustainability credentials command pricing premiums. Market concentration metrics indicate a moderately fragmented industry: the top three companies account for roughly one‑third of global revenue and the top five do not exceed 40% share, underscoring a competitive environment where regional players, specialty compounders and global fluoropolymer producers all retain strategic relevance.
Implication for strategy: buyers enjoy choice but face heterogenous supplier risk. Large converters should use that fragmentation to extract service and security commitments; smaller players may need to pursue vertical integration, strategic alliances, or long‑term supply contracts to stabilize margins.
Competitive landscape — what to watch
-
Chemours Company (Zonyl®): A global specialty supplier with a strong presence in coatings, lubricants and polymer modification. Recent strategic moves include securing additional regional production capacity through alliance structures to reduce delivery lead‑times into high‑growth markets.
-
Daikin Industries: A technology‑driven producer with engineered grades targeted at high‑performance plastics and industrial additives. Their product leadership and global footprint make them a key supplier for formulators demanding precise performance attributes.
-
3M Company (Dyneon™): Continued product innovation, including surface‑modified micronized PTFE grades for low‑VOC and water‑based coatings, positions them well for formulators transitioning away from solvent systems.
-
AGC Inc.: Expanding fluorochemical capacity and gaining early third‑party recycled‑content certifications creates a differentiated sustainability narrative that will influence corporate procurement policies and brand‑driven specification trends.
-
Specialist and regional producers: European and Chinese producers provide local cost and service advantages, especially for regional formulators. Smaller compounders, however, face margin compression under feedstock scarcity and regulatory cost pressure, increasing M&A potential.
Recent corporate activities — capacity alliances in India, capacity expansions in Japan, recycled‑content certification rollouts, and launches of application‑specific low‑VOC grades — collectively point to three dynamics: diversified geographic capacity buildout, premiumization via application engineering, and sustainability as a competitive axis. These moves, taken together, will materially influence commercial negotiations and qualification calendars in 2026.
What the PW Consulting report delivers (practical contents)
-
Proprietary market model: a transparent, auditable Excel model spanning 2020–2032 that supports scenario testing (base, supply‑shock, accelerated‑demand). The model includes price curves, cost drivers, and sensitivity levers.
-
Supply‑risk taxonomy and map: supplier scorecards, capacity overlays, and logistics risk indices to prioritize contracted capacity and identify safe‑source partners.
-
Commercial playbooks: negotiation templates for long‑term offtake, hybrid pricing mechanisms, and contract clauses addressing force majeure, allocation, and ESG commitments.
-
Product and formulation roadmaps: gap analyses for coating, lubricant and polymer applications with recommendations on specification migration, qualification timelines, and co‑development priorities.
-
M&A and partnership screening: target lists and valuation priors for bolt‑on acquisitions and strategic alliances that strengthen feedstock security, technical capability, or regional presence.
-
Regulatory risk dashboard: jurisdictional compliance trackers, cost impact simulations for emission controls and PFAS rules, and recommended mitigation actions for 12–36 month horizons.
Note: the summary above is intentionally high level. The full report contains the detailed subsegment datasets, regional and application splits, supplier revenue estimates, and the raw model files necessary for direct import into corporate planning systems.
High‑impact recommendations for 2026
-
Secure supply through diversification and contracts: Move from spot exposure to a blended strategy that includes multi‑year contracts, strategic buffer inventories, and regional secondary suppliers to mitigate upstream export licensing risk.
-
Prioritize product innovation for low‑VOC and recycled content: Build or partner for grades formulated for water‑based and recycled‑content specifications now, to compress qualification timelines and capture premium pricing as demand mix shifts.
-
Implement raw material governance and hedging: Tighten procurement governance around TFE and fluorspar exposure, adopt trigger‑based hedges, and perform quarterly stress‑tests to update cost pass‑through clauses with customers.
-
Accelerate sustainability certification: Use third‑party recycled‑content and lifecycle verification to differentiate supply and shorten approval cycles with sustainability‑driven OEMs and brands.
-
Evaluate near‑market capacity plays: Consider minority investments or JVs in growth regions to secure domestic supply, shorten lead times and avoid the most acute landed‑cost inflation.
Final note — how PW Consulting supports execution
Our Micronized PTFE Market study is structured to convert market intelligence into executable plans. For 2026, this means translating a 6.92% CAGR baseline and the observable supply shocks into concrete procurement, R&D, and commercial actions that protect margin and position businesses for selective top‑line capture. The study’s datasets, supplier scorecards, and scenario models are designed for direct integration into corporate planning tools — but those proprietary elements are available only in the full report and model package.
For teams preparing 2026 operating plans: begin by mapping your exposure across the six workstreams highlighted, run the supplied scenario models against your demand plan, and initiate selective supplier conversations informed by our risk maps. PW Consulting can support those activities with targeted workshops, model integration, and deal support.
To access the full dataset, supplier scorecards and executable playbooks, please consult the full Micronized PTFE Market report.
For detailed analysis of this topic, please visit the official page: Micronized PTFE Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com