

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: QLED Market to Hit USD 5.44B by 2032 at 8.8% CAGR

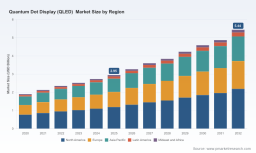
Quantum Dot Display (QLED) Market: Strategic Outlook for 2026 — PW Consulting Preview
Quantum dot displays have moved from a niche image-quality differentiator to a mainstream strategic vector for display OEMs, material suppliers, and systems integrators. This PW Consulting preview distills why the QLED market will matter to boardroom agendas in 2026 and how senior commercial, product and M&A leaders should reframe decisions in light of an accelerating technology and supply-chain reconfiguration.
Quantum Dot Display (QLED) Market
Market trajectory at a glance
After an inflection period between 2020 and 2025 — when the market expanded from roughly USD 1.9 billion to USD 2.95 billion — PW Consulting projects the QLED market to enter a sustained growth phase through our forecast window (2026–2032). Our modeled baseline shows a compound annual growth rate of 8.8% into the forecast period, with total market value rising toward the mid-single-digit billions by the early 2030s. This momentum reflects broader adoption across premium consumer electronics, the emergence of new form factors, and the industrialization of quantum dot material supply chains.
Quantum Dot Display (QLED) Market
Why this matters for 2026 decision-making
- Portfolio prioritization: Product leaders must decide which display platforms to accelerate. QLED technologies are no longer solely a premium TV play — they are influencing monitor, mobile, and automotive display strategies. The pace of adoption over the next 18 months will determine whether QLED remains a differentiator or becomes table stakes in multiple product tiers.
- Supply-chain locking and capacity planning: Vertical and horizontal integration moves by material foundries and panel makers are reshaping bargaining leverage. With a few players controlling a significant share of production and materials, early capacity commitments (or failure to secure them) will materially affect cost, lead times, and innovation cadence.
- M&A and partnership timing: Given a concentrated supplier landscape, strategic acquisitions, minority-stake investments, or long-term supply agreements executed in 2026 will yield asymmetric returns. Our scenario work shows that well-timed consolidation or exclusive supply contracts can accelerate time-to-market while protecting margin.
- Regulatory and product-compliance planning: Materials and environmental compliance (notably the cadmium debate and cadmium-free alternatives) are central to go-to-market strategies. Certification and licensing decisions taken now will influence global distribution and brand positioning.
What PW Consulting’s full report delivers — practical, decision-focused content
This study is designed as a playbook for executives making near- to medium-term strategic choices. Highlights of the full report include (summarized at a high level to preserve strategic value):
Quantum Dot Display (QLED) Market
- Proprietary market sizing and a year-by-year historical series (2020–2025) with a transparent forecasting framework for 2026–2032, enabling sensitivity testing against price, adoption, and component-cost scenarios.
- Segment-level modelling by technology type, application, and region — with both baseline and upside cases — and a methodology appendix so clients can adapt scenarios to internal assumptions.
- Competitive intelligence dossiers on leading foundries, material innovators, and panel manufacturers, including capacities, strategic positioning, and capability maps.
- Actionable GTM playbooks for OEMs and material suppliers: pricing levers, channel strategies, and product roadmaps tailored to short-cycle consumer markets and longer-cycle automotive opportunities.
- M&A playbooks and value-capture models showing where consolidation, licensing, or joint manufacturing agreements create the most defensible value pools.
- Supply-chain risk matrix and mitigation blueprints addressing raw-material concentration, trade policy exposure, and manufacturing consolidation.
We deliberately avoid reproducing sensitive sub-segment numbers in this preview; the full report provides granular splits, share tables, and downloadable data files for client use.
Competitive landscape — who matters and why
The QLED ecosystem now features a mix of material foundries, component specialists, and panel integrators. Market concentration is meaningful: three firms account for a substantial portion of market revenue (CR3 ~65%), while the top five increase concentration further (CR5 ~72%). This structure creates both barriers and opportunities — incumbents can defend pricing and scale, but nimble specialists can capture high-margin adjacency with the right IP or partnerships.
- Nanosys, Inc. (Milpitas, CA) — A leading foundry and quantum dot material supplier that combines product R&D with wide-scale manufacturing partnerships. Nanosys’ foundry model and integration partnerships (including QD-OLED workstreams) make it a logical counterparty for OEMs seeking rapid deployment without internalizing material manufacturing.
- Shoei Chemical, Inc. (Tokyo) — As a vertically integrated advanced materials player, Shoei’s scale and its role in the production ramp of quantum dots give it strategic leverage. Its large-scale factory investments are shifting the supply curve for quantum dot films and materials.
- Samsung Electronics & Samsung Display (Seoul) — Samsung’s twin role as a consumer OEM and panel manufacturer makes it a pivotal adopter of quantum dot innovations. Certification initiatives and product launches are signaling downstream expectations for color performance and cadmium compliance.
- LG Display & Sony — Both players are advancing QD-OLED and QLED variants in premium home-entertainment portfolios; Sony’s integration of QD-OLED in Bravia and LG Display’s product introductions sharpen the competition at the high end.
- China-based panel makers (e.g., BOE, TCL) — These firms offer volume pathways and cost pressure; their adoption timelines and export strategies will determine how quickly premium quantum dot performance becomes accessible in volume markets.
- Nanoco Group (London) — A key player for cadmium-free quantum dots, Nanoco’s licensing and collaboration actions are relevant for firms seeking compliant material routes that mitigate regulatory risk.
Technology, materials and supply-chain dynamics
Three structural factors will determine winners and losers into 2026:
- Material performance vs. regulatory fit: Cadmium-containing quantum dots remain attractive for optical performance, but regulatory and brand-compliance pressures favour cadmium-free solutions. Licensing, certification, and partnerships (already in motion across the industry) will determine which materials scale commercially.
- Manufacturing scale and foundry economics: Large-scale production capacity — for example, foundry output measured in tens of millions of square meters annually — shifts unit costs and enables verticals such as automotive and professional displays to adopt QLED at scale. Early capacity investments translate directly into commercial leverage.
- Trade policy and raw material risk: Supply chains for rare earths and specialty components remain exposed to export controls and geopolitical friction. Restricted access to certain inputs can lengthen lead times and force supply reengineering, affecting both cost and time-to-market.
Recent industry signals illustrate these dynamics: prototype demonstrations highlighting improved color primitives, product launches embedding quantum dot sheets into mass-market TVs, and public certification moves all point to a commercialization phase where product differentiation is tightly coupled with supplier selection and compliance strategy.
Strategic actions for 2026 — a short playbook
- Secure optionality in supply: Negotiate multi-source supply agreements with staged volume commitments. Prioritize suppliers with validated scale and compliance credentials.
- Protect product roadmaps: Prioritize R&D investments that translate quantum-dot optical advantages into perceptible end-user benefits (brightness, color volume, power efficiency) rather than incremental spec battles.
- Use licensing and partnerships as force multipliers: Consider non-equity partnerships with material specialists to accelerate market entry while keeping capital intensity manageable.
- Embed regulatory & sustainability as commercial KPIs: Certification and cadmium-free positioning can drive premium placement and reduce go-to-market friction in regulated markets.
- Model M&A outcomes against concentration metrics: With the top three-to-five firms controlling a high share of market value, acquisitions or minority stakes can be an efficient route to secure technology or capacity — but valuation discipline is critical.
How PW Consulting recommends using this research in 2026
Use the full report as a decision engine: feed its scenario outputs into product-portfolio P&L models, link its supplier risk matrices to procurement playbooks, and use the company dossiers to prioritize partnership or M&A targets. For leadership teams, the report provides both the quantitative backbone and the qualitative narrative necessary to present coherent, defensible investment cases to boards or funding committees.
Final note — the value of the full analysis
This preview highlights trends and decision levers that will shape QLED strategies in 2026. For executives needing executable detail — regional and application-level forecasts, supplier scorecards, price-path assumptions, and downloadable model files — PW Consulting’s full report contains the granular data and strategic tools required to operationalize these insights. Access to the complete dataset and model allows you to stress-test scenarios against internal plans and to blueprint concrete agreements and roadmaps for the coming year.
Contact PW Consulting to obtain the full Quantum Dot Display (QLED) Market report and the accompanying data pack for scenario customization and boardroom-ready strategy materials.
For detailed analysis of this topic, please visit the official page: Quantum Dot Display (QLED) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com