

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Off‑Road Fuel Tank Market to Expand at 5.48% CAGR, Reaching USD 3,191.34 Million by 2032
By pmarketresearch, 2026-07-13
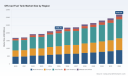
Off Road Fuel Tank Market 2026: Strategic Imperatives from PW Consulting’s Latest Industry Brief
As off-highway equipment manufacturers, component suppliers, and investors set strategy for 2026, the off road fuel tank market is entering a phase where tactical choices will determine multi-year outcomes. PW Consulting’s new market brief—built on a 2020–2025 historical baseline and a 2026–2032 forecast—shows a market expanding from a 2025 base of USD 2,196.75 Million and growing at a 5.48% CAGR through the forecast window. By 2032 the market is sized to cross the USD 3.1 billion threshold under our central scenario. These headline metrics are more than a vanity number: they quantify the commercial runway and the scale of investment required to win.
Off Road Fuel Tank Market
Executive snapshot — why this matters for 2026 decision cycles
-
Market momentum: Modest but stable CAGR and a clear upward path create a predictable backdrop for capex and capacity planning across materials, molding, and metal fabrication segments.
Off Road Fuel Tank Market -
Margin pressure vectors: Raw material volatility and tightening emissions rules are converging to reshape cost structures and product specification requirements.
Off Road Fuel Tank Market -
Competitive balance: Concentration metrics indicate a market where scale provides advantage but where niche specialists and aftermarket players can still capture meaningful share through technology and service differentiation.
Data-driven dynamics shaping supplier and OEM strategy
Three structural drivers will dominate boardroom conversations in 2026:
-
Input-cost inflation and pass-through complexity. Recent market signals show aluminum mill shapes up ~39% and steel mill products ~21% year-on-year in an interval through early 2026. Concurrently, HDPE pricing has traded at elevated levels (about USD 1,227/MT in Q2 2025). These movements materially affect metal- and plastic-based tank economics and force suppliers to refine cost-plus frameworks, hedging approaches, and long-term supplier contracts.
-
Regulatory tightening on emissions and heavy-duty greenhouse gases. Ongoing EPA and CARB enforcement on evaporative emissions for small off-road equipment, plus heavy-duty GHG standards that touch off-road operations, are accelerating adoption of multilayer plastic designs and low-permeation solutions. Compliance is not optional; it is a market entry and feature requirement in key buying centers.
-
Aftermarket and specialized-volume growth. Operators in mining, construction, agriculture, and long-range exploration are demanding higher-capacity, more rugged, or auxiliary fuel solutions—creating durable demand pockets that reward product innovation and fast service response.
Strategic implications for 2026 planning
-
Portfolio and materials posture. Procurement and R&D teams must view metal and polymer routes as complementary strategies, not binaries. Elevated metal prices argue for engineering investments in polymer alternatives where regulatory compliance and performance allow; conversely, where structural robustness or extreme-capacity needs persist, metal fabrication investments remain essential. The right mix will be defined at the product-family level.
-
Supply-chain risk management. The degree of raw-material price movement observed argues for layered mitigation: multi-source qualification, indexed supplier contracts, and selective vertical integration. Firms should run scenario-based pass-through models tied to both aluminum/steel and HDPE indices to quantify margin exposure under up and down cycles.
-
Regulatory-driven product roadmaps. Teams must accelerate low-permeation multi-layer designs and create compliance-forward product families. Early certification and homologation are competitive advantages—especially for OEMs supplying into CARB and EPA-sensitive markets.
-
Aftermarket as a margin lever. Auxiliary and replacement tanks represent a resilient, often higher-margin channel. Investments in fast-turn manufacturing, modular mounting systems, and field-service solutions can defend OEM relationships and open direct-to-operator revenue streams.
-
M&A and partnership playbook. With the market showing a moderate level of concentration (top‑3 firms capture roughly a third of volume, top‑5 approaches half), strategic M&A—targeting technology-enabled blow molders, high-capacity fabricators, or aftermarket specialists—remains a pragmatic route to accelerate scale and capability.
Competitive landscape — profiles and practical takeaways
The market is populated by diversified metal fabricators, high-volume thermoplastic blow molders, aftermarket specialists, and bespoke racing/utility cell makers. Our review of leading players yields five observable strategic archetypes and recommended 2026 actions:
-
Large custom metal fabricators (e.g., IFH Group, Standard Technologies). Strengths: scale in heavy-gauge steel and aluminum, deep OEM relationships, and capacity for custom reservoirs. Action: capture premium margin by offering integrated fuel system modules and long-term supply agreements indexed for material-cost movement.
-
High-volume polymer specialists (e.g., Agri-Industrial Plastics, Elkamet). Strengths: multi-layer HDPE expertise, regulatory-compliant low-permeation designs, and cost-efficient volume production. Action: invest in new resin blends and co-extrusion capabilities to extend performance envelopes while locking raw material exposure via strategic resin supply agreements.
-
Aftermarket and auxiliary system providers (e.g., Transfer Flow, TITAN Fuel Tanks). Strengths: brand recognition among end-users, rapid time-to-market for niche needs, and aftermarket distribution networks. Action: scale digital channels and service offerings (installation, warranty extensions) to convert one-time buyers into recurring customers.
-
Heavy-capacity integrators (e.g., Niece Equipment). Strengths: capability to deliver very large-volume tanks and mobile refueling systems for mining and heavy construction. Action: target long-cycle service contracts and remote fueling solutions as operators consolidate fleet management.
-
Specialty and motorsport suppliers (e.g., Harmon Racing Cells, Extreme Tanks). Strengths: high-performance safety cells, rapid customization, and niche engineering skill. Action: leverage motorsport pedigree to spin performance-derived features into mainstream off-road safety and durability claims.
What PW Consulting’s full report delivers (practical, operational intelligence)
Our brief is a “decision support system” designed for commercial, procurement, and M&A teams. It contains:
-
A transparent market-sizing framework and demand-modeling workbook that ties fleet populations, utilization assumptions, and replacement cycles to revenue forecasts—enabling users to run bespoke scenarios for 2026 planning.
-
A modular cost-benchmarking package that isolates raw material, labor, and overhead drivers and maps them to typical bill-of-materials across metal and polymer architectures—built for sourcing negotiations and margin-protection strategies.
-
Regulatory-impact assessments with compliance roadmaps, required test protocols, and an implementation timeline to guide product homologation in regulated markets.
-
Supplier and capability heat maps, including qualifiers for low-perm plastic systems, heavy-duty fabricated reservoirs, aftermarket fitment networks, and rapid-response electromechanical subassemblies.
-
Commercial playbooks: go-to-market templates for premium OEM programs, distributor partnerships, and direct-service aftermarket channels—complete with sample contractual language and KPIs.
-
M&A target screening criteria and valuation sensitivities tied to concentration dynamics, margin leverage, and technology gaps—helpful for private equity and strategic buyers alike.
How leading teams should use these insights in 2026
-
Finance teams: adopt stress-tested scenarios that link input-cost volatility to EBITDA sensitivity; use these to set covenant buffers and capex phasing.
-
Procurement teams: convert cost models into multi-year supplier agreements with indexed clauses and volume flex provisions to protect margins.
-
Product and engineering: prioritize low-permeation, multi-layer plastic solutions for regulated footprints while executing lightweighting and corrosion-resistance projects for metal tanks.
-
M&A and corporate development: focus on bolt-on targets that fill capability gaps (e.g., aftermarket networks, blow-molding scale, or high-capacity fabrication).
-
Commercial teams: test premium aftermarket subscription and service bundles in high-utilization verticals such as mining and construction to monetize uptime and refueling services.
Closing — a trailer, not a reveal
PW Consulting’s market brief marries macro sizing—anchored to a 2025 base of USD 2,196.75 Million and a 5.48% CAGR outlook—with hands-on tools for 2026 operationalization. In keeping with a “trailer” approach, this note highlights the strategic contours and actionable levers without publishing the granular regional and application splits that are often the decisive inputs in contract negotiations and M&A valuation. For teams that need the full set of segment-level breakouts, supplier scorecards, and downloadable scenario models to execute 2026 plans, the complete report and accompanying analyst support are available via our research portal.
Contact PW Consulting to access the full report, download the forecasting workbook, or arrange a custom workshop to translate the findings into a 90-day action plan for your organization.
For detailed analysis of this topic, please visit the official page: Off Road Fuel Tank Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Stabilizer Bars Market to Reach USD 8,677.8 Million by 2032, Expanding at a 4.8% CAGR (Base Year 2025)
By pmarketresearch, 2026-07-13
PW Consulting Releases Strategic Intelligence: Stabilizer Bars Market Outlook to 2032
PW Consulting today publishes a focused market intelligence brief that positions executive teams to make high-confidence decisions on stabilizer bar strategies in 2026 and beyond. Built on a 2025 base year, the report models a stabilizer bars market that we valued at approximately USD 6,250 Million in 2025 and projects expansion through 2032, reaching roughly USD 8,678 Million under a central scenario. The forecast period (2026–2032) carries a compound annual growth rate (CAGR) of approximately 4.8%, reflecting steady demand backed by vehicle production dynamics, lightweighting trends, and regulatory drivers.
Stabilizer Bars Market
Why this brief matters to 2026 decision-makers
- Bridge from tactical to strategic: equips procurement, product, and M&A teams with a unified, decision-grade view of demand, cost and competitive trajectories as OEM programs reset in 2026.
- Operationalize uncertainty: provides stress-tested scenarios that translate macro shocks (steel price volatility, tariffs, vehicle production swings) into purchasing, capacity and pricing playbooks.
- Actionable differentiation: highlights which technology choices and value propositions—lightweight hollow designs, active stabilizer systems, integrated modules—are likely to capture premium margins across OEM and aftermarket channels.
Macro forces and industry dynamics shaping outcomes
The stabilizer bars market is not insulated from broader automotive and materials trends. Three macro factors stand out for executives planning in 2026:
Stabilizer Bars Market
- Vehicle production momentum. Global passenger car output—on the order of tens of millions of units annually—remains the single largest demand driver for stabilizer bars. OEM production forecasts and platform timing dictate near-term order books for suppliers and should be central to production-scheduling decisions.
- Materials and cost pressure. Steel remains the primary input for most stabilizer designs. Recent European hot-rolled coil price levels and continuing tariff regimes (notably steel-related import measures) have elevated the cost base and emphasized the value of supply-pipeline risk mitigation, hedging and localization. Teams should treat raw-material exposure as a first-order profit risk when budgeting for 2026 programs.
- Design and regulation as enablers. Lightweighting and the transition to electric vehicles accelerate interest in hollow and tubular stabilizer solutions—technical pathways that can reduce assembly mass materially versus traditional solid bars. Simultaneously, safety standards and crash-integrity mandates continue to influence design specifications; OEMs and suppliers that align product roadmaps with evolving regulatory tests will avoid costly redesigns.
Competitive landscape — what leaders are doing and why it matters
The market is characterized by a mix of global OEM-tier suppliers and specialized component manufacturers. Concentration is meaningful: the top players control a material share of industry shipments, while a deeper long tail of regional specialists competes on cost, speed and niche application expertise.
Stabilizer Bars Market
- ZF Friedrichshafen AG — A benchmark for systems thinking. ZF’s work on active stabilizer systems demonstrates an ambition to move beyond passive components into mechatronic vehicle-level value capture. For OEMs prioritizing dynamic handling and improved ride comfort—especially in higher-end segments—active systems are a value pool worth monitoring.
- Magna International Inc. — Integration and scale. Magna’s capability to offer full stabilizer systems as part of broader body and chassis modules makes it a default partner for OEMs seeking supplier consolidation and interface simplification across the vehicle program cycle.
- Tenneco Inc. — Ride control and modularity. Tenneco’s positioning in ride-control subsystems highlights the commercial imperative of modular, easily integrated stabilizer solutions that reduce assembly complexity for manufacturers.
- Benteler, thyssenkrupp Steel and Mubea — Materials and lightweighting leaders. Benteler’s hollow stabilizer focus for EVs, thyssenkrupp’s high-strength and hollow-steel offerings, and Mubea’s advanced tube-forming technologies illustrate the industry’s shift toward materials engineering as a route to product differentiation and CO2 reduction.
- Regional specialists (Hyundai WIA, NHK Spring, Chuo Spring, Dura) — Execution and proximity. These firms reinforce how proximity to OEMs, specialty engineering, and component-level expertise remain competitive levers. For many OEM platforms, supplier selection favors responsiveness over marginal cost advantages.
Recent vendor moves provide additional directional signals: ZF’s public demonstrations of active stabilizer technology at major trade forums, Benteler’s hollow-bar product introductions for EV platforms, and Mubea’s capacity investments in North America are all consistent with an industry pivot towards lightweight, locally-sourced solutions. These developments matter for 2026 procurement cycles because they impact lead times, qualification windows and sourcing flexibility.
What the PW Consulting report delivers — the practitioner’s toolkit
This brief is structured for immediate application by strategy, procurement and product teams. While the full dataset and detailed segment tables are reserved for subscribers, the report includes:
- Integrated demand model (2020–2032) that maps vehicle production scenarios to stabilizer-bar volume and revenue impacts under alternative adoption curves for lightweighting and active systems.
- Cost-sensitivity engine that quantifies P&L exposure to steel-price swings, logistics costs and tariff regimes—presented as scenario outputs to support hedging and fixed-price contract decisions.
- Supplier risk heatmap and capacity overlay that synthesizes geography, lead-times, and technology capability—enabling rapid go/no-go decisions for nearshoring or optional second-source qualification in 2026.
- Competitive scorecards and technology-readiness evaluations for leading vendors, cross-referenced against program timelines and OEM procurement windows.
- Practical playbooks: procurement negotiation levers, modular product design templates, prototype-to-production timelines, and an M&A checklist for tuck-in opportunities that fill capability gaps.
Strategic recommendations for 2026 (executive checklist)
- Embed material-price scenario planning into 2026 budgets. Use the report’s cost-sensitivity outputs to set guardrails for margins, and negotiate index-linked contracts or take selective forward-buy positions where feasible.
- Prioritize lightweight and tubular technologies for EV platforms. Even where direct cost parity is not yet achieved, the combination of mass reduction and system-level benefits de-risks future platform engineering changes.
- Localize critical capacity strategically. Tariff regimes and logistics disruptions make a compelling case for regional capacity either through partnership or brownfield expansion—particularly for suppliers serving time-sensitive OEM programs.
- Explore modular, integrated stabilizer assemblies to increase supplier value capture. Suppliers that move up the stack to offer modules—combining bar, links, bushings and electro-mechanical actuation—can secure longer-term program footprints.
- Use M&A selectively to buy technological breadth and shorten the qualification curve. Market concentration presents opportunities for scale-driven consolidation where synergy cases are clear.
How boards and executive teams should use this brief
For boards preparing 2026 capital allocation decisions, the report serves as a bridge between market-level forecasts and program-level execution. It will help executive teams answer questions such as:
- Where should we allocate incremental CapEx to support OEM wins in 2026–2027?
- Which supplier relationships should be transformed into strategic partnerships and which should be replaced?
- How much margin volatility should we assume in 2026, and what contractual instruments should procurement pursue to stabilize outcomes?
PW Consulting’s approach converts macro uncertainty into discrete, actionable tactics—models, playbooks and decision-support tools that integrate directly with commercial planning and engineering roadmaps. To preserve the strategic value of our synthesis, core segment-level tables, vendor scorecards and granular region/application breakdowns are provided in the full report available through PW Consulting’s research portal.
Next steps and how to access the full analysis
Leaders evaluating supplier strategy, product investment or M&A in 2026 should use this brief as a prelude to the subscriber-only report, which contains the full set of tables, primary-sourced vendor interviews, and downloadable models suitable for boardroom presentation. For access, or to commission a custom brief tailored to your program timelines and procurement levers, contact PW Consulting’s automotive and chassis practice via our website.
PW Consulting’s Stabilizer Bars Market Outlook to 2032 is designed to be a tactical instrument and a strategic north star—helping organizations convert the next two vehicle-program cycles into defensible commercial advantage.
For detailed analysis of this topic, please visit the official page: Stabilizer Bars Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aircraft Interior Lighting Market to Grow from USD 1,450 Million in 2025 to USD 2,306.65 Million by 2032 at a 6.85% CAGR
By pmarketresearch, 2026-07-13
Aircraft Interior Lighting Market: Strategic Imperatives for 2026 — PW Consulting Report
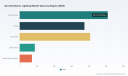
PW Consulting today releases a forward-looking industry brief distilled from our full Aircraft Interior Lighting Market study. The global market for aircraft interior lighting is entering a decisive growth phase: from a base of USD 1,450.0 Million in 2025, our model projects a steady compound annual growth rate (CAGR) of 6.85% through the 2026–2032 forecast window, culminating in a market approaching USD 2,306.65 Million by 2032. These headline figures underscore a resilient, technology-driven expansion that will shape procurement, retrofit, and product roadmaps for OEMs, aftermarket specialists, lessors and airlines in 2026 and beyond.
Aircraft Interior Lighting Market
Why 2026 Is a Strategic Inflection Point
-
Convergence of drivers. Energy-efficient LEDs and emerging OLED technologies, coupled with advances in human‑centric lighting (HCL) and chronobiology-based control systems, are shifting cabin lighting from pure utility to a differentiating passenger-experience platform. The technical benefits—long lifespans (100,000+ hours), significant weight and energy savings, and highly configurable color rendering—are now commercially mature and widely demanded.
Aircraft Interior Lighting Market -
Aftermarket and retrofit momentum. Airlines and lessors pursuing revenue enhancement and cabin renewal are accelerating retrofit programs. As an illustrative benchmark from our field work, an LED cabin lighting upgrade for a typical regional aircraft (covering up-wash, down-wash, reading, lavatory and galley) averages around USD 70,000 including installation—an actionable datapoint buyers can use in total cost of ownership models.
Aircraft Interior Lighting Market -
Regulatory and standards backdrop. Compliance with EASA CS-25 and FAA TSO mandates, together with SAE specification updates, continues to be a gating factor for market entry and product updates. Certification timelines and STC approvals will remain critical operational constraints for new entrants and retrofit vendors alike.
-
Concentrated supplier structure. Market concentration is material: the leading three suppliers control a significant share of the market, and the top five present an even larger combined footprint. For buyers and investors this translates into a marketplace where strategic partnerships, certification portfolios and scale matter as much as product innovation.
What the PW Consulting Report Delivers — Practical Tools for 2026 Decision-Makers
Our full report is organized to be a tactical playbook rather than a purely academic assessment. Key contents include:
-
Actionable market sizing and validated forecasts (2020–2032) with scenario analysis tailored to supply shocks, certification delays and accelerated retrofit cycles.
-
Regulatory and certification matrix mapping EASA, FAA and SAE requirements against product categories and retrofit pathways—highlighting timelines, testing dependencies and common failure modes.
-
Supplier scorecards and procurement playbooks covering technical capability, STC/certification depth, aftermarket reach, and integration risk—designed for sourcing teams evaluating Tier‑1 and Tier‑2 suppliers.
-
Technology roadmaps for LED, OLED, and human‑centric lighting systems, including durability, lifecycle replaceability, control interfaces and retrofitability considerations.
-
Cost‑benefit and TCO templates preconfigured for fleet-level analysis, enabling rapid estimation of payback under multiple utilization and energy-price scenarios (with a separate retrofit cost estimator for regional, narrowbody and widebody platforms).
-
M&A and alliance playbooks that identify value levers—intellectual property, STC portfolios, aftermarket service networks—and a prioritized approach to target screening and diligence.
Competitive Landscape — Positioning, Strengths and Tactical Priorities
The cabin lighting arena is populated by legacy aerospace systems integrators, specialized lighting houses, and nimble aftermarket players. Based on our research and direct industry engagement, the competitive dynamics can be summarized as follows:
-
Tier‑1 integrators (broad systems capability): Firms with full cabin portfolios and strong OEM relationships are leveraging integrated-system offerings—combining cabin wash, mood lighting, reading lights and advanced luminous panels—to lock in platform-level specifications. Their strength lies in certification expertise and cross-platform scale.
-
Specialist lighting companies: These players differentiate through modularity, aesthetics, and innovative light sources (e.g., RGBW strips, decorative finishes). They are frequently faster to market with retrofit-friendly solutions and customizable finishes valuable to airlines seeking brand differentiation.
-
Aftermarket and STC-focused vendors: Companies with strong STC portfolios and FAA approvals are key enablers for operators wanting rapid fleet upgrades without long OEM lead-times. Their strategic value increases as retrofit demand grows.
Selected company observations (high level):
-
Collins Aerospace (RTX): Extensive systems depth across commercial, business and military segments and a clear focus on advanced products (e.g., high‑fidelity luminous panels). Their competitive advantage is end‑to‑end integration and existing OEM attachments.
-
Diehl Aviation: With decades of cabin lighting experience and visible trade‑show activity, Diehl remains a reference supplier for OEMs and airlines seeking integrated, human‑centric solutions—particularly where platform commonality is required.
-
Safran Cabin: Known for high‑CRI solutions and retrofit packages, Safran’s portfolio supports operators prioritizing passenger comfort and maintainability.
-
Astronics & STG Aerospace: Both have positioned themselves around innovative LED strip lighting, programmable mood systems and plug‑and‑play retrofit kits—making them attractive to airlines and completion centers seeking rapid installation and customization.
-
SCHOTT, Luminator, Bruce Aerospace, Aircraft Lighting International, American Bright LED: These players fill critical niches—from decorative, high‑quality finishes to FAA‑approved RGBW systems and custom modules—that support differentiated cabin concepts and aftermarket upgrades.
Recent market signals reinforce these trends: several manufacturers showcased advanced integrated and decorative lighting at the industry expos in 2026, and a number of aftermarket vendors continue to secure FAA approvals for RGBW and three‑wire cabin systems—demonstrating both product maturity and the critical role of certification as a market access filter.
Implications by Stakeholder
-
OEMs: Prioritize ecosystem compatibility and scalable architectures. Offer open control interfaces where possible to capture downstream retrofit opportunities and reduce long‑term support liabilities.
-
Airlines & Lessors: Treat cabin lighting as a revenue and brand tool. Use modular designs and STC-compliant retrofit packages to accelerate cabin refresh cycles while managing downtime and installation costs.
-
Aftermarket Suppliers: Invest in certification pipelines and build strong service networks; the ability to deliver fleet‑wide, fast‑cycle STCs will be a decisive competitive edge.
-
Investors & M&A Teams: Seek targets with combined IP, STC assets, and aftermarket channels; consolidation will likely favor players who can scale certification capabilities and integration services.
Strategic Recommendations for 2026
-
Prioritize human‑centric lighting pilots on representative routes to quantify passenger experience and operational benefits before committing to fleetwide rollouts.
-
Adopt modular, serviceable lighting components and standardized control interfaces to reduce retrofit complexity and future obsolescence risk.
-
For suppliers, invest selectively in STC pipelines and aftermarket service models rather than attempting to be all things to all customers; niche specialization with certification scale wins in the near term.
-
Buyers should incorporate supplier concentration risk into their sourcing decisions and consider multi‑vendor strategies to mitigate single‑supplier exposures.
-
Monitor raw material and component supply chains for LED drivers and critical semiconductors; design for multiple validated sources to avoid program delays.
-
Leverage PW Consulting’s scenario-based TCO templates to stress-test investment cases under different energy price and utilization assumptions.
Accessing the Full Intelligence
This executive brief is a concise synthesis of the full PW Consulting Aircraft Interior Lighting Market report, which contains granular scenario outputs, procurement scorecards, and an interactive retrofit cost model. In line with our “trailer” approach, we have deliberately presented strategic conclusions, supplier analysis and operational recommendations while reserving the detailed segmentation datasets, supplier-specific market shares and appended financial models for the full report. For procurement teams, engineering leaders and corporate strategists preparing 2026 budgets and technology roadmaps, the complete study is a practical toolkit to accelerate decision-making under uncertainty.
To explore the detailed segment-level forecasts, supplier profiles, certification trackers and download our fleet-level TCO tool, please refer to PW Consulting’s Aircraft Interior Lighting Market report landing page.
For detailed analysis of this topic, please visit the official page: Aircraft Interior Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Data Center Consulting Services Market Poised for Strong Expansion at 13.45% CAGR
By pmarketresearch, 2026-07-13
Data Center Consulting Services Market 2026: Strategic Imperatives for Enterprise Decision‑Makers
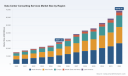
As enterprises accelerate AI deployments, hybrid cloud transformations and sustainability commitments, the global market for data center consulting services has reached an inflection point. Our PW Consulting Market Report — anchored on a robust historical series (2020–2025) and a forward-looking forecast (2026–2032) — shows the market expanding at a compound annual growth rate (CAGR) of 13.45%. After a steady climb from 2020, the market size reached roughly USD 28.4 billion in 2025 and is projected to more than double over the forecast horizon, reflecting the capital intensity and strategic complexity of modern data center programs. For executives making capital allocation, site selection and operating-model decisions in 2026, the timing and granularity of insight could materially affect both cost and operational risk.
Data Center Consulting Services Market
Why 2026 Is a Strategic Turning Point
- Convergence of capacity and capability demand: Cloud and AI workloads are driving demand for new capacity and for higher‑density, purpose‑built facilities. Market participants from engineering firms to IT consultancies and real‑estate specialists are broadening capabilities to capture this demand.
- Regulatory and compliance acceleration: New emissions and privacy rules are shifting design specs and operating requirements. Examples include state-level emissions standards for emergency generators and national rules that tighten controls around bulk personal data — both of which can alter siting, equipment selection and operating procedures.
- Workforce and delivery model stress points: Large-scale upskilling and apprenticeship programs are emerging to address shortages in mission‑critical trades. Simultaneously, prime contractors and consultancies are investing in digital project-delivery and AI-enabled capital-program tools to compress schedules and mitigate labour risk.
- Sustainability and biodiversity as investment filters: Investors and hyperscalers are increasingly pricing in ESG outcomes; partnerships that embed biodiversity and regenerative design into campuses are shifting the value equation for greenfield and brownfield projects.
Report at a Glance — Practical, Actionable Content
The PW Consulting report is structured to be operationally useful for C-suite and program teams tasked with building, upgrading or managing data center portfolios. It blends macro forecasting with tactical tools that can be applied immediately within procurement cycles and capital planning windows:
Data Center Consulting Services Market
- Scenario-based market-sizing and demand curves (2026–2032), including sensitivity to key drivers such as AI density, cloud migration rates and regional power constraints.
- Capital- and life‑cycle cost models that translate design decisions (e.g., efficiency, redundancy, generator choices) into multi‑year TCO outcomes under different fuel and emissions regimes.
- Site-selection and resilience frameworks that weight energy, connectivity, regulatory, and community acceptance variables for both hyperscale and enterprise footprints.
- Vendor selection scorecards and RFP templates tailored for design & engineering, strategy & planning, migration, and operations & maintenance engagements.
- Operational playbooks for O&M teams, including KPI libraries, workforce training roadmaps, and digital twin checklists to accelerate commissioning and reduce mean time to repair.
- Regulatory impact toolkits and privacy/compliance matrices that align technical controls with new legal obligations and state-level standards effective in 2026.
- ESG & sustainability playbooks — from embodied carbon accounting to biodiversity integration and energy procurement design patterns — that support investment-grade sustainability narratives.
Note: the report includes detailed segmentations and company-level profiles underpinning these tools. To preserve the strategic value of those granular datasets and vendor rankings, that proprietary segmentation is available in the full report.
Data Center Consulting Services Market
Competitive Landscape: Reading the Players
The data center consulting ecosystem is a heterogeneous mix of engineering firms, global management consultancies, IT services specialists and real estate advisors. Market concentration metrics indicate the space remains fragmented — with the top few firms holding modest collective share — which creates room for both scale players and specialist boutiques to win business based on project type and client preferences.
- AECOM & Jacobs: Engineering and project-delivery specialists that excel in full lifecycle delivery for mission-critical facilities. Their strengths lie in site engineering, commissioning discipline and large-scale program management across complex regulatory geographies.
- Arup & Ramboll: Technical and sustainability-led firms with deep design capabilities. They are often the go-to partners when architectural integration, thermal management and low-carbon design are priority decision criteria.
- Accenture & IBM Consulting: IT and systems integrators that bridge infrastructure modernization, cloud migration and AI enablement. Accenture’s recent capital delivery capability enhancements and IBM’s hybrid cloud messaging position both as strategic advisors for transformation-led projects.
- Deloitte, PwC & EY: Advisory firms that combine risk, compliance and transaction advisory with the ability to orchestrate complex, multi-stakeholder transformations; they are often engaged at portfolio strategy and M&A stages.
- JLL: Real estate and investment advisory specialists playing a pivotal role in site economics, capacity pipeline assessment and investor due diligence; their market outlooks are watched closely by capital allocators.
- HCL Technologies, Kyndryl & TCS: Tech-centric service firms that focus on infrastructure management and managed services, increasingly positioning themselves around lifecycle O&M and migration services for enterprise clients.
- McKinsey & Company: Strategy and high-level transformation advisory, often engaged for portfolio rationalization, large-scale operating model redesign and AI-driven infrastructure strategies.
Recent market moves underscore how firms are reshaping capabilities: a notable acquisition to strengthen capital project delivery; partnerships that embed biodiversity into campus planning; and public outlooks projecting significant new capacity pipelines — all of which change where and how consultancies compete and collaborate.
How Senior Leaders Should Use This Report in 2026
- CFOs: Use the TCO models and scenario analyses to validate multi‑year capex envelopes, stress-test financing structures, and quantify the value of performance guarantees and O&M outsourcing.
- CTOs & Infrastructure Heads: Leverage migration scorecards and vendor shortlists to accelerate cloud-on-prem decisions and to lock down interoperability and AI-readiness requirements before procurement.
- Real Estate & Portfolio Leads: Apply the site-selection framework and regional scenario planning to prioritize greenfield vs. colocation strategies and to model grid risk and land-use constraints.
- Compliance & Legal Teams: Use the regulatory impact toolkit to map new state and federal rules to contractual obligations, control matrices and consent mechanisms for sensitive datasets.
- HR & Ops Leaders: Adopt the workforce roadmap to align hiring and apprenticeship investments with the project pipeline and digital delivery ambitions.
Signals to Watch in H2 2026 and Beyond
- Announcements of major capacity pipelines and campus launches — these validate demand assumptions and shift supplier capacity.
- Regulatory updates around emissions, emergency power standards and data handling — nuanced compliance costs can change site economics overnight.
- Scaling of workforce training initiatives and apprenticeship rollouts — efficacy here will influence schedule risk and labor cost trajectories.
- Partnerships marrying biodiversity and campus design — these will test market willingness to pay for differentiated ESG outcomes.
- M&A and capability bundling among consultancies — watch for acquisitions that close gaps in capital delivery, digital project tools or sustainability verification.
Conclusion — The Strategic Value of Timely Insight
For 2026, the combination of brisk market growth, regulatory tightening and technology-driven demand means companies can no longer treat data center consulting as a commodity purchase. The PW Consulting report is designed to convert market intelligence into executable plans — supplying senior teams with the templates, scenario models and decision frameworks needed to optimize cost, de‑risk delivery and embed sustainability outcomes. We present a comprehensive, operationally oriented view of the market while preserving the proprietary granularity that clients use to make procurement and investment decisions. For executives serious about securing competitive advantage in the next wave of data center investment, the full report contains the datasets, proprietary scoring matrices and vendor benchmarking that convert high‑level insight into board‑ready recommendations.
Access to the full dataset, segmentation tables, and the vendor comparator suite is available through the PW Consulting report page — where you can download executive summaries, order the full study, and schedule an advisory briefing to align the findings to your 2026 investment roadmap.
For detailed analysis of this topic, please visit the official page: Data Center Consulting Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Flexible Liquid Cooled Cable Market to Surge at 23.01% CAGR, Hitting USD 2,385.19 Million by 2032
By pmarketresearch, 2026-07-13
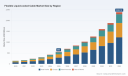
Flexible Liquid-Cooled Cable Market: Strategic Imperatives for 2026 — PW Consulting Release
PW Consulting today publishes an executive briefing drawn from our forthcoming Flexible Liquid Cooled Cable Market report, providing senior executives and investment committees with the strategic context they need as they plan for 2026. The market for flexible liquid-cooled cables has evolved from a niche industrial enabler to a critical infrastructure component across ultra-fast EV charging, data center power delivery, and heavy industrial applications. Our analysis synthesizes historical performance, supply-chain realities, regulatory inflection points, and vendor capabilities to show where near-term competitive advantage will be created — and where risks remain embedded.
Flexible Liquid Cooled Cable Market
Market trajectory: robust expansion with structural drivers
Demand for flexible liquid-cooled cables has accelerated sharply over the past half-decade. The global market expanded from roughly USD 145 million in 2020 to an estimated USD 560 million by our 2025 base year, driven by both industrial retrofit cycles and the rapid roll‑out of megawatt-class EV charging infrastructure. As adoption moves from pilots to commercial deployments, our central forecast model projects a compound annual growth rate (CAGR) of approximately 23.0% for the 2026–2032 period, with the market scaling toward the multi‑billion-dollar range by the end of the forecast horizon.
Flexible Liquid Cooled Cable Market
This growth is not evenly distributed across applications or regions; instead, it is concentrated in use-cases that require sustained high currents (hundreds to over a thousand amps) combined with ergonomic handling characteristics. These macro numbers provide the context for 2026 decision-making: the window to secure industrial partnerships, certification paths, and supply-chain resilience is now.
Flexible Liquid Cooled Cable Market
What the report delivers — actionable, decision-grade intelligence
- Quantitative market sizing and baseline-to-2032 forecasts with scenario sensitivities to raw material price swings and accelerated EV adoption curves.
- A regulatory and standards matrix mapping IEC, UL, and ISO requirements relevant to liquid-cooled systems — plus clear pathways to certification for product teams and test laboratories.
- Supplier and technology scorecards that benchmark design approaches (water-glycol vs. oil vs. fluorinated coolants), conductor choices, and manufacturability constraints.
- Supply-chain heat maps that identify single‑source exposures, copper procurement levers, and preferred contract structures for 2026 negotiations.
- Commercial playbooks for OEMs, charge-point operators, and EPCs outlining bundling strategies, service economics, and aftermarket revenue models.
- Go-to-market options, from strategic partnerships and licensing to bolt‑on M&A targets, prioritized by ease-of-integration and ROIC under multiple adoption scenarios.
We intentionally withhold granular regional and application splits in this briefing to preserve the report’s role as the primary source for purchase-level intelligence; those detailed sub‑segment datasets and interactive models are accessible in the full PW Consulting report.
Competitive landscape: consolidation with diverse specialists
The supplier ecosystem is a mixture of specialist fabricators that serve heavy industry and high-current thermal applications, and larger electrical component players rapidly commercializing liquid-cooled solutions for the EV charging market. Market concentration metrics indicate meaningful but incomplete consolidation: the leading three players control a significant share of the market, while the top five consolidate a clear majority — a structure that favors strategic alliances without precluding new entrants from gaining traction through differentiated engineering or regional distribution strength.
- Specialist fabricators (examples include firms with deep histories in induction heating, resistance welding, and furnace leads) are distinguished by custom engineering capabilities, rapid turnaround on repairs, and intimate knowledge of high-current terminalization and coolant routing. Their strengths lie in bespoke solutions and service models tailored to heavy industry maintenance cycles.
- Industrial-scale suppliers and Tier‑1 electrification vendors are commercializing modular, standardized liquid-cooled cable systems optimized for electric-vehicle ultra-fast charging. These players leverage systems engineering, ergonomic design, and global support networks to drive commercial rollouts with large charging-station OEMs and network operators.
- Newer entrants and regional manufacturers are pushing innovation at the conductor and hose-material level, while some vendors specialize in very large cross-section cables for steel and ferroalloy plants — showcasing the breadth of technical pathways in the market.
Key names across both archetypes include recognized specialists in water-cooled power leads and a cohort of established electrification players that have introduced liquid‑cooling products and connector platforms for megawatt-class charging. Recent industry moves — such as product integrations between major connector manufacturers and charger OEMs, and field deployments charging above the megawatt threshold — underscore the rapid shift from prototype validation to commercial utilization.
Regulation, materials, and standards: non-negotiable elements of 2026 strategy
Three practical points for engineering and compliance teams:
- Copper remains the predominant conductor material because it offers the best combination of thermal and electrical performance; high‑conductivity electrolytic grades are commonly specified in performance‑critical leads. Securing material supply and specifying contract provisions for grade and traceability will be decisive for product consistency and warranty performance.
- Product designs typically use specialized protective hoses and high-temperature tubing to enclose stranded conductors and enable coolant circulation without sacrificing flexibility. Design tolerances around bend radius, thermal expansion, and terminal swivels materially affect lifecycle costs and handling ergonomics.
- Liquid-cooled systems must comply with a set of international standards — examples include IEC connector frameworks, UL safety standards, and ISO insulation and touch‑temperature limits — and suppliers who can demonstrate early certification or an auditable path to certification will be preferred partners in 2026 procurement cycles.
Notably, the industry is moving toward formalized safety certifications for megawatt-class systems; the first UL certifications supporting 1 MW-class liquid-cooling systems appeared recently, which is lowering a barrier to commercial scale deployments and giving early movers a durable advantage.
Strategic recommendations for 2026 decision-makers
Based on our modeling and vendor due diligence, PW Consulting recommends the following priority actions for organizations allocating capital or signing supply contracts in 2026:
- Prioritize certified partners: Require suppliers to demonstrate compliance roadmaps (IEC/UL/ISO) and factory test evidence; for charger OEMs, mandate fielded-system performance at target current/power levels as a contract milestone.
- Lock in copper supply with quality specifications: Negotiate grade‑specific clauses (e.g., electrolytic copper grades) and consider hedging strategies to mitigate short-term price volatility.
- Pilot ergonomics and maintainability at scale: For EV charging operators, user handling and replacement turnaround times are operational cost drivers; insist on modular terminations and field-replaceable sections in procurement specifications.
- Design for service revenue: Build service networks and remote diagnostics pathways to capture recurring maintenance margins; warranty frameworks should incentivize preventive replacement of high‑wear interfaces.
- Explore targeted M&A and partnerships: Acquire or partner with specialist fabricators to secure IP around terminalization and large-section joints, or to gain regional manufacturing footprints with lower lead times.
- Invest in lab and field validation: Allocate budget for accelerated life testing and temperature/flow profiling, and fund first-of-kind deployments to validate cooling strategies under realistic duty cycles.
Scenarios and risks
Our scenario analysis centers on two sensitivities that will shape outcomes in 2026: the cadence of EV ultra-fast charger rollouts and raw-material inflation. Under the baseline growth trajectory (the ~23% CAGR outlook), commercial scale deployments and standardized connectors will drive sizable volumes and faster maturation of supplier ecosystems. Upside scenarios incorporate regulatory incentives and faster station buildout, while downside outcomes are dominated by sustained copper price shocks or delays in equipment certification.
Operational risk is concentrated in terminal reliability, cooling loop integrity, and field repairability; each has direct consequences for uptime economics in charging networks and for maintenance budgets in industrial installations.
Why PW Consulting’s guidance matters for 2026
Our report combines granular engineering insight with strategic commercial frameworks: market-sizing that starts from audited historical shipments, a forecast model calibrated to adoption drivers, and a vendor evaluation methodology that blends technical scorecards with commercial viability assessments. For boards and investment committees, this delivers a practical bridge between engineering feasibility and balance-sheet implications — enabling conditioned commitments to capital equipment, supply agreements, and M&A pursuits that will be executed during 2026.
Next steps
PW Consulting’s full Flexible Liquid Cooled Cable Market report includes the detailed segmentation datasets, company scorecards, and downloadable forecast models that underpin the executive recommendations summarized here. For procurement teams, product leaders, and corporate strategists preparing commitments in 2026, these assets are designed to accelerate decision-making while reducing program execution risk.
Contact PW Consulting to request the full report, vendor benchmarking appendices, and an in‑person briefing with our industry analysts.
For detailed analysis of this topic, please visit the official page: Flexible Liquid Cooled Cable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Press Hardening Machine Market Poised for 7.32% CAGR, Surging to USD 1,674.65 Million by 2032
By pmarketresearch, 2026-07-13
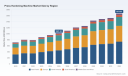
Press Hardening Machine Market: Strategic Playbook for 2026 Decision-Makers
PW Consulting today publishes a focused industry briefing drawn from our full Press Hardening Machine Market report (base year 2025, forecast 2026–2032). This executive-oriented release synthesizes the implications senior leaders need to act on in 2026 — from capital allocation and supplier selection to technology roadmaps and M&A strategy — while preserving the granular subsegment intelligence that makes the full report essential for implementation teams.
Press Hardening Machine Market
Market snapshot: momentum and medium‑term opportunity
The press hardening equipment market has transitioned from a niche specialty into a core enabler of structural lightweighting across automotive, commercial vehicle and select industrial segments. Our consolidated market model records an increase in overall industry revenues from roughly USD 715 million in 2020 to just over USD 1.02 billion in 2025 (USD Million, nominal). The market is forecast to continue expanding through the 2026–2032 horizon at a compound annual growth rate of 7.32%, reaching an estimated USD 1.67 billion by 2032.
Press Hardening Machine Market
This pace reflects the intersection of three durable forces: accelerating adoption of ultra‑high strength steels (UHSS) for crash management and mass reduction, manufacturer investments in faster and more energy‑efficient lines, and continuing OEM demand for integrated, traceable production capable of meeting stringent automotive heat‑treat quality regimes.
Press Hardening Machine Market
Why 2026 is a strategic inflection year
- Regulatory and safety-driven material shifts. Press hardening enables production of components using UHSS grades up to 2000 MPa, supporting vehicle lightweighting strategies that in some modern architectures assign 20–40% of bodyweight to press‑hardened parts. That structural role elevates press hardening from a cost item to a safety and performance enabler.
- Efficiency becomes a board‑level KPI. Recent vendor innovations show step‑change energy improvements: servo‑driven press platforms paired with multi‑layer furnace concepts claim material reductions in line energy intensity. Buyers in 2026 should prioritize solution footprints that materially cut energy and improve throughput per capita, because energy and carbon intensity are now central to procurement and total cost of ownership.
- Heat‑treat process traceability is table stakes. Compliance to automotive heat‑treat standards increasingly relies on in‑line monitoring with pyrometers, infrared imaging and linked analytics. The combination of process control and machine‑level IIoT capability is differentiating suppliers and shaping warranty and quality accountability models.
- Input cost volatility compresses margins. Steel feedstock remains the dominant cost in press‑hardening value chains. With raw materials representing a large share of steel production costs, procurement teams must bake volatility scenarios and hedging options directly into capital and operating models for new lines.
Competitive landscape — consolidation, capabilities and strategic postures
The market is moderately consolidated. The three largest suppliers account for a majority share of global installed capacity, and the top five capture more than two‑thirds of the market by revenue. That concentration shapes pricing dynamics, technology diffusion, and the bundling of turnkey services such as furnace design, automation, tooling and in‑line inspection.
- AP&T (Ulricehamn, Sweden). A long‑standing pioneer in press hardening, AP&T combines complete turnkey production solutions with energy‑focused system design. Its SkyLines concept and multi‑layer furnace architectures target large, complex EV structures — with vendor‑reported energy gains that buyers will see reflected in total cost models. AP&T’s emphasis on integrated monitoring and modular line concepts positions it as a preferred partner for OEMs seeking scalability and sustainability.
- Fagor Arrasate (Arrasate, Spain). Known for fully automated integrated systems, Fagor Arrasate continues to compete on delivering high‑output, tightly integrated press hardening lines with sophisticated servo‑hydraulic drive architectures and multilevel furnace solutions — a strong value proposition for high‑mix, high‑volume programs.
- Schuler Group (Göppingen, Germany). Schuler’s technology portfolio targets high‑precision, high‑cadence production with architectures that support multiple part types per line at elevated throughput. For programs where takt and cycle efficiency are primary constraints, Schuler is frequently shortlisted.
- Macrodyne Technologies Inc. (Canada). A strong supplier of custom hydraulic and servo hot‑stamping presses, Macrodyne’s recent trade‑show activity reflects its continuing focus on heated platen and specialty forming solutions — a fit for Tier‑1 suppliers and integration projects with complex part geometry.
- Loire Gestamp / AFM (Hernani, Spain). With a history in hydraulic hot stamping lines and associated furnaces, Loire Gestamp remains relevant where proven hydraulic architectures and tailored line engineering are prioritized over platform standardization.
Recent vendor activity confirms two directional bets in the vendor community: deeper vertical integration of furnace + press + automation to deliver predictable quality and energy outcomes, and productizations that reduce customization lead times for EV platform programs. AP&T’s SkyLines presentation (mid‑2025) and Macrodyne’s MACH 2026 showcase illustrate these twin dynamics: energy and scalability on one hand; niche, high‑complexity capacity on the other.
Strategic implications for buyers and investors in 2026
- CapEx framing and total cost of ownership. Procurement must move beyond headline machine price. Energy consumption, maintenance intervals, monitoring capability and retrofit potential materially change ROI timelines. Select line architectures that preserve upgrade paths for controls and sensing — this reduces lifecycle risk.
- Technology choices must align with program mix. Servo‑mechanical platforms offer energy arbitrage and throughput advantages for high‑mix, variable run programs; hydraulic systems retain advantages for specific heavy‑forming applications. Our report provides scenario matrices that help teams map line type to program economics.
- Supplier risk and supply chain resilience. Given the concentration profile, buyers should pursue a dual strategy: a primary strategic partner plus validated secondary suppliers to mitigate lead‑time and geopolitical risk. Near‑term raw material exposure suggests integrating steel procurement strategies into machine purchase decisions, including indexed contracts and safety stock strategies.
- Service and aftermarket as margin levers. As lines become more instrumented, opportunities for performance‑based service contracts, remote diagnostics and outcome‑linked warranties expand. Investors and OEMs should quantify serviceable revenue as part of lifecycle models.
- M&A and partnership playbook. Consolidation and capability gaps create actionable targets. Buyers with systems integration strengths may find attractive bolt‑on targets among regional line builders; conversely, established OEMs can accelerate capability by securing long‑term supplier partnerships that include technology roadmaps and co‑development clauses.
What PW Consulting’s full report provides (practical contents)
The complete study delivers operationally actionable intelligence designed for program managers, procurement leads, plant engineering, and corporate strategy teams. Core deliverables include:
- Historical market sizing (2020–2025) and a granular forecast through 2032 with scenario sensitivity to energy and raw material price swings;
- Segmented demand analysis by geography, machine configuration and component families, with buyer requirement matrices (note: detailed subsegment tables and vendor share models are available in the full report);
- Vendor benchmarking and capability maps covering control systems, furnace architectures, automation and in‑line monitoring;
- Capital and operating expenditure models, including payback and NPV templates that fold in energy consumption and material cost assumptions;
- M&A target screening criteria and a shortlist of priority acquisition archetypes for private equity and strategic acquirers;
- Implementation playbooks: procurement checklists, commercial terms to negotiate, test acceptance criteria for plant trials, and a 12–36 month deployment roadmap.
Methodology and confidence indicators
The report uses a hybrid research methodology: supplier financials and shipment data, primary interviews with manufacturers and OEMs, plant‑level intake and commissioning schedules, together with bottom‑up cost modelling that explicitly includes steel feedstock exposure and energy consumption. The base year is 2025, historical coverage is 2020–2025, and forecasts extend 2026–2032. Our concentration metrics and market share assessments are constructed to help executives assess supplier bargaining power and consolidation risk.
How to use this insight in 90 days
- Prioritize a cross‑functional steering team (procurement, engineering, sustainability, legal) to convert report scenarios into a Program Decision Matrix;
- Run two vendor pilots: one focused on energy‑efficient servo + multi‑layer furnace options, one focused on high‑complexity hydraulic/transfer solutions;
- Integrate raw material price hedging clauses into supplier contracts and model P&L sensitivity across +/- 15% steel cost swings; and
- Create a service and performance KPI framework that aligns payment milestones with demonstrated energy and quality results during a defined ramp period.
PW Consulting’s Press Hardening Machine Market report is positioned to be the practical playbook for 2026 capital allocation and supplier strategy. If your organization must decide on line investments, retrofit budgets or strategic supplier partnerships this year, the report equips you with the scenario tools, vendor maps and execution checklists to move from deliberation to deployment with confidence.
To access the full dataset, detailed segmentation tables, vendor scorecards and procurement templates, please visit our report page or contact PW Consulting directly for a briefing and customized workshop.
For detailed analysis of this topic, please visit the official page: Press Hardening Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Gestational Trophoblastic Disease Market to Expand at a 5.81% CAGR Through 2032, Sparking Growth Opportunities in Chemotherapy and Diagnostics
By pmarketresearch, 2026-07-13
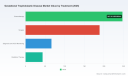
PW Consulting: Strategic Brief — Gestational Trophoblastic Disease Market Outlook 2026 and Beyond
Executive snapshot
PW Consulting today publishes a strategic preview of our comprehensive market study on Gestational Trophoblastic Disease (GTD), designed specifically to inform executive decision-making in 2026. The GTD market has demonstrated steady expansion over the 2020–2025 base period, growing from a mid‑hundreds million USD base to an estimated USD 546.0 Million in 2025. Under our baseline forecast (2026–2032) the market is projected to grow at a compound annual growth rate (CAGR) of 5.81%, reaching an estimated USD 810.3 Million by 2032. This trajectory is being shaped by clinical advances, evolving guideline recommendations, growing off‑label and trial use of immunotherapies, and persistent demand for established chemotherapeutics and diagnostic monitoring services.
Gestational Trophoblastic Disease Market
Why this report matters for 2026 strategy
- Actionable forecasting: Our model combines epidemiology, treatment pathway adoption scenarios, and pricing/reimbursement assumptions to translate clinical developments into revenue implications across the forecast horizon.
- Decision-grade intelligence: The report bridges clinical nuance (e.g., low‑risk vs high‑risk GTN pathways) with commercial realities—supply chains for injectable chemotherapy, generics pressure, and payers’ growing scrutiny of immuno‑oncology for rare indications.
- Playbook orientation: Rather than theoretical commentary, the work provides go/no‑go decision frameworks, commercial launch sequencing guidance, and partnership archetypes relevant to pharma, diagnostics firms, and private equity investors active in onco‑rare disease portfolios.
Market dynamics shaping near‑term choices
Several interlocking dynamics create both risk and opportunity for stakeholders in 2026:
Gestational Trophoblastic Disease Market
- Therapeutic continuity vs disruption: Standard single‑agent regimens (methotrexate +/- folinic acid or actinomycin D) continue to deliver >95% success in low‑risk GTN, while multi‑agent EMA/CO regimens yield long‑term survival in the mid‑80s to mid‑90s percent range for high‑risk cases. These high baseline cure rates mean innovations must demonstrate either clear safety/tolerability advantages, avoidance of escalation to multi‑agent chemotherapy, or superior outcomes in refractory disease to gain traction.
- Immunotherapy enters clinical practice: Recent trials and guideline shifts are accelerating interest in checkpoint inhibitors. Notably, ESMO‑presented data from the TROPHAMET program showed a meaningful improvement in complete response metrics when avelumab was combined with an 8‑day methotrexate schedule versus methotrexate alone in low‑risk GTN—an outcome now reflected in 2025 international consensus guidance as a potential option to reduce escalation to multi‑agent regimens in select settings.
- Off‑label and guideline‑driven use in resistant disease: Checkpoint inhibitors (e.g., pembrolizumab) are being recommended by some national payers for multi‑drug resistant high‑risk GTN after multiple chemotherapy lines, while broader regulatory approvals for GTD remain limited. This creates a complex mix of trial, compassionate use, and payer‑specific access pathways through 2026.
- Adjunct and repurposing research: Early‑stage modalities—focused ultrasound in localized research programs and preclinical explorations of statin repurposing for choriocarcinoma—signal a widening innovation set, though commercial availability and scale remain several years out.
Competitive landscape — capability map, not a leaderboard
The GTD market exhibits moderate concentration: the top three companies capture a meaningful share of market activity, while the top five firms account for a majority of commercial presence and supply chain influence. This structure supports differentiated competitive moves across innovators and generics manufacturers.
Gestational Trophoblastic Disease Market
- Established oncology leaders (Pfizer, Novartis, Bristol‑Myers Squibb): These firms supply key chemotherapeutic agents that underpin standard-of-care single‑agent and multi‑agent regimens. For incumbents, the strategic choices in 2026 center on lifecycle management (supply continuity, formulation improvements), value‑based contracting in advanced markets, and selective clinical investments that protect or expand regimen relevance in the face of immunotherapy options.
- Generics and injectables specialists (Hikma, Teva, Fresenius Kabi): Price competition and manufacturing scale are core advantages. Near‑term strategic levers include sterile injectable capacity investments, geographic expansion into under‑served referral centres, and service bundles (diagnostic integration, patient support) to defend margins.
- Immuno‑oncology entrants and alliances (Merck & Co., Merck KGaA/Pfizer alliance for avelumab): Checkpoint inhibitors are increasingly relevant for chemo‑resistant cases and as potential first‑line augmentations. Companies controlling these agents face choices around label expansion strategies, payer evidence generation, and partnering with centers of excellence for real‑world outcome studies.
Recent developments that change tactical priorities
- March 2026 — TROPHAMET data announced at ESMO: Avelumab combined with an 8‑day methotrexate schedule demonstrated a material improvement in hCG normalization rates versus methotrexate alone in low‑risk GTN. This evidence is accelerating payer conversations and could alter first‑line algorithms in jurisdictions that rapidly adopt guideline updates.
- 2025 international consensus guidelines: Collaborative guidance from major GTD and gynecologic oncology societies explicitly recognize avelumab as an option in selected low‑risk cases—creating an access inflection point for companies with immunotherapy portfolios and for suppliers of methotrexate who participate in combination regimens.
- Payer and regulatory nuance: Pembrolizumab is being recommended in some national pathways for patients who have failed multiple chemotherapy lines, but full regulatory approvals for checkpoint inhibitors in GTD remain limited—presenting a patchwork access environment.
- Innovation watch: Focused ultrasound and statin repurposing remain investigational; these areas merit monitoring for future partnership or licensing opportunities rather than immediate commercial bets.
What’s in the full PW Consulting report (practical components)
- Rigorous market-sizing and forecast model (2020–2032) with scenario toggles for guideline adoption, immunotherapy penetration, and pricing pressure.
- Detailed treatment‑pathway maps and patient flow models that translate clinical decision points into unit volumes and service demands.
- Payer and reimbursement playbooks, including HTA requirements, coverage pathways for off‑label immunotherapies, and contracting templates for high‑cost agents used in rare cancers.
- Competitive dossiers and capability matrices for the leading manufacturers and service providers (manufacturing footprints, sterile injectable capacity, portfolio overlap, clinical investment roadmaps).
- Clinical pipeline assessment and probability‑weighted launch impact analysis for key immunotherapies, novel therapeutics, and diagnostic/monitoring technologies.
- Commercial strategy blueprints: go‑to‑market sequencing, tendering tactics in emerging markets, and patient support program designs to maximize adherence to HCG monitoring protocols.
- M&A and partnership screening tools: acquisition candidate scoring, integration risk checklists, and divestiture playbooks tailored for rare‑oncology assets.
- Real‑world evidence and post‑launch outcomes trackers templates to support payer negotiations and guideline adoption.
Actionable recommendations for 2026 corporate planning
- For innovators with immunotherapy assets: accelerate targeted RWE (real‑world evidence) programs in referral centers and prepare flexible pricing strategies tied to outcome milestones—this reduces payer resistance where label expansion is limited.
- For generics and injectables manufacturers: prioritize sterile injectable capacity upgrades and geographic distribution partnerships to capture demand volatility from occasional guideline‑driven therapy shifts.
- For companies owning methotrexate/dactinomycin portfolios: defend regimen relevance by investing in co‑development studies with immunotherapy partners and by offering integrated diagnostic/monitoring services that simplify clinician adoption.
- For investors and private equity: screen targets for manufacturing resilience, regulatory risk exposure (off‑label reliance), and differentiated service offerings (diagnostic+therapy bundles) that increase stickiness.
- Across the board: embed payer engagement at the earliest trial design stage for any program targeting GTD, given the high cure rates with standard regimens and the premium payers place on demonstrable reductions in escalation to multi‑agent chemotherapy.
How PW Consulting supports your next moves
Our GTD report is structured to move teams from insight to implementation. We provide modular deliverables (board briefs, acquisition screens, country access dossiers, and launch readiness checklists) and a responsive advisory option to help operationalise recommendations in the 12–18 month window following publication. For teams evaluating portfolio allocation, the report’s scenario models allow rapid sensitivity testing of market outcomes under alternate guideline adoption, therapeutic success, and pricing environments.
Next steps
This briefing is intentionally selective: it surfaces the critical levers and recent inflection points shaping GTD strategy while withholding granular segment tables and market split figures to preserve the investigative value of the full report. Executive teams seeking the complete dataset, region‑level forecasts, segment breakdowns, and competitor revenue estimates are invited to access the full PW Consulting GTD Market Report via our publication page. Engage PW Consulting for a tailored executive workshop that translates our findings into a bespoke 90‑day action plan aligned to your business objectives.
For detailed analysis of this topic, please visit the official page: Gestational Trophoblastic Disease Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial-Grade GBL Market Set to Grow at a 5.48% CAGR Through 2032 as Asia‑Pacific Demand Surges
By pmarketresearch, 2026-07-13
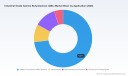
Industrial-Grade Gamma-Butyrolactone (GBL) Market—Strategic Preview for 2026 Decisions
PW Consulting’s latest Industrial Grade Gamma-Butyrolactone (GBL) Market report translates a complex and evolving chemicals landscape into actionable strategy for executives planning around 2026. This preview synthesizes the report’s high-conviction findings—anchored in a robust dataset and scenario modelling—so business leaders can prioritise near-term commercial, supply-chain, and regulatory moves without waiting for the full dataset. To preserve the research’s proprietary value, this article outlines frameworks, directional forecasts, competitive insights and decision triggers while intentionally withholding granular segment-level tables and pricing schedules available only in the full report.
Industrial Grade Gamma Butyrolactone Gbl Market
Market snapshot: what the numbers imply for 2026
GBL’s industrial market has demonstrated steady recovery and structural demand growth through the early 2020s. From a 2020 baseline, the market expanded through 2025 to a global value of approximately USD 4.44 billion (USD Million unit basis). Our forecast framework—covering 2026–2032—projects a compound annual growth rate (CAGR) of 5.48%, taking the market toward roughly USD 6.44 billion by 2032 under the base scenario.
Industrial Grade Gamma Butyrolactone Gbl Market
Two implications flow directly from this trajectory for 2026 strategic planning:
Industrial Grade Gamma Butyrolactone Gbl Market
- Near-term supply-demand balance will remain sensitive to feedstock and energy dynamics. Even modest feedstock moves can create regional cost dislocations that open short windows for margin capture or prompt inventory rebalancing.
- Structural demand drivers—especially electronics, battery materials (via N-methyl-2-pyrrolidone, NMP), and specialty solvent applications—are firming up long-term premium segments. Firms that can align production quality, reliability and sustainability credentials will capture outsized returns as markets bifurcate into commodity and premium streams.
Why this report matters to C-suite and portfolio teams in 2026
- Strategic procurement: The report maps BDO-to-GBL cost pass-through dynamics and presents scenario-based hedging options. Procurement teams will find the modelling useful for negotiating multi-year contracts and short-term purchasing strategies in 2026.
- Capital allocation: We provide an investment-priority matrix that ranks brownfield debottlenecking, greenfield capacity and downstream integration by expected ROI under three realistic raw-material price trajectories—critical input for 2026 CAPEX reviews.
- M&A and partnership screening: Our company-level diligence and M&A heatmaps identify targets and acquirers whose near-term strategic moves are likely to reshape regional footprints and access to premium end-markets.
- Regulatory & compliance planning: With granular coverage of regional regulatory regimes and trade controls, the report equips compliance functions to pre-empt licence and registration friction points coming online in 2026.
What the full report contains (practical, decision-ready content)
- Proprietary market-sizing and scenario models (2020–2032) with sensitivity testing to feedstock and energy price shocks.
- Supply-side map: plant-level capacity, vintage, technology route and purity capabilities (interactive), with qualitative indications of ramp risk and feedstock exposure.
- Demand-side segmentation by end-use, purity specification and substitution risk—with tactical playbooks for suppliers, consumers and distributors.
- Pricing dashboard and pass-through model that ties regional BDO indexes to GBL traded values and margin bands.
- Regulatory compendium and transaction checklist tailored for trade, logistics and product stewardship teams operating across the US, EU, China and Asia Pacific.
- Competitive profiles and scenario-driven strategic options for incumbent producers, new entrants and speciality chemical integrators.
These tools are built to be used in boardrooms and procurement war-rooms throughout 2026—supporting faster, higher-confidence decisions without sacrificing rigor.
Competitive landscape: how leading players are positioning for 2026
The GBL market demonstrates moderate concentration: the largest three firms control a meaningful plurality of supply, and the top five firms together represent a clear majority. This concentration profile creates both friction and opportunity: the incumbents can discipline capacity growth and margins, while nimble challengers can carve niches via quality, sustainability claims, or closer proximity to fast-growing end-markets.
- Mitsubishi Chemical Corporation —A strategic advantage lies in high-purity capability and an established continuous-process production route. Recent capacity moves at its Okayama site underline a deliberate tilt toward electronics and battery supply chains that demand both quality and reliability.
- BASF SE —BASF combines scale with an explicit sustainability proposition (biomass-balanced and PCF reporting across BDO/THF/GBL). For offtakers prioritising lifecycle claims or facing customer-driven ESG requirements, BASF’s integrated value chain is a differentiator.
- Ashland Inc. —A market influencer in pricing and product positioning, Ashland’s publicised price actions in 2025 reflect upstream cost pressures and demonstrate how integrated BDO/derivative players can use commercial levers to defend margins.
- LyondellBasell —Leverages proprietary process know-how and integration into oxirane derivatives; a strategic choice for customers seeking supply continuity tied to wider polymer and specialty-chemical portfolios.
- Regional and specialty producers (examples from Taiwan and China) — Offer flexible supply, localised service and competitive cost structures. Their role is increasingly strategic: they provide agility and local logistics efficiencies in regions where demand is expanding fastest.
Each player’s 2024–2026 actions—price moves, capacity tweaks and sustainability reporting—provide leading indicators for how 2026 market tightness and margin pools will evolve.
Feedstock and cost dynamics: the critical lever
1,4-Butanediol (BDO) remains the primary upstream feedstock and is the most significant near-term cost driver. Regional BDO price snapshots from March 2026 indicate observable differentials across North America, Europe and Northeast Asia—price spreads that are large enough to change sourcing and hedging behaviour. Our pricing model demonstrates how a 10–20% sustained shift in regional BDO can reconfigure supplier competitiveness and prompt short-run arbitrage flows or contractual escalations.
For decision-makers: integrate feedstock scenarios into procurement, and stress-test production economics for any capacity moves planned in 2026. The full report contains executable Monte Carlo scenarios and contract negotiation playbooks calibrated to these dynamics.
Regulatory and trade landscape: constraints and operational levers
- United States: Operational controls and handling rules treat GBL as a controlled precursor in many contexts; distribution systems must be auditable and aligned with law-enforcement thresholds.
- European Union: REACH obligations make registration, risk assessment and downstream-user documentation essential—particularly for industrial handlers and formulators.
- China: Recent adjustments to import/export licensing for certain product concentrations create tactical easing in specific trade flows—an important nuance for companies planning supply-chain re-routing or export expansion.
Regulatory agility will be a competitive advantage in 2026; companies that build compliance-forward logistics and contract templates now will avoid shipment delays and qualification setbacks later.
Near-term tactical playbook for 2026 (what to do in the next 6–12 months)
- Procurement: Lock in blended supply contracts that include regional optionality and mechanism to capture short-term arbitrage should BDO spreads widen further.
- Operations: Prioritise ramping high-purity streams where demand from electronics and battery sectors is validated; small purity upgrades can command meaningful premium capture.
- Commercial: Differentiate offers with lifecycle claims and documented PCF where customers in pharma and electronics require sustainability proof points.
- M&A & Partnerships: Screen bolt-on assets that increase regional logistics flexibility or provide ingress to premium end-markets rather than chasing undifferentiated tonnage.
Why PW Consulting’s report is uniquely useful for 2026
Beyond headline numbers, the report’s practical value is its decision-orientation. We translate scenario outputs into immediate tactical actions, supply-contract templates, and CAPEX decision gates—materials designed to be operationalised in 2026 planning cycles. The combination of plant-level intelligence, a calibrated pricing model tied to BDO movements, and a regulatory compendium makes the report a single-source briefing for executive teams facing trade-offs between growth, margin protection and regulatory compliance.
Next steps and access
If your 2026 strategy includes supply-chain optimisation, CAPEX reprioritisation, or acquisition screening in industrial solvents and intermediates, PW Consulting’s full report contains the proprietary datasets, interactive models and supplier diligence packages required to act with confidence. For complete segmentation tables, plant-level capacity data, company scorecards and the scenario modelling workbook, please follow the link on our release page to purchase the full Industrial Grade GBL Market report.
PW Consulting will also be hosting a live briefing for clients in Q3 2026 to walk through the report’s scenario tools and to run bespoke sensitivity exercises for specific corporate portfolios—slots are limited.
For detailed analysis of this topic, please visit the official page: Industrial Grade Gamma Butyrolactone Gbl Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com