

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Press Hardening Machine Market Poised for 7.32% CAGR, Surging to USD 1,674.65 Million by 2032

Press Hardening Machine Market: Strategic Playbook for 2026 Decision-Makers
PW Consulting today publishes a focused industry briefing drawn from our full Press Hardening Machine Market report (base year 2025, forecast 2026–2032). This executive-oriented release synthesizes the implications senior leaders need to act on in 2026 — from capital allocation and supplier selection to technology roadmaps and M&A strategy — while preserving the granular subsegment intelligence that makes the full report essential for implementation teams.
Press Hardening Machine Market
Market snapshot: momentum and medium‑term opportunity
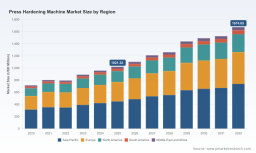
The press hardening equipment market has transitioned from a niche specialty into a core enabler of structural lightweighting across automotive, commercial vehicle and select industrial segments. Our consolidated market model records an increase in overall industry revenues from roughly USD 715 million in 2020 to just over USD 1.02 billion in 2025 (USD Million, nominal). The market is forecast to continue expanding through the 2026–2032 horizon at a compound annual growth rate of 7.32%, reaching an estimated USD 1.67 billion by 2032.
Press Hardening Machine Market
This pace reflects the intersection of three durable forces: accelerating adoption of ultra‑high strength steels (UHSS) for crash management and mass reduction, manufacturer investments in faster and more energy‑efficient lines, and continuing OEM demand for integrated, traceable production capable of meeting stringent automotive heat‑treat quality regimes.
Press Hardening Machine Market
Why 2026 is a strategic inflection year
- Regulatory and safety-driven material shifts. Press hardening enables production of components using UHSS grades up to 2000 MPa, supporting vehicle lightweighting strategies that in some modern architectures assign 20–40% of bodyweight to press‑hardened parts. That structural role elevates press hardening from a cost item to a safety and performance enabler.
- Efficiency becomes a board‑level KPI. Recent vendor innovations show step‑change energy improvements: servo‑driven press platforms paired with multi‑layer furnace concepts claim material reductions in line energy intensity. Buyers in 2026 should prioritize solution footprints that materially cut energy and improve throughput per capita, because energy and carbon intensity are now central to procurement and total cost of ownership.
- Heat‑treat process traceability is table stakes. Compliance to automotive heat‑treat standards increasingly relies on in‑line monitoring with pyrometers, infrared imaging and linked analytics. The combination of process control and machine‑level IIoT capability is differentiating suppliers and shaping warranty and quality accountability models.
- Input cost volatility compresses margins. Steel feedstock remains the dominant cost in press‑hardening value chains. With raw materials representing a large share of steel production costs, procurement teams must bake volatility scenarios and hedging options directly into capital and operating models for new lines.
Competitive landscape — consolidation, capabilities and strategic postures
The market is moderately consolidated. The three largest suppliers account for a majority share of global installed capacity, and the top five capture more than two‑thirds of the market by revenue. That concentration shapes pricing dynamics, technology diffusion, and the bundling of turnkey services such as furnace design, automation, tooling and in‑line inspection.
- AP&T (Ulricehamn, Sweden). A long‑standing pioneer in press hardening, AP&T combines complete turnkey production solutions with energy‑focused system design. Its SkyLines concept and multi‑layer furnace architectures target large, complex EV structures — with vendor‑reported energy gains that buyers will see reflected in total cost models. AP&T’s emphasis on integrated monitoring and modular line concepts positions it as a preferred partner for OEMs seeking scalability and sustainability.
- Fagor Arrasate (Arrasate, Spain). Known for fully automated integrated systems, Fagor Arrasate continues to compete on delivering high‑output, tightly integrated press hardening lines with sophisticated servo‑hydraulic drive architectures and multilevel furnace solutions — a strong value proposition for high‑mix, high‑volume programs.
- Schuler Group (Göppingen, Germany). Schuler’s technology portfolio targets high‑precision, high‑cadence production with architectures that support multiple part types per line at elevated throughput. For programs where takt and cycle efficiency are primary constraints, Schuler is frequently shortlisted.
- Macrodyne Technologies Inc. (Canada). A strong supplier of custom hydraulic and servo hot‑stamping presses, Macrodyne’s recent trade‑show activity reflects its continuing focus on heated platen and specialty forming solutions — a fit for Tier‑1 suppliers and integration projects with complex part geometry.
- Loire Gestamp / AFM (Hernani, Spain). With a history in hydraulic hot stamping lines and associated furnaces, Loire Gestamp remains relevant where proven hydraulic architectures and tailored line engineering are prioritized over platform standardization.
Recent vendor activity confirms two directional bets in the vendor community: deeper vertical integration of furnace + press + automation to deliver predictable quality and energy outcomes, and productizations that reduce customization lead times for EV platform programs. AP&T’s SkyLines presentation (mid‑2025) and Macrodyne’s MACH 2026 showcase illustrate these twin dynamics: energy and scalability on one hand; niche, high‑complexity capacity on the other.
Strategic implications for buyers and investors in 2026
- CapEx framing and total cost of ownership. Procurement must move beyond headline machine price. Energy consumption, maintenance intervals, monitoring capability and retrofit potential materially change ROI timelines. Select line architectures that preserve upgrade paths for controls and sensing — this reduces lifecycle risk.
- Technology choices must align with program mix. Servo‑mechanical platforms offer energy arbitrage and throughput advantages for high‑mix, variable run programs; hydraulic systems retain advantages for specific heavy‑forming applications. Our report provides scenario matrices that help teams map line type to program economics.
- Supplier risk and supply chain resilience. Given the concentration profile, buyers should pursue a dual strategy: a primary strategic partner plus validated secondary suppliers to mitigate lead‑time and geopolitical risk. Near‑term raw material exposure suggests integrating steel procurement strategies into machine purchase decisions, including indexed contracts and safety stock strategies.
- Service and aftermarket as margin levers. As lines become more instrumented, opportunities for performance‑based service contracts, remote diagnostics and outcome‑linked warranties expand. Investors and OEMs should quantify serviceable revenue as part of lifecycle models.
- M&A and partnership playbook. Consolidation and capability gaps create actionable targets. Buyers with systems integration strengths may find attractive bolt‑on targets among regional line builders; conversely, established OEMs can accelerate capability by securing long‑term supplier partnerships that include technology roadmaps and co‑development clauses.
What PW Consulting’s full report provides (practical contents)
The complete study delivers operationally actionable intelligence designed for program managers, procurement leads, plant engineering, and corporate strategy teams. Core deliverables include:
- Historical market sizing (2020–2025) and a granular forecast through 2032 with scenario sensitivity to energy and raw material price swings;
- Segmented demand analysis by geography, machine configuration and component families, with buyer requirement matrices (note: detailed subsegment tables and vendor share models are available in the full report);
- Vendor benchmarking and capability maps covering control systems, furnace architectures, automation and in‑line monitoring;
- Capital and operating expenditure models, including payback and NPV templates that fold in energy consumption and material cost assumptions;
- M&A target screening criteria and a shortlist of priority acquisition archetypes for private equity and strategic acquirers;
- Implementation playbooks: procurement checklists, commercial terms to negotiate, test acceptance criteria for plant trials, and a 12–36 month deployment roadmap.
Methodology and confidence indicators
The report uses a hybrid research methodology: supplier financials and shipment data, primary interviews with manufacturers and OEMs, plant‑level intake and commissioning schedules, together with bottom‑up cost modelling that explicitly includes steel feedstock exposure and energy consumption. The base year is 2025, historical coverage is 2020–2025, and forecasts extend 2026–2032. Our concentration metrics and market share assessments are constructed to help executives assess supplier bargaining power and consolidation risk.
How to use this insight in 90 days
- Prioritize a cross‑functional steering team (procurement, engineering, sustainability, legal) to convert report scenarios into a Program Decision Matrix;
- Run two vendor pilots: one focused on energy‑efficient servo + multi‑layer furnace options, one focused on high‑complexity hydraulic/transfer solutions;
- Integrate raw material price hedging clauses into supplier contracts and model P&L sensitivity across +/- 15% steel cost swings; and
- Create a service and performance KPI framework that aligns payment milestones with demonstrated energy and quality results during a defined ramp period.
PW Consulting’s Press Hardening Machine Market report is positioned to be the practical playbook for 2026 capital allocation and supplier strategy. If your organization must decide on line investments, retrofit budgets or strategic supplier partnerships this year, the report equips you with the scenario tools, vendor maps and execution checklists to move from deliberation to deployment with confidence.
To access the full dataset, detailed segmentation tables, vendor scorecards and procurement templates, please visit our report page or contact PW Consulting directly for a briefing and customized workshop.
For detailed analysis of this topic, please visit the official page: Press Hardening Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com