

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Aircraft Interior Lighting Market to Grow from USD 1,450 Million in 2025 to USD 2,306.65 Million by 2032 at a 6.85% CAGR

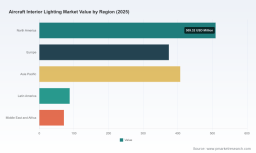
Aircraft Interior Lighting Market: Strategic Imperatives for 2026 — PW Consulting Report
PW Consulting today releases a forward-looking industry brief distilled from our full Aircraft Interior Lighting Market study. The global market for aircraft interior lighting is entering a decisive growth phase: from a base of USD 1,450.0 Million in 2025, our model projects a steady compound annual growth rate (CAGR) of 6.85% through the 2026–2032 forecast window, culminating in a market approaching USD 2,306.65 Million by 2032. These headline figures underscore a resilient, technology-driven expansion that will shape procurement, retrofit, and product roadmaps for OEMs, aftermarket specialists, lessors and airlines in 2026 and beyond.
Aircraft Interior Lighting Market
Why 2026 Is a Strategic Inflection Point
-
Convergence of drivers. Energy-efficient LEDs and emerging OLED technologies, coupled with advances in human‑centric lighting (HCL) and chronobiology-based control systems, are shifting cabin lighting from pure utility to a differentiating passenger-experience platform. The technical benefits—long lifespans (100,000+ hours), significant weight and energy savings, and highly configurable color rendering—are now commercially mature and widely demanded.
Aircraft Interior Lighting Market -
Aftermarket and retrofit momentum. Airlines and lessors pursuing revenue enhancement and cabin renewal are accelerating retrofit programs. As an illustrative benchmark from our field work, an LED cabin lighting upgrade for a typical regional aircraft (covering up-wash, down-wash, reading, lavatory and galley) averages around USD 70,000 including installation—an actionable datapoint buyers can use in total cost of ownership models.
Aircraft Interior Lighting Market -
Regulatory and standards backdrop. Compliance with EASA CS-25 and FAA TSO mandates, together with SAE specification updates, continues to be a gating factor for market entry and product updates. Certification timelines and STC approvals will remain critical operational constraints for new entrants and retrofit vendors alike.
-
Concentrated supplier structure. Market concentration is material: the leading three suppliers control a significant share of the market, and the top five present an even larger combined footprint. For buyers and investors this translates into a marketplace where strategic partnerships, certification portfolios and scale matter as much as product innovation.
What the PW Consulting Report Delivers — Practical Tools for 2026 Decision-Makers
Our full report is organized to be a tactical playbook rather than a purely academic assessment. Key contents include:
-
Actionable market sizing and validated forecasts (2020–2032) with scenario analysis tailored to supply shocks, certification delays and accelerated retrofit cycles.
-
Regulatory and certification matrix mapping EASA, FAA and SAE requirements against product categories and retrofit pathways—highlighting timelines, testing dependencies and common failure modes.
-
Supplier scorecards and procurement playbooks covering technical capability, STC/certification depth, aftermarket reach, and integration risk—designed for sourcing teams evaluating Tier‑1 and Tier‑2 suppliers.
-
Technology roadmaps for LED, OLED, and human‑centric lighting systems, including durability, lifecycle replaceability, control interfaces and retrofitability considerations.
-
Cost‑benefit and TCO templates preconfigured for fleet-level analysis, enabling rapid estimation of payback under multiple utilization and energy-price scenarios (with a separate retrofit cost estimator for regional, narrowbody and widebody platforms).
-
M&A and alliance playbooks that identify value levers—intellectual property, STC portfolios, aftermarket service networks—and a prioritized approach to target screening and diligence.
Competitive Landscape — Positioning, Strengths and Tactical Priorities
The cabin lighting arena is populated by legacy aerospace systems integrators, specialized lighting houses, and nimble aftermarket players. Based on our research and direct industry engagement, the competitive dynamics can be summarized as follows:
-
Tier‑1 integrators (broad systems capability): Firms with full cabin portfolios and strong OEM relationships are leveraging integrated-system offerings—combining cabin wash, mood lighting, reading lights and advanced luminous panels—to lock in platform-level specifications. Their strength lies in certification expertise and cross-platform scale.
-
Specialist lighting companies: These players differentiate through modularity, aesthetics, and innovative light sources (e.g., RGBW strips, decorative finishes). They are frequently faster to market with retrofit-friendly solutions and customizable finishes valuable to airlines seeking brand differentiation.
-
Aftermarket and STC-focused vendors: Companies with strong STC portfolios and FAA approvals are key enablers for operators wanting rapid fleet upgrades without long OEM lead-times. Their strategic value increases as retrofit demand grows.
Selected company observations (high level):
-
Collins Aerospace (RTX): Extensive systems depth across commercial, business and military segments and a clear focus on advanced products (e.g., high‑fidelity luminous panels). Their competitive advantage is end‑to‑end integration and existing OEM attachments.
-
Diehl Aviation: With decades of cabin lighting experience and visible trade‑show activity, Diehl remains a reference supplier for OEMs and airlines seeking integrated, human‑centric solutions—particularly where platform commonality is required.
-
Safran Cabin: Known for high‑CRI solutions and retrofit packages, Safran’s portfolio supports operators prioritizing passenger comfort and maintainability.
-
Astronics & STG Aerospace: Both have positioned themselves around innovative LED strip lighting, programmable mood systems and plug‑and‑play retrofit kits—making them attractive to airlines and completion centers seeking rapid installation and customization.
-
SCHOTT, Luminator, Bruce Aerospace, Aircraft Lighting International, American Bright LED: These players fill critical niches—from decorative, high‑quality finishes to FAA‑approved RGBW systems and custom modules—that support differentiated cabin concepts and aftermarket upgrades.
Recent market signals reinforce these trends: several manufacturers showcased advanced integrated and decorative lighting at the industry expos in 2026, and a number of aftermarket vendors continue to secure FAA approvals for RGBW and three‑wire cabin systems—demonstrating both product maturity and the critical role of certification as a market access filter.
Implications by Stakeholder
-
OEMs: Prioritize ecosystem compatibility and scalable architectures. Offer open control interfaces where possible to capture downstream retrofit opportunities and reduce long‑term support liabilities.
-
Airlines & Lessors: Treat cabin lighting as a revenue and brand tool. Use modular designs and STC-compliant retrofit packages to accelerate cabin refresh cycles while managing downtime and installation costs.
-
Aftermarket Suppliers: Invest in certification pipelines and build strong service networks; the ability to deliver fleet‑wide, fast‑cycle STCs will be a decisive competitive edge.
-
Investors & M&A Teams: Seek targets with combined IP, STC assets, and aftermarket channels; consolidation will likely favor players who can scale certification capabilities and integration services.
Strategic Recommendations for 2026
-
Prioritize human‑centric lighting pilots on representative routes to quantify passenger experience and operational benefits before committing to fleetwide rollouts.
-
Adopt modular, serviceable lighting components and standardized control interfaces to reduce retrofit complexity and future obsolescence risk.
-
For suppliers, invest selectively in STC pipelines and aftermarket service models rather than attempting to be all things to all customers; niche specialization with certification scale wins in the near term.
-
Buyers should incorporate supplier concentration risk into their sourcing decisions and consider multi‑vendor strategies to mitigate single‑supplier exposures.
-
Monitor raw material and component supply chains for LED drivers and critical semiconductors; design for multiple validated sources to avoid program delays.
-
Leverage PW Consulting’s scenario-based TCO templates to stress-test investment cases under different energy price and utilization assumptions.
Accessing the Full Intelligence
This executive brief is a concise synthesis of the full PW Consulting Aircraft Interior Lighting Market report, which contains granular scenario outputs, procurement scorecards, and an interactive retrofit cost model. In line with our “trailer” approach, we have deliberately presented strategic conclusions, supplier analysis and operational recommendations while reserving the detailed segmentation datasets, supplier-specific market shares and appended financial models for the full report. For procurement teams, engineering leaders and corporate strategists preparing 2026 budgets and technology roadmaps, the complete study is a practical toolkit to accelerate decision-making under uncertainty.
To explore the detailed segment-level forecasts, supplier profiles, certification trackers and download our fleet-level TCO tool, please refer to PW Consulting’s Aircraft Interior Lighting Market report landing page.
For detailed analysis of this topic, please visit the official page: Aircraft Interior Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com